
Himax Technologies And 2 Other Top Growth Stocks With Strong Insider Ownership
The United States market has remained flat over the last week but is up 15% over the past year, with earnings expected to grow by 18% annually. In this environment, growth companies with high insider ownership can be particularly appealing as they often align management's interests with those of shareholders, potentially driving robust performance.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.4% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
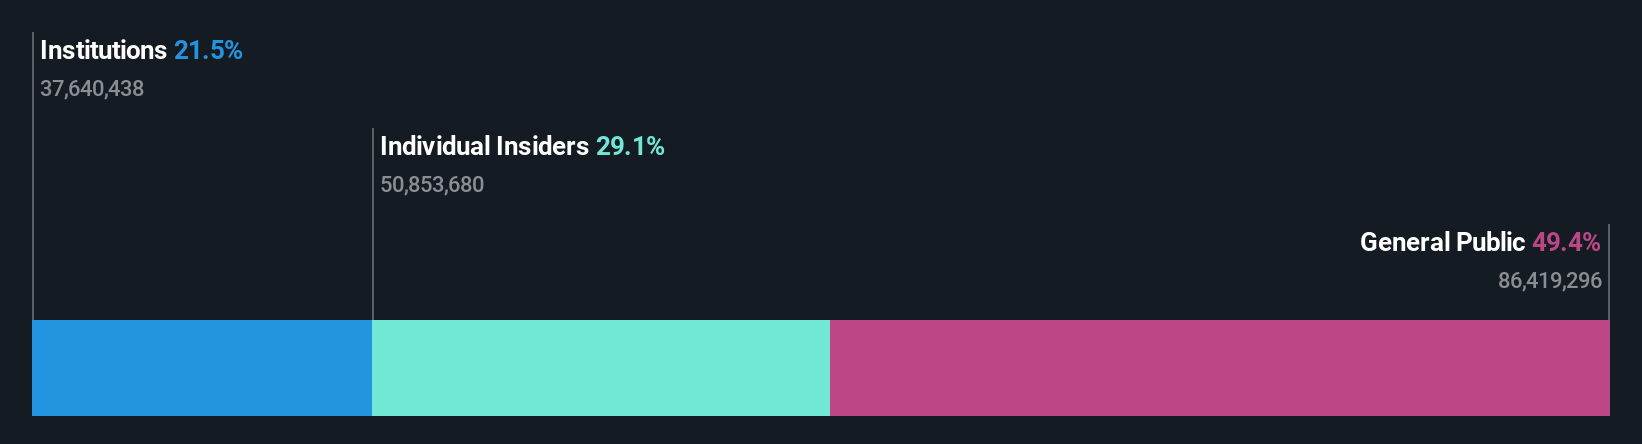
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
Below we spotlight a couple of our favorites from our exclusive screener.
Himax Technologies (HIMX)
Simply Wall St Growth Rating: ★★★★★★
Overview: Himax Technologies, Inc. is a fabless semiconductor company specializing in display imaging processing technologies across various regions including China, Taiwan, Korea, Japan, the United States, and Mexico with a market cap of approximately $2.32 billion.
Operations: Himax's revenue segments include display driver ICs, timing controllers, CMOS image sensors, wafer level optics products, and LCOS microdisplays across multiple international markets.
Insider Ownership: 29.1%
Revenue Growth Forecast: 24.7% p.a.
Himax Technologies is positioned for robust growth, with revenue expected to outpace the US market at 24.7% annually, and earnings projected to grow significantly at 70.2% per year. Recent product innovations, such as their advanced automotive TDDI solutions and WiseEye palm vein technology integration into smart locks, highlight their commitment to cutting-edge development. However, profit margins have decreased from last year, indicating potential challenges in maintaining profitability amidst rapid expansion efforts.
- Click here and access our complete growth analysis report to understand the dynamics of Himax Technologies.
- Our comprehensive valuation report raises the possibility that Himax Technologies is priced higher than what may be justified by its financials.
Brady (BRC)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Brady Corporation manufactures and supplies identification solutions and workplace safety products across the Americas, Asia, Europe, and Australia with a market cap of approximately $4 billion.
Operations: The company's revenue segments consist of $1.11 billion from the Americas & Asia and $554.95 million from Europe & Australia.
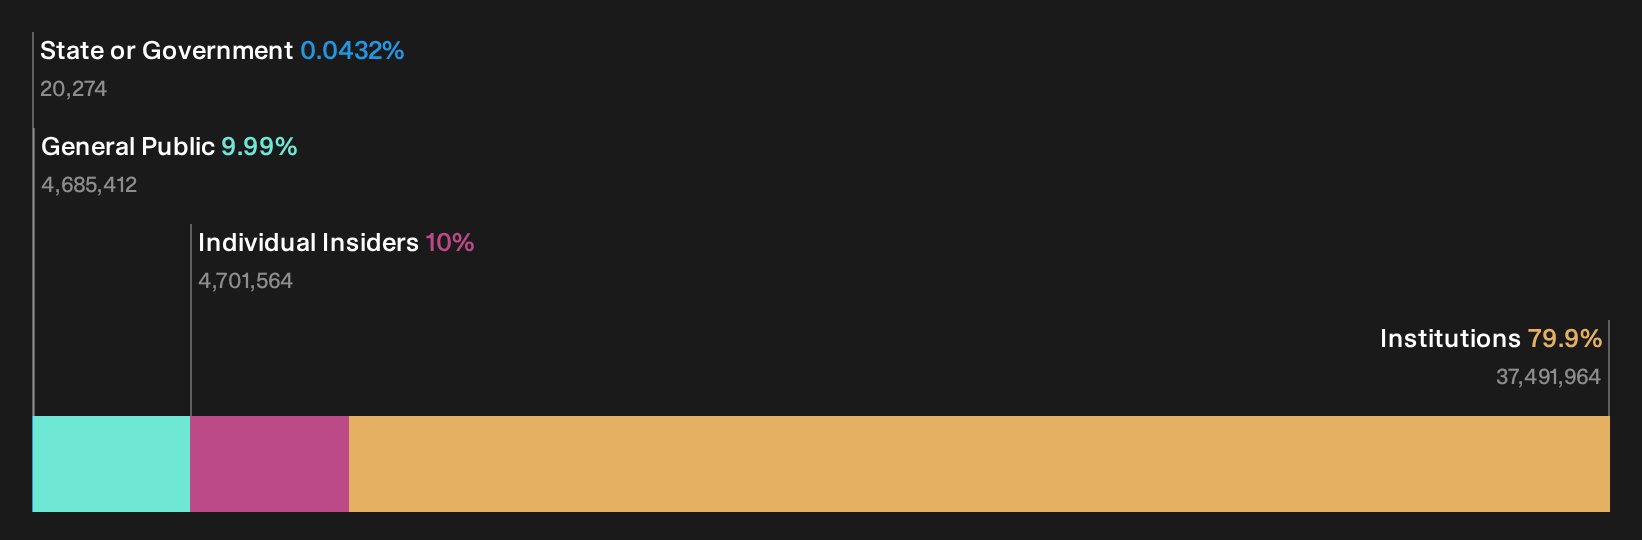
Insider Ownership: 10%
Revenue Growth Forecast: 26.6% p.a.
Brady Corporation is poised for significant growth, with revenue expected to increase by 26.6% annually, surpassing the US market average. Despite substantial insider selling over the past three months, Brady's earnings are forecast to grow at 22.8% annually. Recent financial results show a year-over-year increase in full-year sales to US$1.66 billion and net income of US$205.38 million, alongside a completed share buyback program totaling US$255.25 million since May 2022.
- Click here to discover the nuances of Brady with our detailed analytical future growth report.
- Upon reviewing our latest valuation report, Brady's share price might be too pessimistic.
Warby Parker (WRBY)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Warby Parker Inc. operates as a retailer of eyewear products through both retail and e-commerce platforms in the United States and Canada, with a market cap of approximately $3.13 billion.
Operations: The company's revenue comes from its Holistic Vision Care segment, amounting to $911.61 million.
Insider Ownership: 13.4%
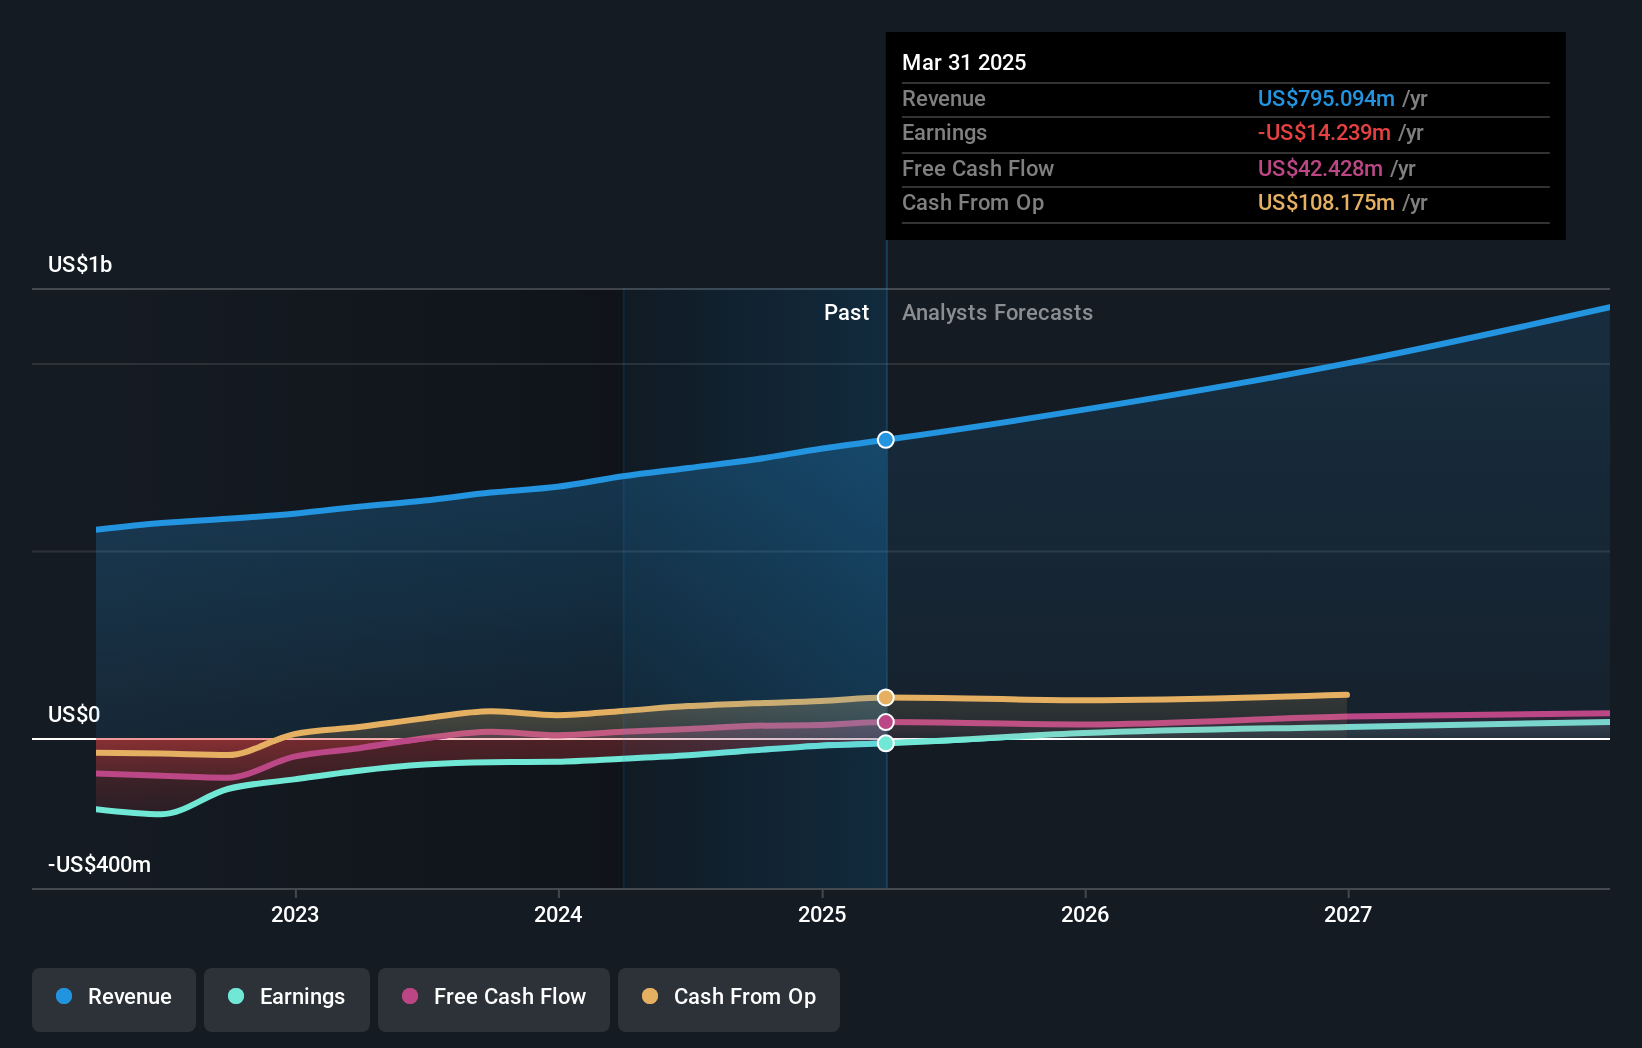
Revenue Growth Forecast: 18.4% p.a.
Warby Parker exhibits strong growth potential with revenue expected to increase by 18.4% annually, outpacing the US market average. The company recently reported a positive shift in profitability, with Q2 2026 net income reaching US$4.64 million compared to a loss last year. Earnings are projected to grow significantly at 76.1% per year over the next three years. Despite no recent insider trading activity, Warby Parker maintains substantial insider ownership and reaffirmed its fiscal year guidance for continued revenue growth.
- Unlock comprehensive insights into our analysis of Warby Parker stock in this growth report.
- Our expertly prepared valuation report Warby Parker implies its share price may be too high.
Where To Now?
- Click this link to deep-dive into the 187 companies within our Fast Growing US Companies With High Insider Ownership screener.
- Searching for a Fresh Perspective? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 33 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com