
Is Butterfly Network (BFLY) Expensive As Bridge Neurotech And Mendaera Deals Lift Its Story?
Why Butterfly Network’s Bridge Neurotech Deal Matters For Investors
Butterfly Network (BFLY) just signed a multi-year research and development agreement with Bridge Neurotech, putting its Ultrasound-on-Chip technology at the center of non surgical brain computer interface exploration.
The arrangement includes licensing fees, milestone-based payments, and committed hardware purchases, so the deal ties Butterfly’s brain imaging ambitions directly to concrete commercial terms rather than purely experimental work.
Butterfly Network’s share price has moved sharply over the year, with a 1-day share price return of 2.74% and a 30-day share price return of 12.55%. The 1-year total shareholder return of 258.70% and the very large 3-year total shareholder return of about 9x suggest strong momentum that recent Bridge Neurotech and Mendaera agreements appear to be feeding into, shifting expectations around growth potential and risk.
Scan beyond Butterfly Network and compare it with carefully filtered 33 healthcare AI stocks that are also advancing AI driven medical technology into new use cases.
Butterfly Network now trades about 38% below the average analyst target after a sharp run, with the stock up about 259% over 1 year. Is that a bargain or a warning sign for valuation work next?
Most Popular Narrative: 28% Undervalued
Butterfly Network’s most followed narrative pegs fair value at $11.40 using a 7.52% discount rate, compared with the last close at $8.25. This frames the recent rally as still leaving a valuation gap on this view.
Ongoing advances in semiconductor manufacturing, new product launches (e.g., iQ Station, upcoming fourth-generation P5 technology), and cost containment efforts are driving product miniaturization and lower production costs, supporting higher gross margins and a credible path to sustainable profitability at scale as portable imaging adoption accelerates globally.
See why 37 investors see Butterfly Network as 28% undervalued.
Result: Fair Value of $11.40 (UNDERVALUED)
Still, delays in closing large enterprise and medical school deals, along with ongoing high R&D spend, could pressure Butterfly Network’s growth narrative and push profitability further into the future.
Find out about the key risks to this Butterfly Network narrative.
Another View: Butterfly Network Looks Expensive On Sales
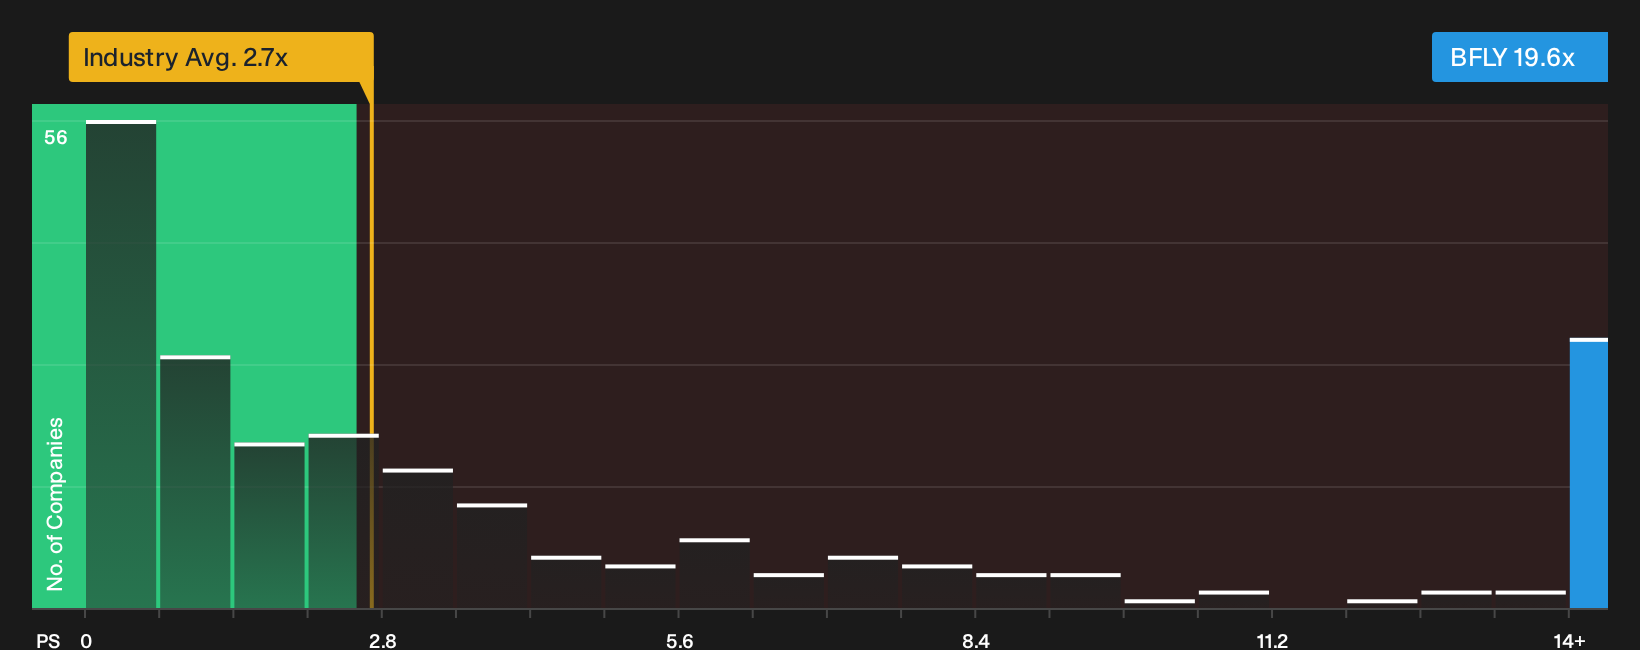
That fair value narrative presents Butterfly Network as undervalued, but the picture changes when looking at the P/S ratio. The stock trades at 19.6x sales, compared with 5.7x for peers and a fair ratio of 4.9x, which suggests that rich expectations may be reflected in the price.
If the market moved closer to that fair ratio, a significant amount of optimism would need to be re-rated. This raises the question of how comfortable investors might be with paying such a premium for growth that is still tied to an unprofitable business model.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Butterfly Network so far. With both concerns and reasons for optimism on the table, move quickly from the headline to the evidence and weigh the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Butterfly Network?
If Butterfly Network has sharpened your interest, do not stop with a single ticker. Broader idea hunting gives you better context, better comparisons, and better decisions.
- Target potential upside by scanning a focused pool of 20 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Protect your downside by reviewing a curated mix of 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Zero in on quality at a discount by tracking a filtered set of 29 high quality undervalued stocks where fundamentals and pricing appear more aligned in your favor.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com