
Did Resort Software Expansion Just Shift Agilysys (AGYS) Investment Narrative?
- Agilysys, Inc. reported that 7 Cedars Resort Properties has expanded its use of the Agilysys ecosystem across hotel, casino gaming, golf, retail, and multiple food and beverage outlets, deploying solutions such as Versa PMS, InfoGenesis POS, Agilysys Book, and several ancillary tools.
- The 7 Cedars rollout shows how a single hospitality client can adopt a wide slice of the Agilysys product stack to centralize operations, automate manual work, and manage reservations and guest interactions across many venues on one platform.
- We will now look at how Agilysys' deeper 7 Cedars deployment could inform the investment narrative built around its integrated SaaS ecosystem.
Scan how Agilysys applies its hospitality SaaS toolkit, then broaden your watchlist with list of solid balance sheet and fundamentals (25 results) that could support similarly complex, multi-venue operations.
Agilysys Investment Narrative Recap
To own Agilysys, you need to believe that an integrated hospitality SaaS stack can keep winning multi venue rollouts and deepen wallet share per property. The 7 Cedars deal fits that logic, showing one resort using Agilysys across property management, POS, bookings, events, marketing and more on a single platform.
The near term swing factor still looks like execution on this SaaS pipeline and backlog, not one property win. The biggest risk remains concentration in hospitality, where any slowdown in travel or casino spending could pressure recurring revenue, especially with higher operating expenses tied to product development and sales capacity.
The 7 Cedars expansion aligns closely with Agilysys' push toward cloud native, subscription software and heavier cross sell per customer. One resort running Versa PMS, InfoGenesis POS, Book, Express Mobile, Sales & Catering, DataMagine and Digital Marketing illustrates the integrated ecosystem that underpins recurring revenue and higher average spend per client.
That scope also highlights execution risk. As deployments grow in complexity, implementation timelines, support quality and compliance needs could weigh on costs and margins if not well managed. The key question for readers is whether Agilysys can repeat this type of full stack deployment across more properties without eroding profitability.
What The Analyst Framework Implies For Agilysys
Agilysys' narrative projects US$523.9 million revenue and US$91.9 million earnings by 2029. This assumes 16.6% yearly revenue growth and roughly a doubling of earnings, with an increase of about US$49 million from US$42.9 million today.
The analyst playbook around Agilysys is very explicit. To match current targets, you would need to accept revenue growing at 16.6% a year, profit margins stepping up from 13.0% to 17.5%, and earnings climbing from US$42.9 million today to US$91.9 million by 2029.
That structure matters more than the headline price targets. The story is built on a larger top line, richer margins and modest share count expansion of 0.86% a year, all flowing into higher earnings and a future P/E of 53.7x that still sits well above the US software sector at 28.6x.
For you as an investor, the key judgment is simple. Decide whether a hospitality focused software provider with heavy investment in product and sales can justify that 2029 profile of US$523.9 million in sales and US$91.9 million in profit, or whether those assumptions feel stretched against the risks around travel cycles, competition and ongoing spend on growth.
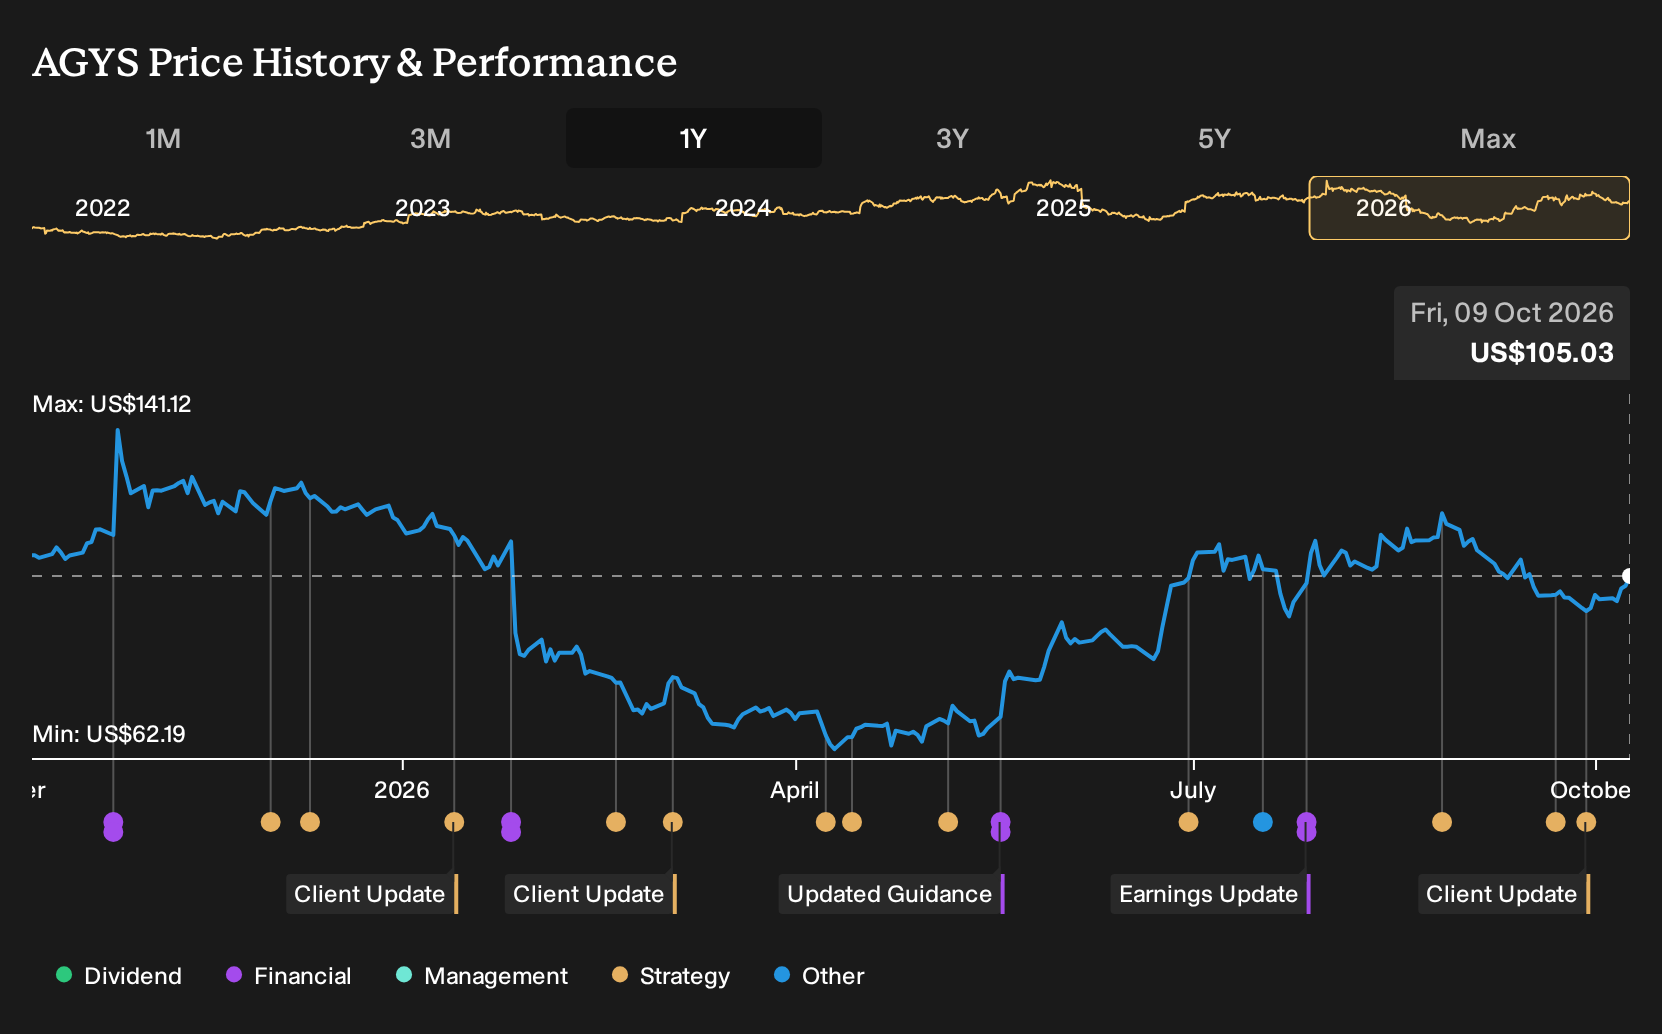
Uncover why Agilysys' fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view leans hard into execution as a catalyst. The most optimistic Agilysys analysts were already modeling US$592.2 million of revenue and US$102.4 million of earnings by 2029 before this 7 Cedars rollout. That camp assumes faster multi module wins and much stronger margins, which may or may not adjust as this case study sinks in.
Explore 4 other Agilysys fair value estimates, including one that suggests as much as 51% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Agilysys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agilysys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilysys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Agilysys?
If the Agilysys story has sharpened your thinking about software driven business models, use that same lens to compare other potential opportunities in just a few minutes with the Simply Wall St Screener.
- If you prefer resilient balance sheets and steady fundamentals that can handle tougher conditions, then shortlist candidates using our 31 resilient stocks with low risk scores.
- If you are interested in companies that our filters flag as potentially trading below their estimated worth, start by scanning the 29 high quality undervalued stocks.
- If you want ideas that combine robust finances with cleaner debt profiles, build a watchlist straight from the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com