
Will Completed Store Expansion Change Ross Stores (ROST) Narrative
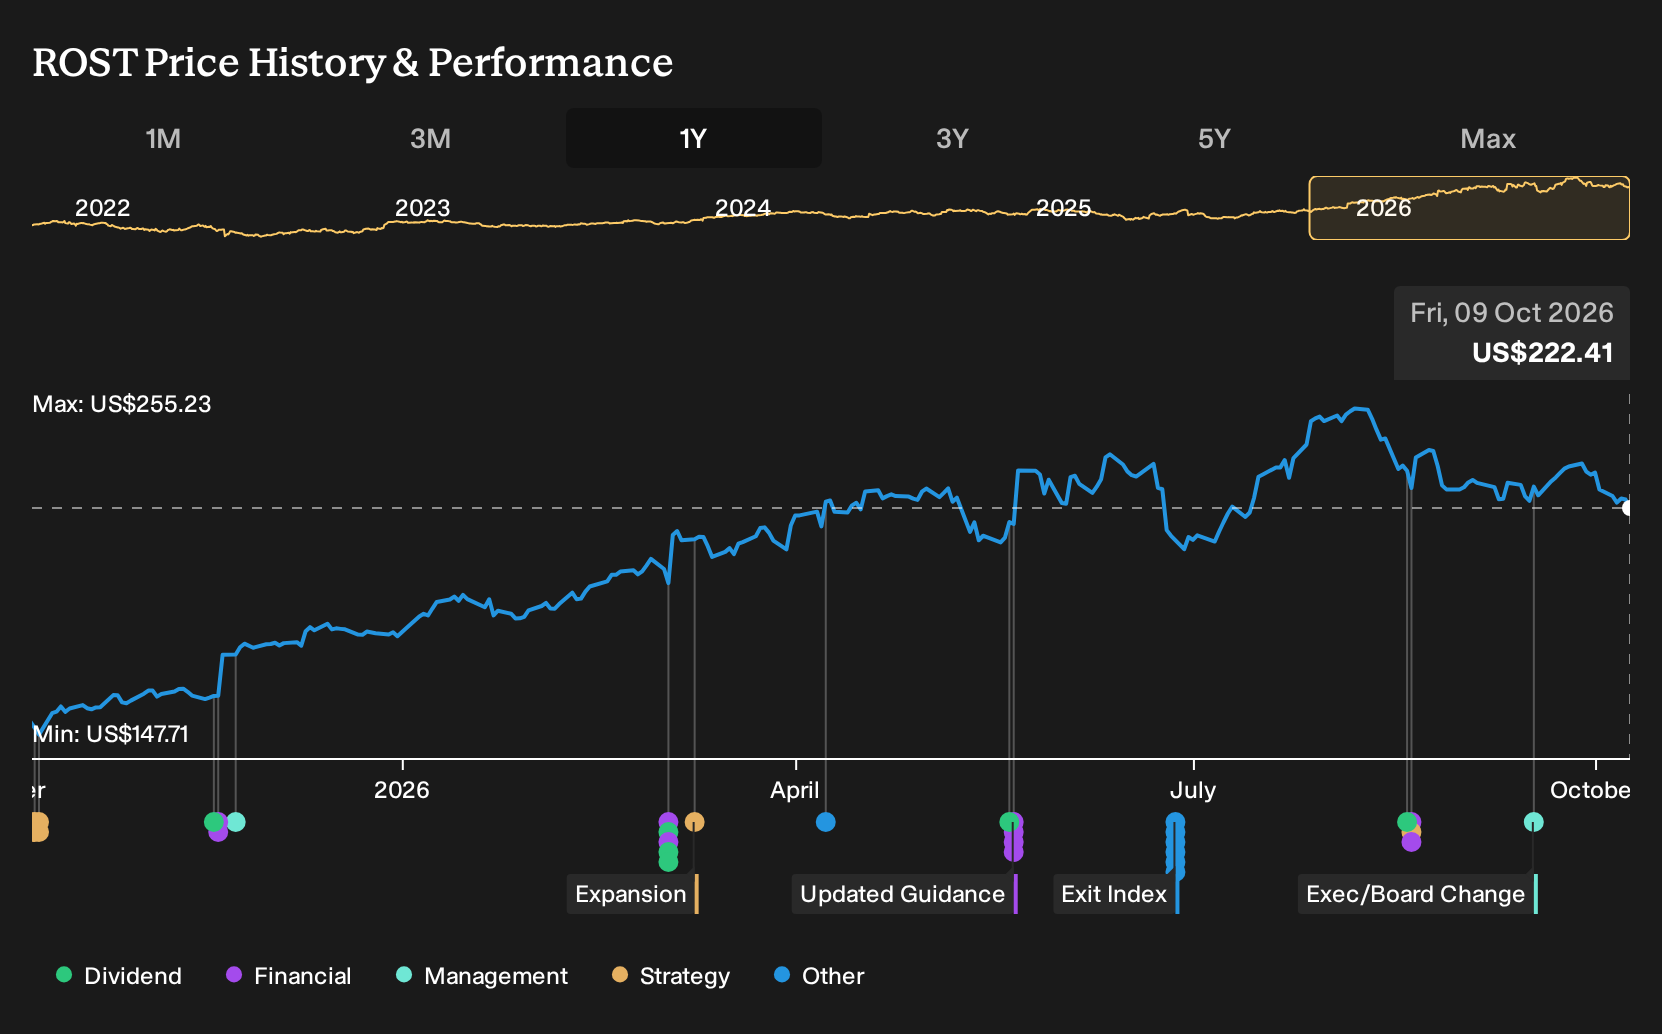
- Ross Stores recently finished its fiscal 2026 expansion plan, opening 41 Ross Dress for Less and 10 dd's DISCOUNTS across 17 states, including its first locations in Massachusetts.
- The push into new geographies, alongside a stated ambition to scale to at least 2,900 Ross and 700 dd's stores, highlights management's focus on store-driven growth rather than relying solely on same-store sales.
- We will look at how Ross Stores' investment narrative lines up with the completed 2026 store rollout, including the new Massachusetts entry.
Scan beyond Ross Stores and see how other off price and resilient retailers line up using our hand picked 31 resilient stocks with low risk scores as a starting universe.
Ross Stores Investment Narrative Recap
For Ross Stores, the core belief is that off price retail can keep pulling in a wide mix of shoppers while new locations get built out methodically. The 2026 rollout of 115 stores, now completed, fits that story and keeps the 5% unit growth framework intact. The key near term swing factor remains how well these fresh stores ramp, especially in newer regions like Massachusetts.
The biggest immediate risk sits on the cost side, not the sales line. Higher fuel and freight costs, combined with a larger capital spend of about US$1.1b for the year, put pressure on margins if store productivity or merchandise margins soften. The latest opening wave does not significantly change that risk profile on its own.
The most relevant recent update is management’s confirmation that Ross Stores has now completed its fiscal 2026 expansion plan with 115 net new locations. That matters because prior commentary highlighted that newer store cohorts were running at 70% to 75% of mature store sales or better. Investors can now watch whether this larger 2026 cohort tracks a similar pattern.
This rollout also ties directly into existing catalysts around customer growth and access to closeout merchandise. A broader footprint gives the retailer more shelf space to deploy its buying model, which has recently been associated with merchandise margin expansion of 85 to 110 basis points. Execution risk on these new stores remains, yet the operational story is now less about announcements and more about how these units settle into steady productivity over the next few years.
Ross Stores' narrative projects US$30.3b revenue and US$3.2b earnings by 2029. This assumes 7.4% yearly revenue growth and an earnings increase of about US$0.5b from US$2.7b today.
Uncover how Ross Stores' fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Ross Stores fixates on the risk that heavy capital spending could outpace demand. Before this expansion news, the lowest analysts were only penciling in about 6.8% annual revenue growth and roughly US$2.8b in 2029 earnings. That is a much more cautious story. Use it as a prompt to compare multiple narratives, and then decide which assumptions feel realistic to you.
Explore 3 other Ross Stores fair value estimates, including one that suggests as much as 66% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ross Stores research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ross Stores. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ross Stores' overall financial health at a glance.
Looking for more investment ideas beyond Ross Stores?
Once you have a view on Ross Stores, widen the lens and compare it with other businesses that fit the kind of risk, income, or quality profile you prefer. The Simply Wall St Screener is a fast way to build that wider watchlist without starting from a blank page.
- If you want potential mispricing with stronger fundamentals, scan through 29 high quality undervalued stocks and see which companies fit your return and quality filters.
- For investors who care most about steady income, work through 8 dividend fortresses and identify which payers line up with your yield and payout expectations.
- When capital preservation comes first, begin with a 31 resilient stocks with low risk scores and compare those resilient profiles with Ross Stores on your own terms.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com