
Grand Canyon Education (LOPE), What Is Behind The Fresh Attention?
Grand Canyon Education (LOPE) has put a new financing tool in place, securing a five year, US$100.0 million senior secured revolving credit facility that can support share repurchases and other corporate uses.
Recent trading paints a mixed picture for Grand Canyon Education. The share price gained 7.25% over the past 90 days and 5.69% over the last month, yet the year to date share price return is down 3.38% and the 1 year total shareholder return has declined 23.07%. This suggests that recent momentum is improving from a weaker longer term patch as investors weigh the new credit facility and buyback capacity against past performance.
Compare Grand Canyon Education's new credit firepower with peers by scanning 29 high quality undervalued stocks that also pair disciplined balance sheets with scope for buybacks and reinvestment.
Grand Canyon Education now trades about 21% below the average analyst target and at a larger implied discount to intrinsic value. After the recent rally and new credit line, is the market's caution still warranted?
Most Popular Narrative: 18% Undervalued
On Simply Wall St's most followed narrative, Grand Canyon Education screens as undervalued, with a fair value estimate of $195 against a last close of $159.80. That gap rests on the idea that the service provider model can keep earnings resilient even while the share price has lagged over the past year.
Direct partnerships with over 5,500 employers and the rollout of 20+ new career-aligned programs annually position GCE to capture sustained demand for workforce reskilling and upskilling, supporting ongoing student pipeline growth and forming the basis for durable revenue and operating earnings expansion.
See why 3 investors see Grand Canyon Education as 18% undervalued.
Result: Fair Value of $195 (UNDERVALUED)
Still, Grand Canyon Education faces pressure from declining revenue per student, along with ongoing legal and regulatory risks that could challenge the current undervalued narrative.
Find out about the key risks to this Grand Canyon Education narrative.
Another View: Grand Canyon Education Through The P/E Lens
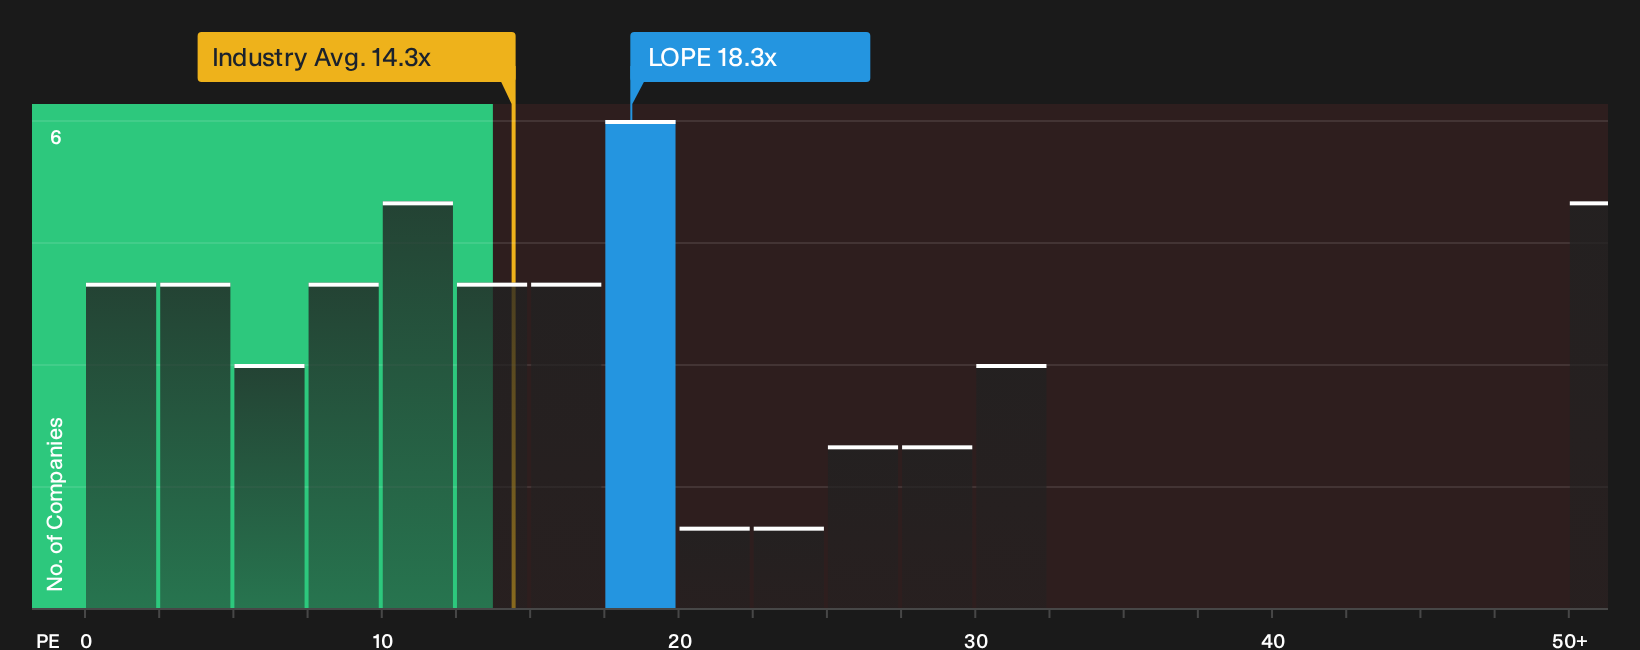
There is a catch. Grand Canyon Education trades on a P/E of 18.3x, which is higher than both the US Consumer Services industry at 14.3x and the peer average of 13.8x, and in line with its own fair ratio of 18.3x. That leaves less obvious multiple based upside and raises the question of whether the discount case is already partly priced in.
To see what the numbers imply for this pricing gap, and how much room there might be for re rating or de rating, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Grand Canyon Education may feel mixed right now, which is exactly when it pays to study the details yourself and move early on your own thesis. To see the factors investors are optimistic about, take a focused look at the 3 key rewards.
Looking for more investment ideas beyond Grand Canyon Education?
If Grand Canyon Education has you thinking harder about valuation and risk, make the next move and line up a few fresh ideas using targeted screeners.
Scan for potential value opportunities that pair quality fundamentals with a pricing gap the market may be overlooking by running the 29 high quality undervalued stocks.
Target stability and capital protection first, then layer in upside potential by filtering companies through the 31 resilient stocks with low risk scores.
Hunt for underfollowed opportunities that combine strong financials with thinner analyst coverage by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com