
Senior Housing NOI Growth Could Be A Big Test For Ventas Stock
- Ventas recently reported double digit net operating income growth in its senior housing portfolio, supported by a diversified base of nearly 1,400 healthcare properties across North America and the United Kingdom.
- The sharp net operating income uplift in senior housing highlights how this segment is becoming an increasingly important earnings engine within Ventas’ broader healthcare real estate platform.
- We will now look at how Ventas’ double digit senior housing net operating income growth interacts with the existing investment narrative.
Scan beyond Ventas and compare its senior housing momentum with a curated list of solid balance sheet and fundamentals (25 results) that could complement a healthcare-heavy real estate portfolio.
Ventas Investment Narrative Recap
To own Ventas, you need to be comfortable with a simple idea. Senior housing remains the main engine. The rest of the healthcare portfolio provides balance while that engine is pushed harder. The recent double digit senior housing NOI growth supports that thesis and keeps the key short term catalyst squarely on continued occupancy and pricing resilience in those communities.
The flip side is risk concentration. As more earnings come from operated senior housing, exposure to operator execution, local market conditions and equity funded expansion rises. If occupancy or rate growth in key markets softens, or if acquisition yields compress, the impact on same store NOI and normalized FFO per share could be meaningful.
One context point that matters around this news is Ventas’ use of equity to fund senior housing expansion. Management has raised about US$4.2b of equity by Q2 2026 and deployed over US$8b into senior communities since early 2024, while keeping net debt to EBITDA at 4.7x. The recent NOI surge effectively becomes a live test of whether those large outlays are translating into the stronger earnings base analysts expected.
That equity heavy approach brings both opportunity and pressure. If the acquired and converted senior housing assets keep producing strong NOI, the enlarged portfolio can support revenue growth, offset interest costs and help justify the higher share count. If future deals earn lower yields because competition pushes pricing up, or if current properties see slower NOI, the dilution risk to FFO per share and the concern around interest coverage remain front of mind for shareholders.
Ventas' current analyst narrative points to US$8.9b in revenue and US$677.2m in earnings by 2029, based on 11.6% yearly top line growth and an earnings increase of about US$414.5m from the US$262.7m reported today.
Uncover why Ventas' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
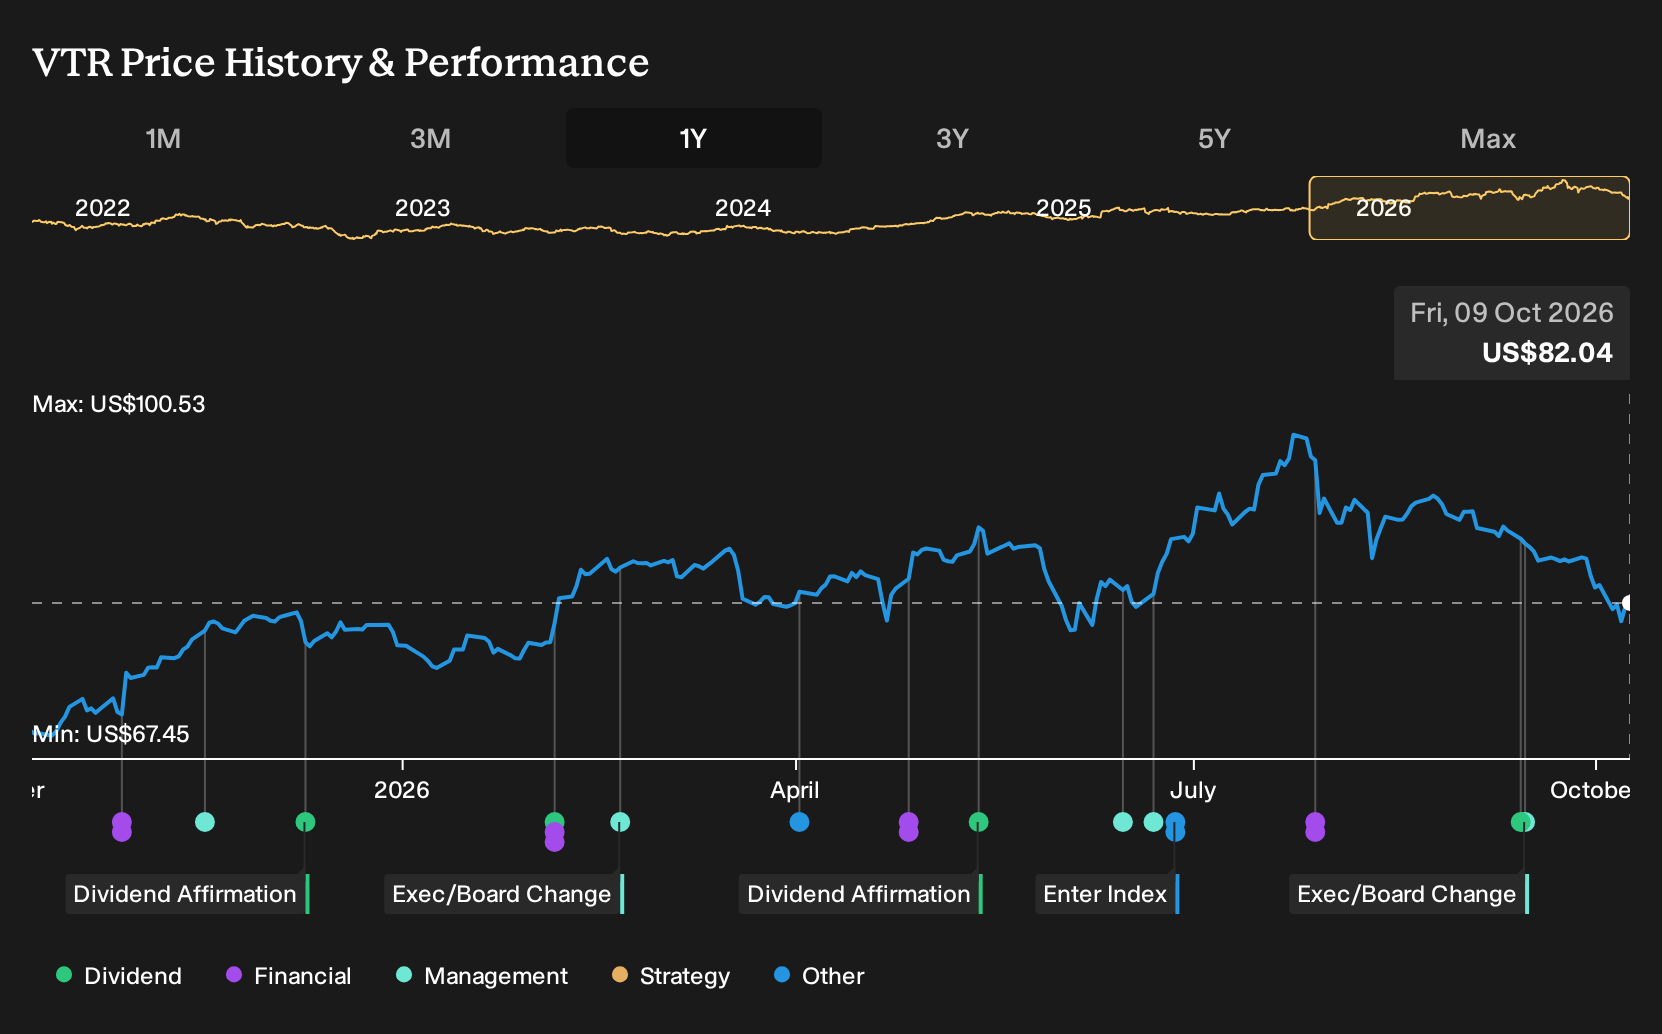
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$101.9 and US$118.6 per share, which is a tight band but still shows how opinions on Ventas can diverge. Set that against risks around equity funded senior housing deals and potential yield compression, then weigh how those pressures could shape future earnings resilience.
Explore another Ventas fair value estimate, including one that suggests as much as 45% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ventas research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ventas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ventas' overall financial health at a glance.
Looking for more Ventas-sized investment ideas?
Once you have a view on Ventas, it can help to line it up against other businesses with different income profiles and risk levels using the Simply Wall St Screener.
- If you want a wider margin of safety, scan through 29 high quality undervalued stocks that may offer stronger fundamentals relative to their current share prices.
- If your priority is capital preservation, compare Ventas with 31 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- If you are hunting for fresh opportunities away from the usual tickers, comb through 20 high quality undiscovered gems that combine solid balance sheets with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com