
How Fed Rate Expectations Will Impact ING Stock Investors
- ING Groep has drawn fresh attention after its own foreign exchange specialists highlighted firmer US Federal Reserve tightening expectations and a stronger dollar, while market observers reassess the bank’s earnings power and capital distribution in relation to its current P/E level and modest undervaluation signals.
- The interesting angle is how ING Groep’s sensitivity to rate moves and currency swings intersects with questions about sustainable net interest income and fee growth, which relates directly to the resilience of its business model rather than only short term market sentiment.
- We will now look at how ING Groep’s investment narrative could be shaped by its US rate and dollar focused FX commentary.
ING Groep Investment Narrative Recap
To own ING Groep, you need to believe the bank can keep turning its large digital retail and wholesale footprint into steady fee income and reasonably stable net interest income, even as rates and currencies move around. The near term swing factor is how quickly US and European rate expectations shift, because that directly feeds into deposit pricing, loan yields, and currency translated earnings.
The biggest current risk sits in margin pressure and FX volatility. Faster rate cuts or a weaker euro against a firm US dollar could squeeze commercial net interest income, particularly if wholesale loan demand in places like Germany stays muted. In that scenario, ING Groep would lean harder on fee growth, cost control, and its digital cost base to protect returns.
The most relevant recent input is ING’s own FX team flagging upside risks to US core inflation and a firm dollar index above 102. That view supports expectations of tighter Fed policy for longer, which matters for ING Groep because US rates influence global funding costs and cross border client activity that run through its wholesale franchise.
For you as an investor, the link back to catalysts is clear. Sustained dollar strength and slower euro recovery keep FX swings front and centre for ING Groep’s commercial net interest income, while also shaping client demand for hedging, trade finance, and treasury services. Execution on digitalisation, fee expansion, and cost efficiencies then determines whether those macro cross currents translate into earnings resilience or margin drag.
ING Groep Earnings Framework Behind The FX Story
ING Groep's narrative projects €27.9 billion revenue and €8.4 billion earnings by 2029. This lines up with analysts assuming 3.4% yearly revenue growth and an earnings decrease of €0.3 billion from €8.7 billion today.
Uncover how ING Groep's fair value indicates an 11% potential upside to its current price before the market closes the gap.
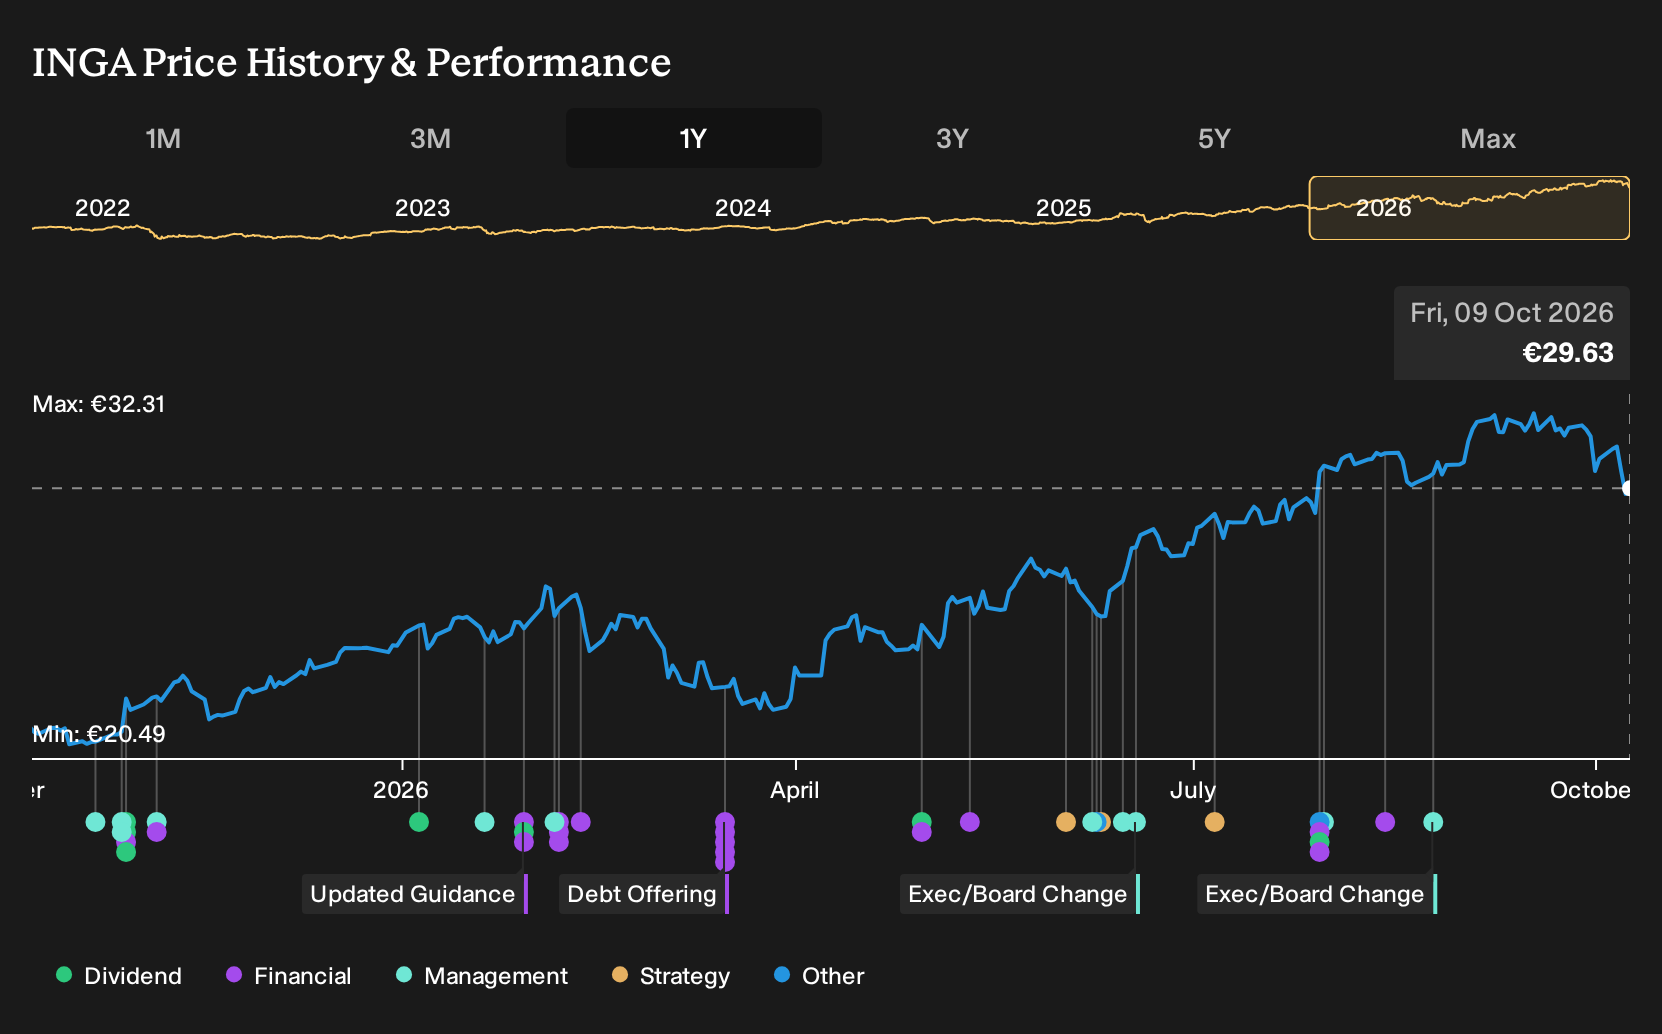
Exploring Other Perspectives
One bullish twist on ING Groep focuses less on rate risk and more on what rapid digital adoption could mean for earnings. The most optimistic analysts were pencilling in €30.4b revenue and €10.1b earnings by 2029 before this FX news. You can treat those upbeat AI and fee income assumptions as one possible storyline, and then weigh how fresh dollar and Fed commentary might nudge that script in a different direction.
Explore 3 other ING Groep fair value estimates, including one that suggests as much as 101% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ING Groep research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ING Groep. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ING Groep's overall financial health at a glance.
Looking for more ING Groep style investment ideas?
If the ING Groep story has sharpened your thinking on interest rate exposure, balance sheet strength, and valuation, it can be useful to compare that against other potential opportunities using the Simply Wall St Screener.
- For investors who want income to feel more predictable, review companies in the income-focused 221 dividend fortresses that offer yields above 5% with an emphasis on durability.
- If capital preservation sits high on your checklist, scan a curated 225 resilient stocks with low risk scores built around resilient balance sheets and lower risk profiles.
- When you are hunting for future potential rather than household tickers, check out a 618 high quality undiscovered gems that couples solid fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com