
3 Japanese Growth Stocks To Own In October 2026
Global banks now point to stronger earnings as a key support for equities, even with higher interest rates and volatile headlines. That puts fast growing Japanese companies with relatively healthy balance sheets in the spotlight for investors who do not want to sit on the sidelines if profit stories keep drawing capital toward shares. This article highlights three such stocks from our growth oriented Japan screener.
The three stocks below are just a small sample from this theme. The full screen surfaced 77 more companies with similarly compelling growth and balance sheet stories that are not covered here.
If you want to go beyond this shortlist, head straight into the Healthy high growth potential screener to filter, analyze, and identify the highest conviction ideas that fit your own return and risk preferences.
SHIFT (TSE:3697)
Overview: SHIFT is a Tokyo based provider of software quality assurance, testing tools like CAT, and consulting, alongside smaller social support services.
Operations: SHIFT generates most of its ¥150,255 million revenue in Japan, led by ¥96,956 million from software testing and ¥46,302 million from software development services.
Market Cap: ¥239.5 billion
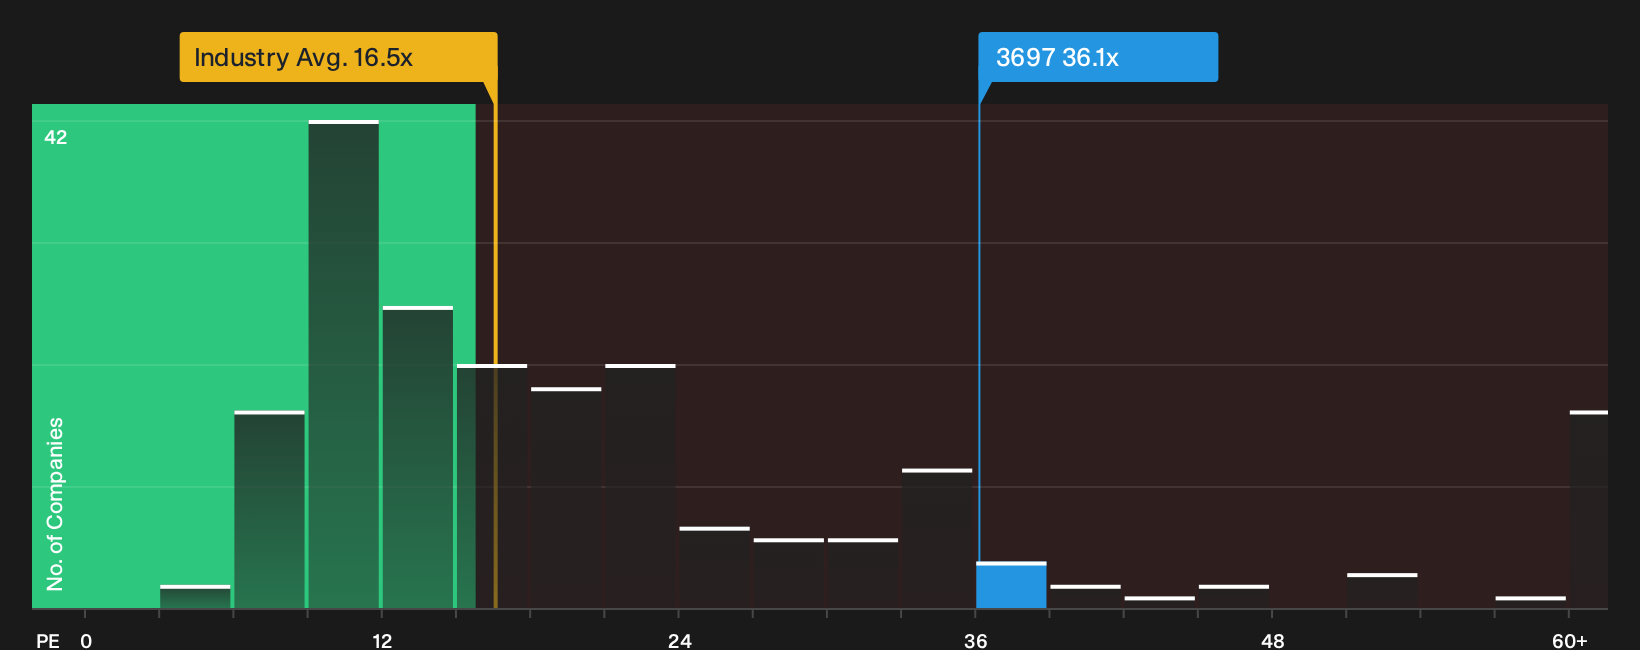
SHIFT fits the Healthy high growth potential theme through its software testing platforms and consulting, where analysts have characterized earnings growth expectations as being supported by scalable SaaS style services. The stock trades on a P/E near 36x and carries margin pressure, so potential returns depend on how profitability pressure is addressed.
If you want to see how that pressure and pricing power stack up in detail, review the 2 key rewards and 2 important warning signs (1 is major!) to see what could really affect returns.
Sansan (TSE:4443)
Overview: Sansan provides cloud-based tools that turn business cards and related meeting data into shared contact systems to help companies grow sales efficiently.
Market Cap: ¥278.3 billion
Sansan fits within the Healthy high growth potential theme because its contact and sales productivity platforms directly support revenue expansion. Recent earnings and margin gains indicate that this growth is not coming at the expense of financial health. However, future returns depend on how one key profitability lever develops from here.
That hinge point is profitability, so pull up the analysis report for Sansan to see whether Sansan’s growth engine is reinforcing margins or quietly limiting potential upside

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor probe cards, test equipment, and related inspection tools that help chipmakers measure and screen advanced devices.
Operations: Micronics Japan generates ¥84,868 million from its probe card business and ¥1,391 million from TE equipment, with revenue mainly from South Korea and Taiwan.
Market Cap: ¥671.9 billion
Micronics Japan is aligned with the Healthy high growth potential theme, with earnings forecast to rise about 24.9% a year and recent profit expanding faster than sales as probe card demand linked to memory and generative AI increases. Future returns still depend, however, on how results evolve if a single key assumption about that demand curve is challenged.
If that demand assumption is on your mind, review the 2 key rewards and 1 important major warning sign to see where Micronics Japan’s AI driven test exposure could surprise you.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, the quiet breakout stories are already flying. Scan these under the radar candidates while it matters and consider them before they become widely followed.
- Target reliable income streams by reviewing the 28 dividend fortresses that have been filtered for yield strength and balance sheet resilience before everyone starts chasing payouts.
- Spot early movers in digital assets by using the 20 cryptocurrency and blockchain stocks that focuses on businesses tied to real blockchain adoption rather than hype that may fade.
- Track the next wave of automation by reviewing the curated 91 robotics and automation stocks that could benefit as factories, warehouses, and devices keep upgrading their capabilities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com