
Toast (TOST) Expands Toast IQ While Fair Value Still Looks Higher
Toast (TOST) has just widened its Toast IQ product suite with new AI tools for labor management, marketing automation, and multilingual support. This gives investors fresh context for how the platform is evolving.
Recent trading suggests interest in Toast is rebuilding. The 1-day share price return of 2.55% and 7-day share price gain of 4.23% come after a 30-day share price decline of 2.52%. Meanwhile, the 1-year total shareholder return is down 12.64%, yet the 3-year total shareholder return is up 74.72%, which points to stronger longer term momentum than the past year implies.
Scan for other payment and AI-enabled platforms showing similar momentum and product breadth, and explore a curated set of 39 profitable AI stocks that aren't just burning cash aligned with the type of tools Toast is rolling out.
Toast now appears to be a more capable business than its recent share price path suggests. The real test is whether that AI heavy platform is still available at a sensible valuation today.
Most Popular Narrative: 33% Undervalued
The most followed narrative on Toast pegs fair value at $46.44 per share, compared with the recent $31.31 close. This frames the current AI heavy expansion against a valuation that still looks discounted according to that view.
A cloud-based vertical ecosystem built specifically for the restaurant and hospitality sector. Unifies POS hardware/software, supply chain management, integrated payments, marketing, and kitchen management. Has successfully pivoted from heavy growth investments toward accelerated net profitability.
See why 3 investors see Toast as 33% undervalued.
Result: Fair Value of $46.44 (UNDERVALUED)
Still, the Toast narrative can break if rich P/E and P/B multiples compress, or if restaurant clients push back on pricing for its AI heavy toolkit.
Find out about the key risks to this Toast narrative.
Another View On Toast Valuation
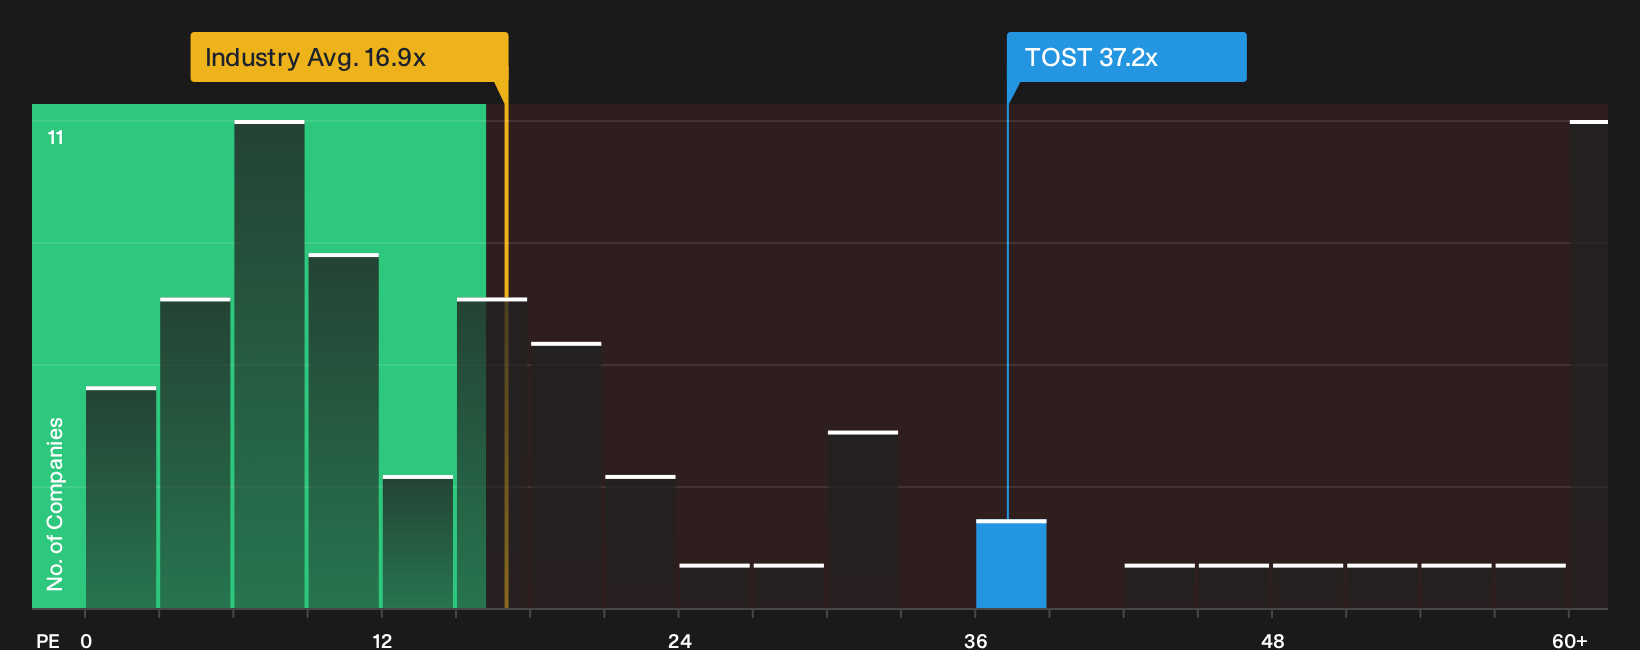
That $46.44 fair value comes from a narrative style framework, but the market is also looking at Toast through earnings multiples. The current P/E is 37.2x, which is more than double the US Diversified Financial industry at 16.9x and above the fair ratio of 19.3x. That kind of gap can mean investors are paying up for quality growth, or it can leave less room for error if sentiment cools.
To see how that earnings based view could evolve as expectations shift, and how it compares with other approaches, See what the numbers say about this price — find out in our valuation breakdown..
Here is how Toast stacks up against peers on this metric visually, which can help you judge how stretched or justified that premium looks at a glance
Next Steps
If this Toast story feels balanced between opportunity and risk, treat that as a prompt to move fast and stress test the numbers yourself. To see which potential upsides analysts are watching most closely, review the 4 key rewards.
Looking for more investment ideas beyond Toast?
Toast gives you one angle on AI and payments, but a broader watchlist can sharpen decisions and spotlight opportunities you might otherwise miss.
- Target resilient balance sheets and steadier cash profiles by scanning a list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispriced opportunities by reviewing a focused group of 20 high quality undiscovered gems.
- Stack your watchlist with stability first and foremost by filtering for 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com