
Is Ferrovial (BME:FER) Cheap After Its I 24 Concession Win?
Ferrovial’s I-24 milestone and why it matters for investors
Ferrovial (BME:FER) has moved to commercial close on the I-24 Southeast Choice Lanes project with Tennessee’s Department of Transportation, securing a 50-year concession that covers financing, construction, operation and maintenance.
The I-24 announcement comes after a weaker run for Ferrovial’s shares, with the 30-day share price return down 7.58% and the 90-day move down 20.36% to €44.6. At the same time, the 5-year total shareholder return of 90.35% still points to a strong longer-term record, which suggests recent momentum has faded even as the market has historically rewarded the business over time.
Scan infrastructure players facing similar crosswinds to Ferrovial using our hand picked list of solid balance sheet and fundamentals (202 results) as a starting universe for your watchlist.
Bulls see I-24 as proof Ferrovial can keep turning large concessions into long-term cash flows. Bears point to the recent share price slide and question whether the current valuation still stacks up.
Most Popular Narrative: 26% Undervalued
Ferrovial’s most followed narrative puts fair value at €60.30, above the last close of €44.60. This frames I-24 as a valuation swing factor rather than a side project.
The market may be attributing too much value to Ferrovial's assets based on outsized recent increases in toll rates and revenue per transaction, which are partly a function of dynamic pricing and aggressive promotions, both of which may not be sustainable if macroeconomic or regulatory environments change. This could lead to slower future revenue growth or even a reversal if price elasticity is higher than assumed, compressing top-line growth.
See why 8 investors see Ferrovial as 26% undervalued.
Result: Fair Value of €60.30 (UNDERVALUED)
Still, this narrative can break if North American toll roads keep compounding strong results or if Ferrovial’s record €17.3b order book delivers smoother earnings than expected.
Find out about the key risks to this Ferrovial narrative.
Another view on Ferrovial’s valuation
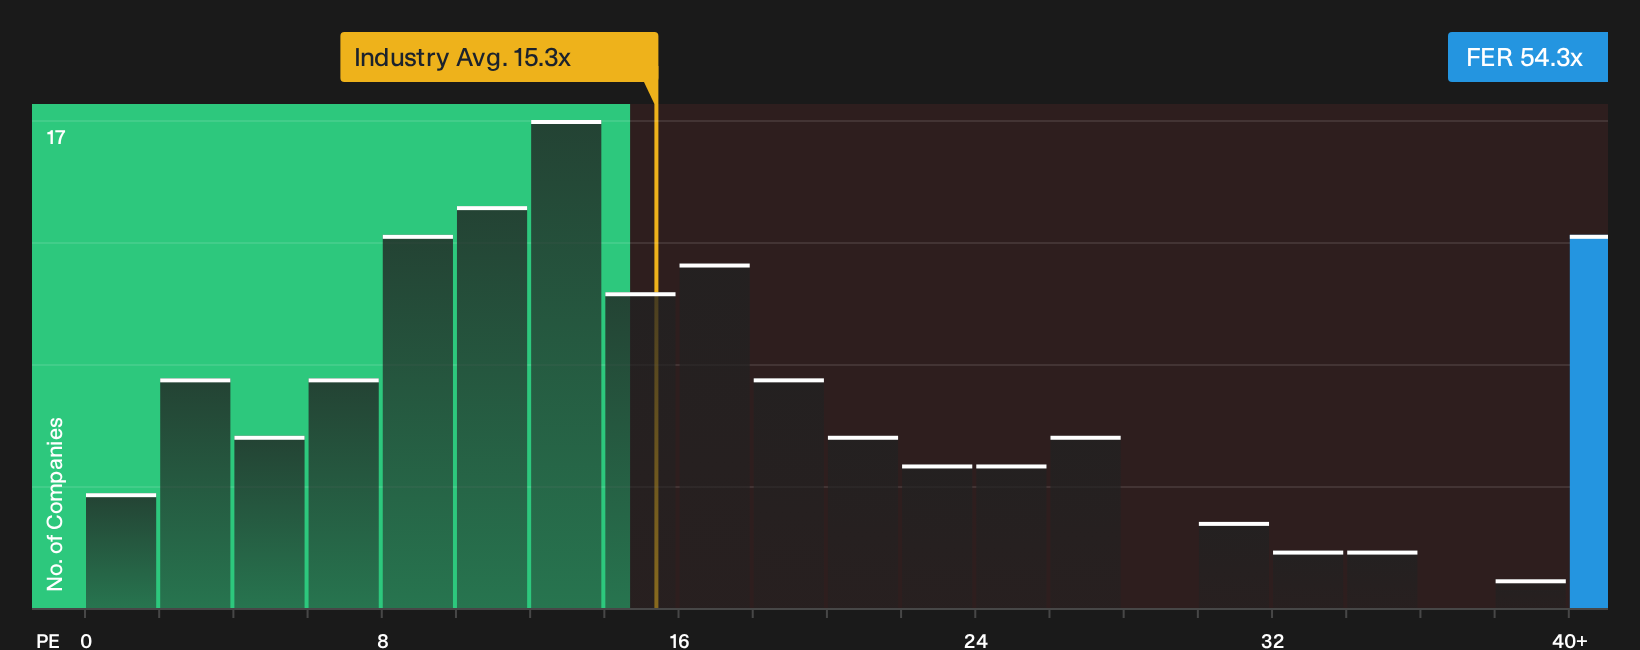
Analysts using earnings multiples see Ferrovial on a steep P/E of 54.3x, compared with 23.4x for peers, 15.3x for the wider European construction group and a fair ratio of 27.6x. That is a big premium. Is it compensation for quality, or just extra valuation risk?
Our valuation tools unpack this gap in more detail so you can judge whether that higher P/E feels justified or stretched, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Ferrovial story today should push you to stress test the numbers yourself and decide how comfortable you feel with both the upside and the downside. Start with the 2 key rewards and 3 important warning signs.
Looking for more Ferrovial-sized investment ideas?
If Ferrovial has you thinking harder about pricing power, contracts and durability, broaden your watchlist now so you are not relying on a single story.
- Target resilient compounding by scanning a curated set of 177 high quality undervalued stocks that pair quality fundamentals with more modest expectations baked into their prices.
- Lock in potential income streams by reviewing 220 dividend fortresses that combine higher yields with balance sheets built to support regular payouts.
- Reduce portfolio stress by filtering for 224 resilient stocks with low risk scores that show stronger financial health scores and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com