
Zymeworks (ZYME) Sets 2026 Revenue Guidance, Is The Stock Below Fair Value?
Zymeworks (ZYME) drew fresh attention after appointing Stuart Knight as Executive Vice President and Chief Information Officer and issuing 2026 revenue guidance of US$278 million to US$292 million, giving investors new reference points.
Recent trading shows a mixed picture. Zymeworks’ share price has edged higher in the last quarter with a 90 day share price return of 4.58%, yet the year to date move is slightly down. At the same time, a 1 year total shareholder return of 42.41% and a very large 3 year total shareholder return above 7x suggest that momentum has built over time as investors reassess both growth potential and risk around the new guidance and leadership changes.
Compare how this kind of AI driven biotech story stacks up against a hand picked group of 33 healthcare AI stocks that are moving on similar data and revenue catalysts.
Zymeworks now has fresh revenue targets and a long runway of AI enabled drug programs. The harder question is whether a US$1.8b valuation and recent share price gains already reflect that strength.
Most Popular Narrative: 38% Undervalued
The most followed narrative puts Zymeworks fair value at $41.75, well above the last close at $25.79, and ties that gap directly to future milestone and royalty flows that analysts have built into their models.
Zymeworks' strategic partnership and out-licensing approach with large pharmaceutical companies (e.g., Jazz, BeiGene, BMS, J&J) is generating significant near-term and long-term non-dilutive cash inflows, diversifying revenue streams and reducing the R&D burn rate, thus supporting better EBITDA margins and enhanced cash flow stability as the partnered assets advance.
See why 8 investors see Zymeworks as 38% undervalued.
Result in bold: Result: Fair Value of $41.75 (UNDERVALUED)
Still, this upside story for Zymeworks can unravel quickly if key regulatory decisions slip or if partnered programs underdeliver on expected milestone and royalty cash flows.
Find out about the key risks to this Zymeworks narrative.
Another View: What Multiples Say About Zymeworks
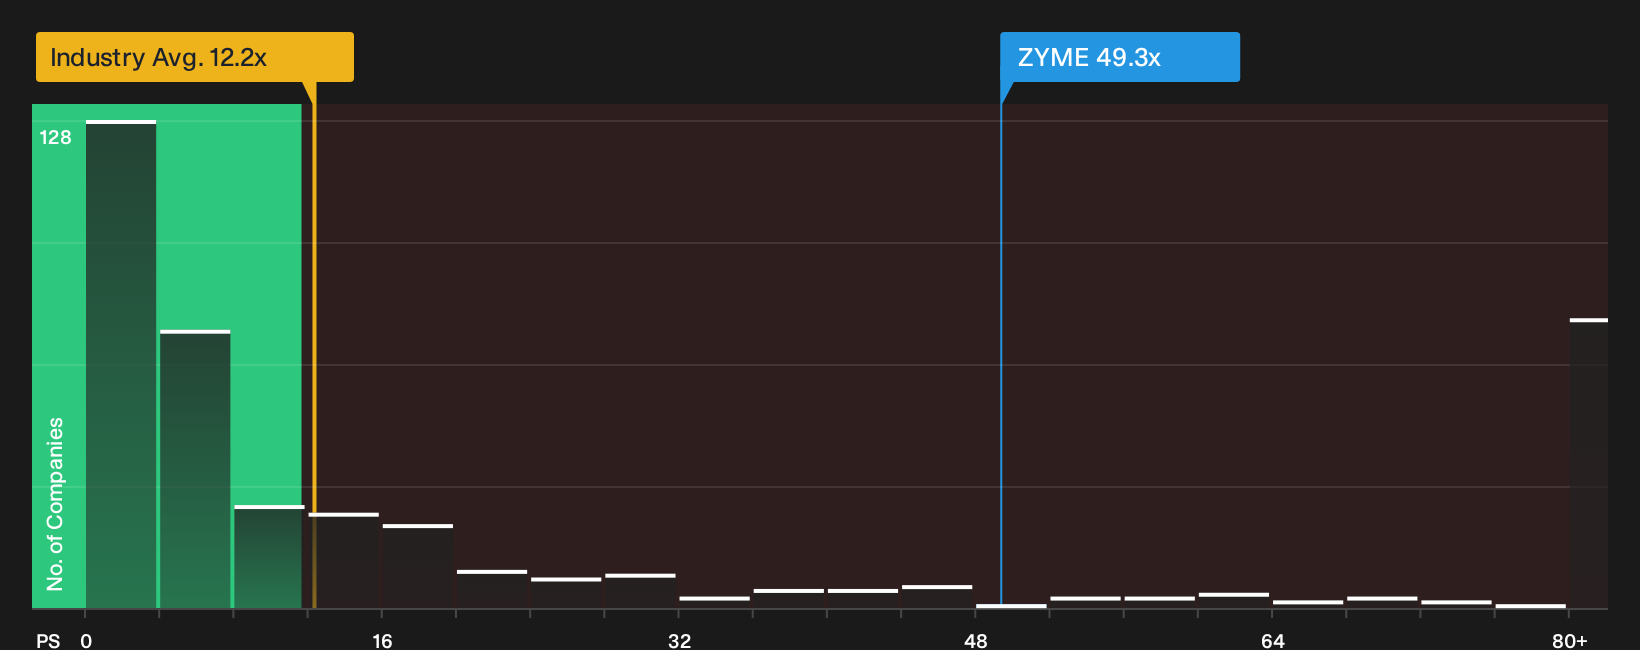
There is a very different picture when you look at Zymeworks through its P/S ratio. The stock trades at 49.3x sales compared with 12.2x for the US biotech group and 11.4x for peers, while the fair ratio is 0.2x. That kind of gap points to real valuation risk if expectations change.
To see how that high sales multiple fits with the rest of the numbers, have a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Seen enough optimism around Zymeworks today. If you want to move fast and stress test that upbeat view against the data, start with the 2 key rewards.
Looking for more investment ideas beyond Zymeworks?
If you stop with Zymeworks, you miss the wider opportunity set. Put a few more quality filters to work and give yourself stronger options.
- Target fresh upside by scanning 20 high quality undiscovered gems that combine solid fundamentals with stories many investors have not yet priced in.
- Protect your downside first and run through 31 resilient stocks with low risk scores that screen for resilience using cleaner balance sheets and more stable business profiles.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (25 results) so your next idea rests on financial footing that can handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com