
UK's Top 3 Stocks Estimated Below Fair Value In October 2026
The United Kingdom's stock market has recently faced challenges, as evidenced by the FTSE 100 index closing lower due to weak trade data from China, impacting companies closely tied to its economic performance. In light of these conditions, identifying stocks that are currently undervalued can offer potential opportunities for investors seeking value amidst broader market uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.39 | £2.48 | 43.9% |
| Smiths News (LSE:SNWS) | £0.744 | £1.45 | 48.7% |
| Smith & Nephew (LSE:SN.) | £10.205 | £17.37 | 41.3% |
| Shell (LSE:SHEL) | £37.935 | £68.48 | 44.6% |
| Property Franchise Group (AIM:TPFG) | £4.12 | £7.34 | 43.9% |
| Premier Foods (LSE:PFD) | £1.94 | £3.13 | 37.9% |
| LSL Property Services (LSE:LSL) | £2.64 | £4.56 | 42.2% |
| Hollywood Bowl Group (LSE:BOWL) | £2.515 | £5.00 | 49.7% |
| Gamma Communications (LSE:GAMA) | £10.94 | £20.18 | 45.8% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.725 | £1.35 | 46.4% |
Let's dive into some prime choices out of the screener.
Currys (LSE:CURY)
Overview: Currys plc is an omnichannel retailer of technology products and services across the UK, Ireland, and several Nordic countries, with a market cap of £1.51 billion.
Operations: The company generates revenue from two main segments: £3.82 billion from the Nordics and £5.50 billion from the UK & Ireland.
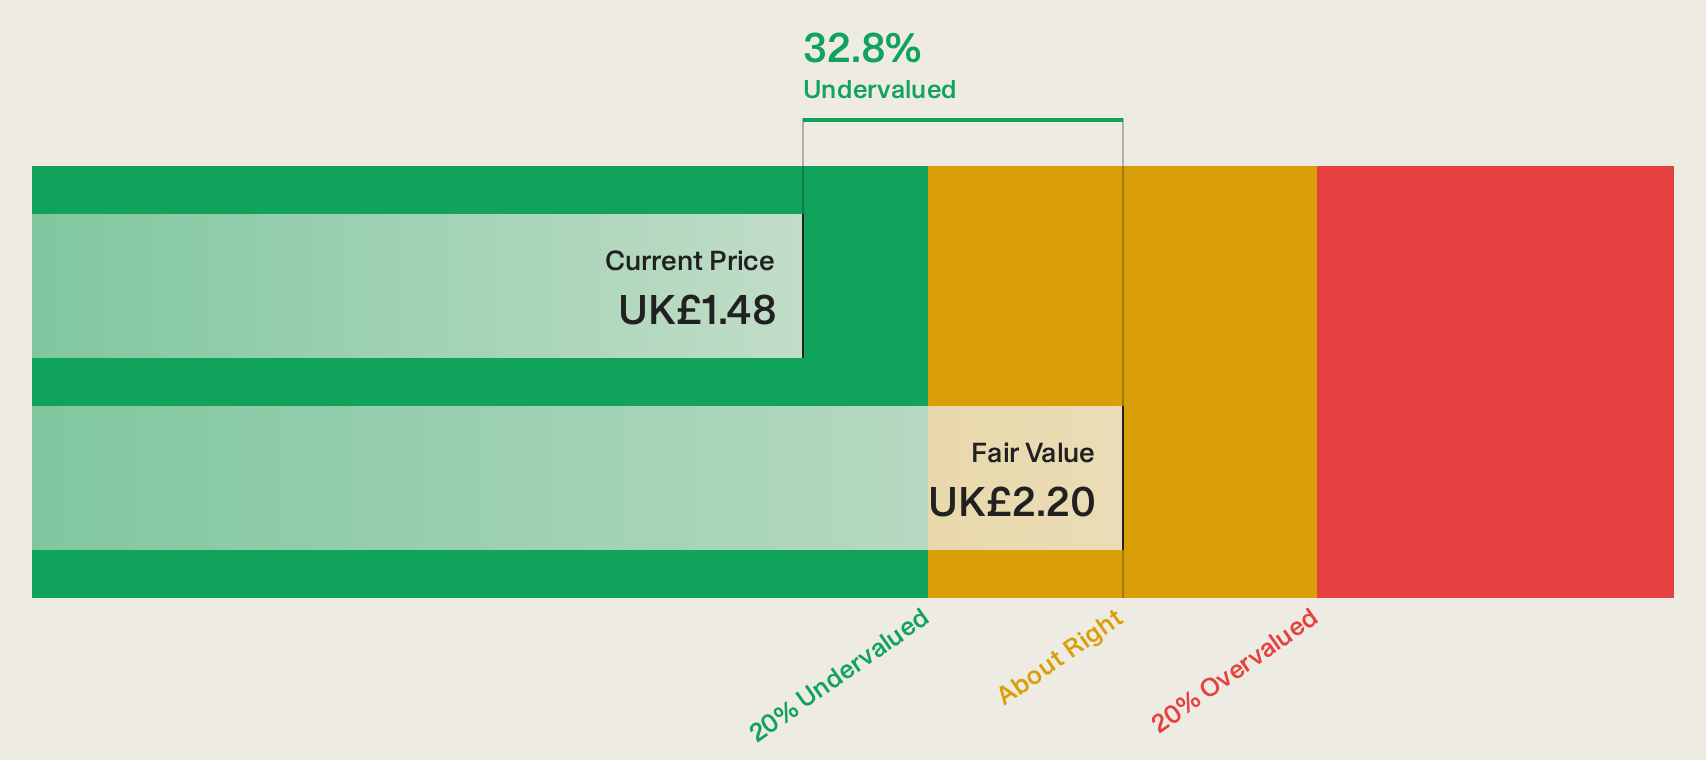
Estimated Discount To Fair Value: 33.3%
Currys is trading at £1.47, significantly below its estimated future cash flow value of £2.2, indicating it is undervalued based on discounted cash flow analysis. Despite a slower forecasted earnings growth rate of 0.8% annually compared to the UK market's 11.1%, analysts agree on a potential price rise of 26%. Recent changes include the appointment of Fredrik Tonnesen as director and a final dividend declaration of 2.25 pence per share.
- The growth report we've compiled suggests that Currys' future prospects could be on the up.
- Click here to discover the nuances of Currys with our detailed financial health report.
Morgan Sindall Group (LSE:MGNS)
Overview: Morgan Sindall Group plc is a UK-based construction and regeneration company with a market cap of £1.91 billion.
Operations: The company's revenue segments consist of Fit Out (£1.94 billion), Infrastructure (£920.60 million), Partnership Housing (£845.30 million), and Mixed Use Partnerships (£50.90 million).
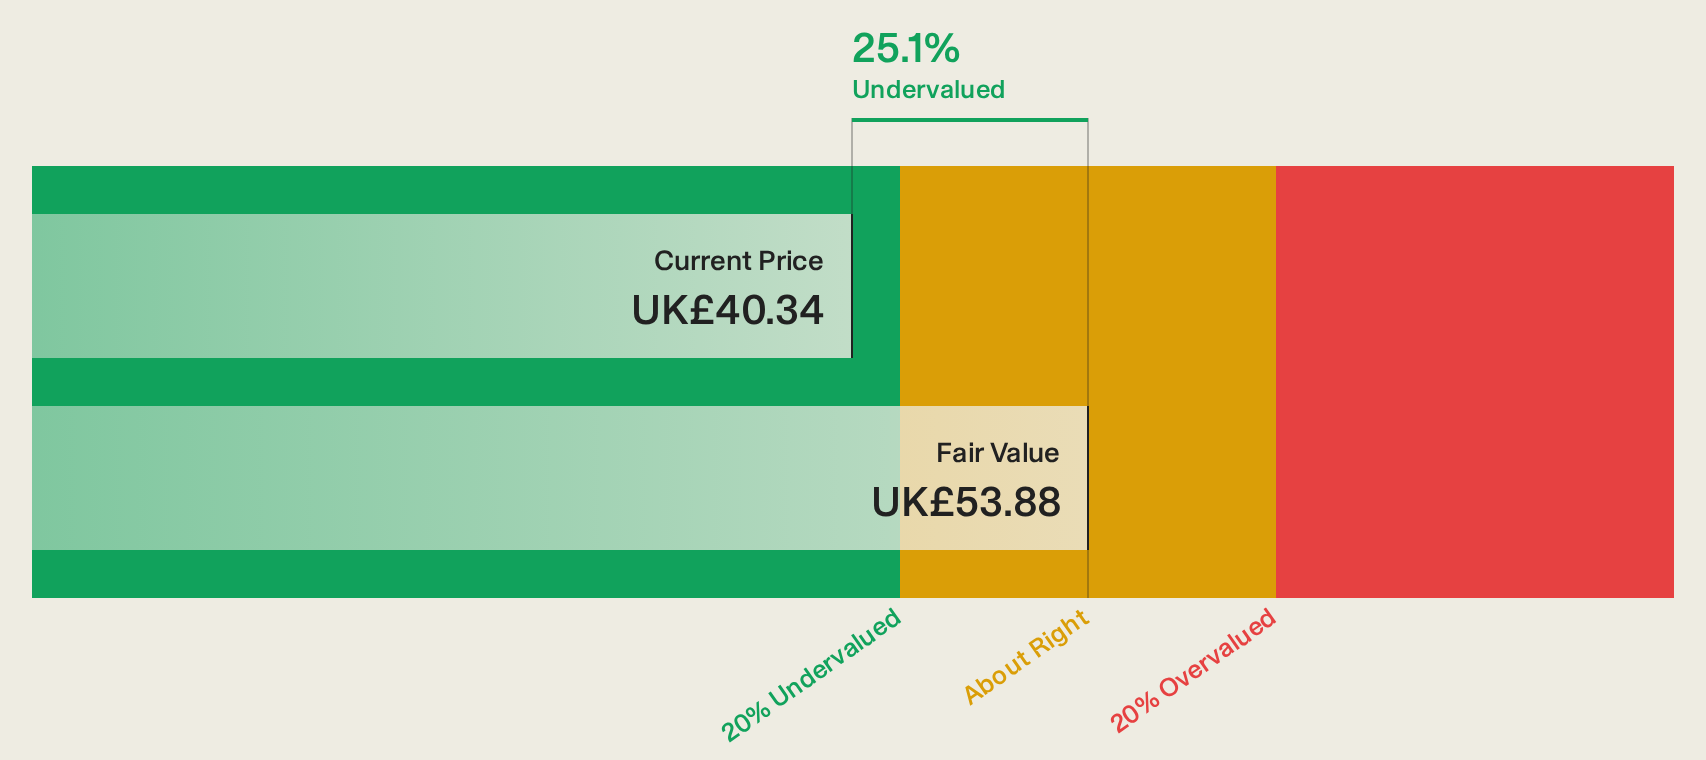
Estimated Discount To Fair Value: 23.2%
Morgan Sindall Group is trading at £40.86, below its estimated future cash flow value of £53.19, highlighting its undervaluation on a discounted cash flow basis. Although earnings are expected to grow slower than the UK market at 1.4% annually, analysts anticipate a potential price increase of 37.6%. Recent results showed sales rising to £2.56 billion and net income improving to £87.1 million for the first half of 2026, alongside a proposed interim dividend increase to 55 pence per share.
- Our earnings growth report unveils the potential for significant increases in Morgan Sindall Group's future results.
- Click here and access our complete balance sheet health report to understand the dynamics of Morgan Sindall Group.
PayPoint (LSE:PAY)
Overview: PayPoint plc provides payments and banking, shopping, and e-commerce services in the United Kingdom and New Zealand, with a market cap of £391.19 million.
Operations: The company's revenue is derived from two main segments: Love2shop, contributing £158.23 million, and Pay Point, generating £178.78 million.
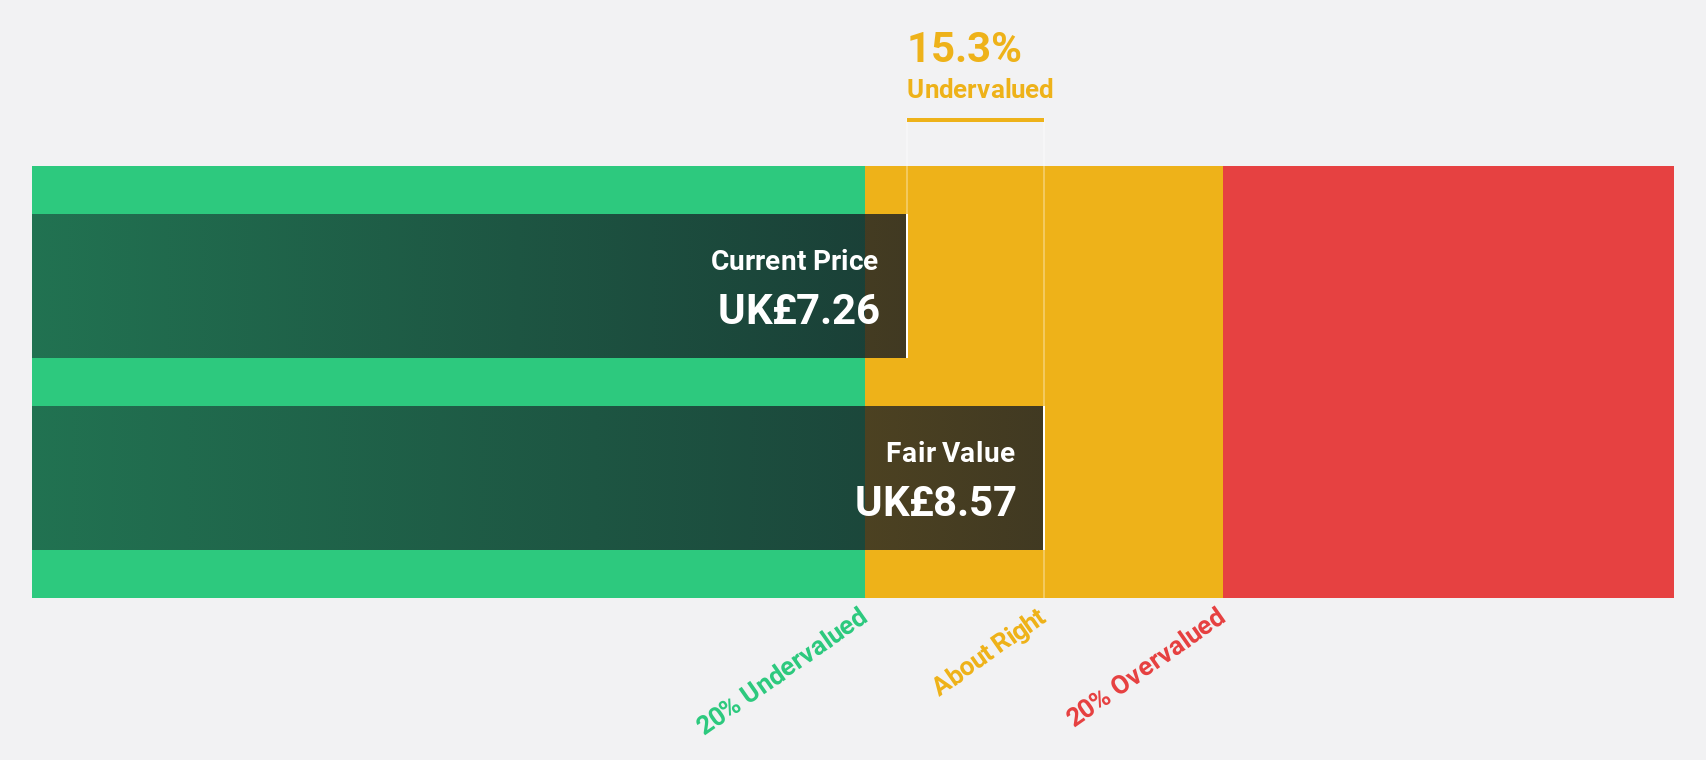
Estimated Discount To Fair Value: 37.2%
PayPoint is trading at £6.64, significantly below its estimated future cash flow value of £10.56, suggesting undervaluation. The company's earnings grew by 105% over the past year and are forecast to grow 10.55% annually, though slower than the UK market average of 11.1%. Despite a high future return on equity forecast of 57.1%, revenue is expected to decline by 6.9% per year over the next three years, and dividend stability remains uncertain following recent board changes.
- The analysis detailed in our PayPoint growth report hints at robust future financial performance.
- Delve into the full analysis health report here for a deeper understanding of PayPoint.
Taking Advantage
- Dive into all 27 of the Undervalued UK Stocks Based On Cash Flows we have identified here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com