
Antero Midstream (AM) Stock May Be Overvalued After A 161% Run
Antero Midstream has delivered a powerful share price run in recent years, which naturally puts the spotlight on whether the current valuation is still grounded in its earnings. With the stock now well above levels of just a few years ago, the question for investors is how much of the underlying profit story is already reflected in today’s price.
- Over the past 5 years the stock has returned about 161%, which raises the stakes on whether the company’s earnings profile can support that kind of rerating.
- The business relies heavily on fee-based midstream services, which can support more predictable earnings and may shape how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Antero Midstream worth weighing. See what analysts think Antero Midstream's shares could be worth.
The stock’s next move may depend on whether Antero Midstream’s current share price is justified by the level and quality of its earnings.
If you want other starting points for research beyond Antero Midstream, a focused screen of 29 high quality undervalued stocks can help you compare earnings power and pricing across a wider watchlist.
Does Antero Midstream Look Pricey on Earnings?
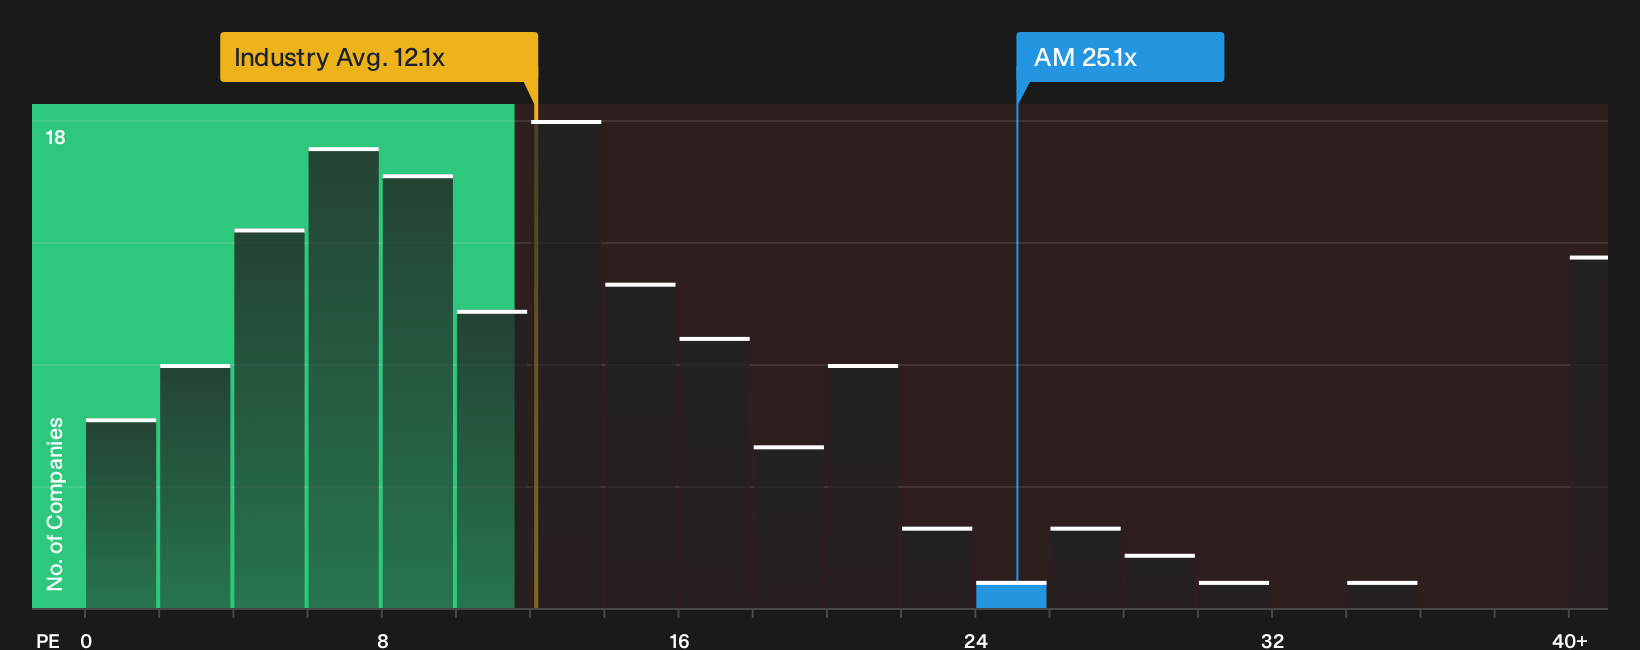
The P/E ratio fits Antero Midstream because earnings are a central part of how investors usually assess fee based infrastructure businesses. Right now the stock trades on about 25.1x earnings, which is higher than the Oil and Gas sector average of roughly 12.1x and also above the peer group near 17.4x. That is a sizeable premium for a midstream operator.
A tailored fair value framework that factors in Antero Midstream’s growth profile, profitability, size and risk suggests a lower P/E would be more in line with those fundamentals. As a result, the current 25.1x points to an overvalued setup on this metric. For anyone weighing an entry or adding to a position, a key consideration is whether the quality and durability of future profits justifies paying materially more per dollar of earnings than both the sector and closer peers are priced at today. Explore the numbers behind Antero Midstream's P/E valuation.
The Antero Midstream Narrative: What Would Justify Today's Price?
Narratives for Antero Midstream pick up where this valuation puzzle leaves off. They outline which paths for future growth, margins and earnings would need to occur for the stock to be worth much more or much less than today’s share price. Each one focuses on the specific assumptions behind its fair value view, so you can track those against Antero Midstream’s actual results over time on Simply Wall St’s Community page.
One of the top community narratives on Antero Midstream: 12% undervalued
"Rising in basin natural gas demand from new West Virginia gas fired power plants and data centers is expected to increase throughput on Antero Midstream’s gathering and intrastate pipeline system…"
Discover why this Narrative puts Antero Midstream at 12% undervalued.
One more Antero Midstream cross-check that sits outside the current price
Market ratios tell you what investors pay today, while forward looking analyst models sketch where they think this business might be a few years out. Lining those side by side can sharpen your view. Explore where analysts expect Antero Midstream to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com