
Deutsche Telekom (XTRA:DTE) Stock May Be Undervalued Despite Fresh Cloud Security News
Deutsche Telekom has seen its share price retreat in recent months after a strong multi‑year run. This puts fresh attention on whether the current valuation is still supported by the company’s earnings power. With new cloud and security partnerships in play, the question now is how much of that operational story is already reflected in today's price.
- Over the past 5 years the stock has delivered a total return of 76.4%. This raises the issue of how much long term earnings strength the market is pricing in today.
- The recent rollout of Titan.ium’s iDNS on Deutsche Telekom’s horizontal cloud and the Cloudflare security tie‑up can influence expectations for future profitability, since they may support more efficient networks and higher value enterprise services.
- The analysts covering Deutsche Telekom have run their own numbers. See what analysts think Deutsche Telekom's shares could be worth.
The stock's next move may depend on whether its current share price is appropriately aligned with the earnings Deutsche Telekom is generating today.
If you want to stress test this same earnings question beyond Deutsche Telekom, you can apply the same lens across 179 high quality undervalued stocks.
Does Deutsche Telekom Look Undervalued on Earnings?
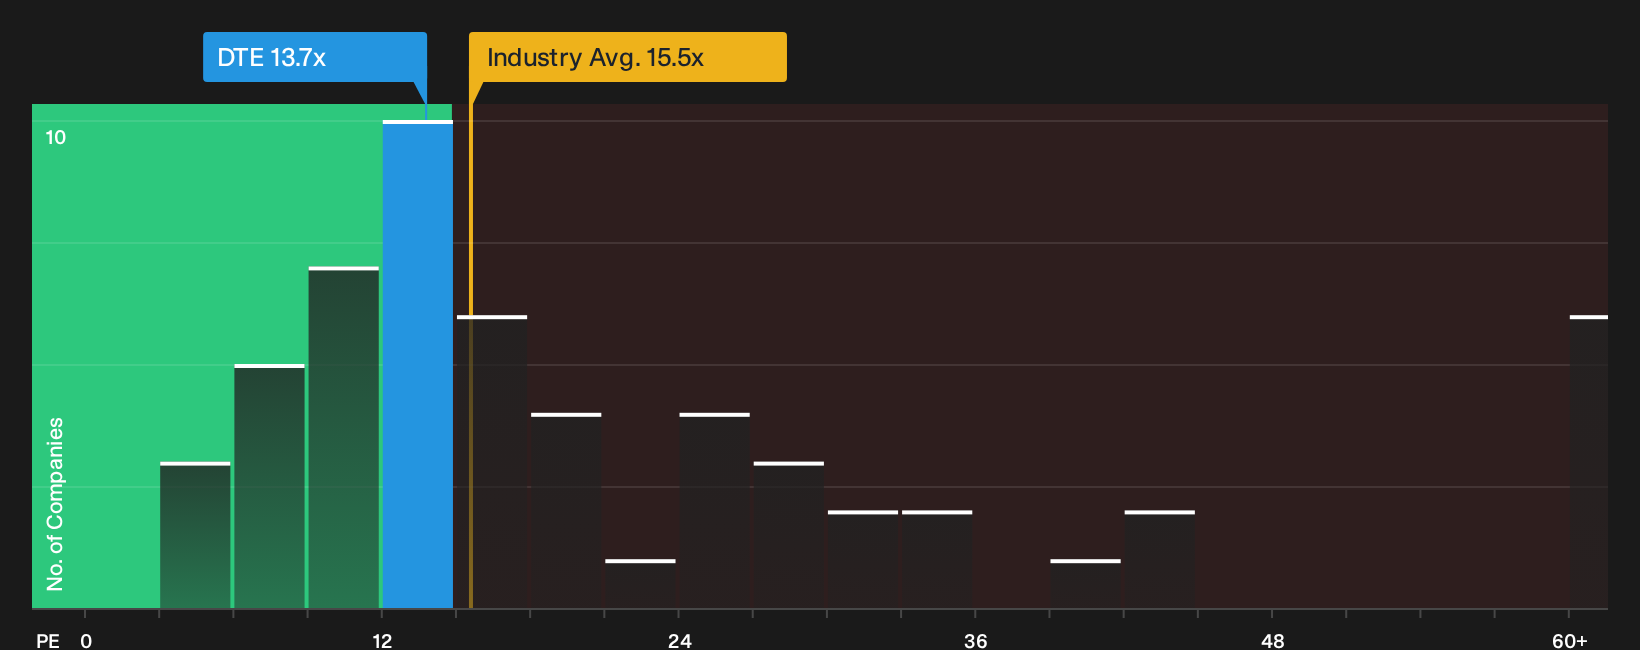
The P/E ratio fits Deutsche Telekom well because earnings remain the main yardstick investors use for large, mature telecom groups. On this measure, the stock trades on a P/E of 13.7x, compared with a Telecom industry average of 15.0x and a wider peer group closer to 21.1x. That places the shares below both the sector level and the broader peer set on an earnings basis, even after a strong multi year return profile.
Fair value modelling that adjusts for Deutsche Telekom’s own growth outlook, profitability and risk points to a higher P/E as a tailored reference point. This leaves the current 13.7x screening as undervalued on this framework. Because the recent Cloudflare security partnership and Titan.ium iDNS rollout both speak directly to enterprise and network efficiency ambitions, the existing earnings multiple may not be charging a full premium for those efforts. Explore the numbers behind Deutsche Telekom's P/E valuation.
The Deutsche Telekom Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Deutsche Telekom. They spell out which combinations of growth, margins and earnings paths would need to play out for the share price to sit meaningfully above or below today's level. Each one lays out the assumptions behind its own fair value estimate so you can compare those expectations with actual results on Simply Wall St's Community page as they arrive.
One of the top community narratives on Deutsche Telekom: 32% undervalued
"Disciplined capital allocation, with leverage kept below 2.75x while Deutsche Telekom plans almost €10b of 2026 shareholder returns through buybacks and dividends..."
Discover why this Narrative puts Deutsche Telekom at 32% undervalued.
Deutsche Telekom’s valuation is only one side of the story
Price multiples and shareholder return plans frame Deutsche Telekom in one light, but the in house checks also raise specific concerns that deserve attention before drawing a conclusion. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com