
3 Stocks To Watch As Emerging Market Debt Stress Reshapes Funding Winners
Global bond markets are lurching, borrowing costs for emerging economies are under pressure, and suddenly the quiet world of sovereign and corporate debt feels very loud. For investors, stress in funding markets can reshape which stocks quietly absorb the shock and which potentially benefit as capital is repriced. This article walks through 3 stocks from our Global Emerging Markets Debt & Bond-Financing Ecosystem screener that appear positively exposed to the latest debt market shake-up.
The 3 stocks below are only a starter set from this theme. The full screen surfaced 15 more publicly listed asset managers, banks, and insurers with equally compelling emerging markets debt stories that are not covered here. To see the wider opportunity set in one place, head straight into the Global Emerging Markets Debt & Bond-Financing Ecosystem screener to identify, analyze, and focus on the ideas that best fit your own conviction and risk profile.
Brookfield (TSX:BN)
Brookfield gives you exposure to a global pool of real assets and credit, including platforms that can touch emerging market borrowers. This matters when funding conditions in sovereign and corporate debt markets are being repriced and capital is hunting for scaled owners of hard assets.
Brookfield is a global multi-asset manager investing in real estate, infrastructure, renewable power, credit, private equity, and venture capital, with credit and infrastructure arms that can include emerging market sovereign and corporate borrowers. Its biggest revenue contributors are Private Equity at about US$28.7b, Infrastructure at roughly US$26.2b, Asset Management at around US$14.4b, and Renewable Power and Transition at close to US$7.8b, alongside smaller Real Estate and Corporate lines, and it carries a market value of roughly CA$118.2b.
"Carry realisations accelerate over the next several quarters: Q2 net realised carry was US$121m, LTM US$520m, BN-share accumulated US$9.6bn less ~US$2.9bn costs, and US$6bn net is expected to be realised within three years."
What really matters now is how one still unresolved pressure on Brookfield’s funding mix ultimately feeds through to future earnings resilience.
To see how that funding question, the carry engine, and Brookfield’s wider real asset platform all connect, move through the full narrative for Brookfield to explore what the headline metrics may be masking.

Ashmore Group (LSE:ASHM)
Ashmore Group is one of the purest listed plays on emerging markets debt, with its whole model tied to how EM sovereign and corporate bond cycles affect assets under management, fee income, and investor appetite for higher yielding debt strategies.
Ashmore Group focuses on managing emerging markets equity and fixed income portfolios, earning about £139 million from investment management services. The London based asset manager runs strategies across external, local currency and corporate debt for global clients and carries a market value around £1.4b.
"Ashmore Group has a long record of seed capital gains, including a large £82.5m contribution in FY26. A moderation in realized gains from this portfolio could remove an important support for profit before tax and leave reported earnings more dependent on subdued core fee income."
There is a key question over what happens if one relatively quiet shift in how those EM focused funds are priced and paid for starts to have a greater impact on future margins.
If that pricing shift is what worries you, move straight into the full narrative for Ashmore Group to see how Ashmore Group’s fee model could be quietly decoupling from sentiment.

Record (LSE:REC)
Record runs currency and asset management strategies that plug directly into emerging market debt flows through FX hedging, EM local debt and EM focused mandates. The group earns about £38 million from Currency Management and roughly £2 million from Asset Management, and carries a market value near £84 million.
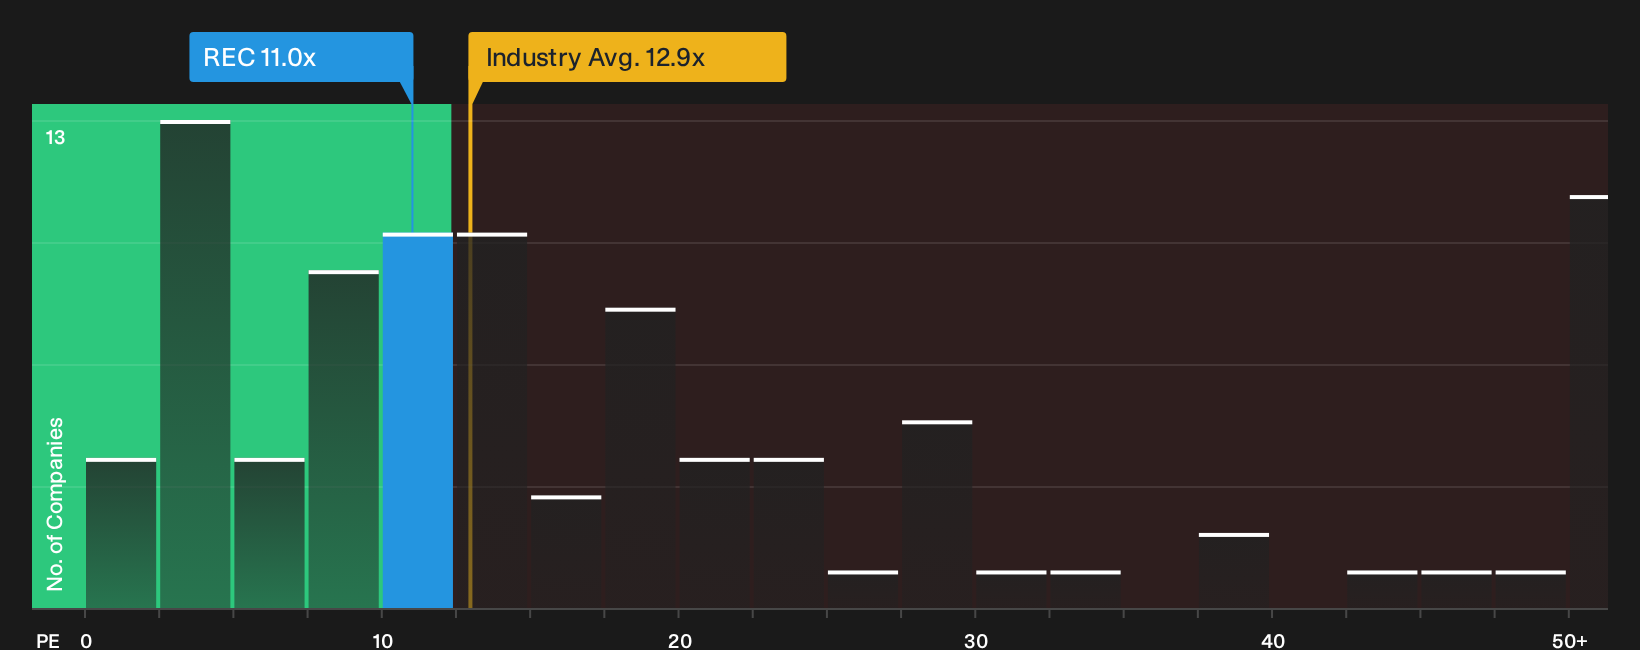
Record sits where EM debt, FX volatility and institutional hedging needs meet, offering currency management and EM local debt products linked to the same stresses hitting sovereign and corporate borrowers. Investors get that tie in plus a relatively low 11x P/E. However, income appeal and valuation both hinge on what happens when one unseen pressure on earnings quality and payouts shifts.
That pressure point on Record’s earnings and payouts is exactly what the 2 key rewards and 1 important warning sign is built to unpack, before the market fully prices it in
Seeking Fresh Alternatives Before They Fly
Markets can move quickly and the freshest breakout ideas rarely stay under the radar for long. Look for momentum while it is still developing, before the crowd catches up, and consider acting while it remains early in the trend.
- Target durable cash generators by scanning a curated list of solid balance sheet and fundamentals (7 results). This can help you focus on resilient operators before weakness in more vulnerable peers becomes widely recognized.
- Track income-focused companies with the 3 dividend fortresses and see which higher-yield payers also have strong balance sheets and payouts that may attract close investor attention.
- Consider positioning for developments in artificial intelligence using the 92 AI infrastructure stocks and find listed suppliers connected to expanding compute demand as the story continues to develop.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com