
Is Edwards Lifesciences (EW) Undervalued After FDA Approval Of Its AUTUS Valve?
FDA approval of AUTUS valve puts Edwards Lifesciences in focus
Edwards Lifesciences (EW) is back on investor radar after the U.S. Food and Drug Administration cleared its AUTUS Size-Adjustable Valve for pediatric pulmonary valve replacement, a first-of-its-kind device designed to expand as children grow.
Set against this clinical milestone, Edwards Lifesciences has had a mixed run on the market, with the share price slipping 7.17% over the past 90 days. A 1-year total shareholder return of 15.24% suggests longer term holders have fared better than recent buyers.
Scan other cardiology-focused opportunities that are moving on clinical progress and balance-sheet strength with our curated list of solid balance sheet and fundamentals (25 results), which echo parts of the Edwards Lifesciences story.
The AUTUS win and steady 1-year return of 15.24% leave Edwards Lifesciences at an interesting crossroads. Is most of the easy upside already cashed in, or do the current numbers still argue for more opportunity?
Most Popular Narrative: 16% Undervalued
On the most followed view, Edwards Lifesciences carries an estimated fair value of about $101 per share versus a last close of $85.21. This puts the focus squarely on whether the current price fully reflects its volume and margin ambitions.
The main factor that has to go right is successful execution on the multi-platform structural heart strategy. This includes TMTT growth toward the stated 2030 revenue goal and continued translation of long-term clinical data into physician preference.
See why 28 investors see Edwards Lifesciences as 16% undervalued.
Result: Fair Value of $100.96 (UNDERVALUED)
Still, the narrative can crack if tariff related cost pressure squeezes margins, or if insider selling and governance concerns keep weighing on Edwards Lifesciences’ valuation.
Find out about the key risks to this Edwards Lifesciences narrative.
Another View: Edwards Lifesciences On Earnings Multiples
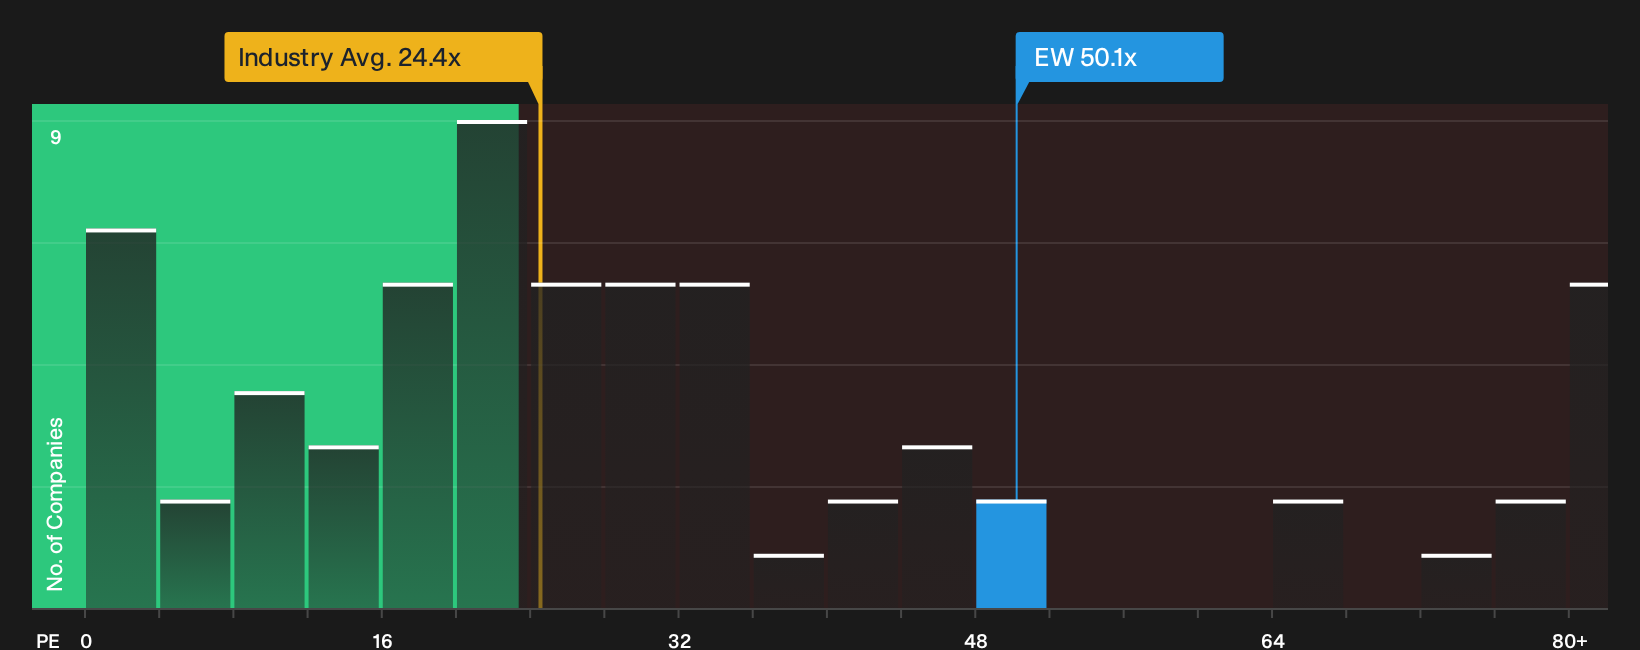
There is a catch. While the SWS fair value suggests Edwards Lifesciences trades about 5.8% below that estimate, the P/E ratio of 50.1x looks rich next to a fair ratio of 32.6x, the US Medical Equipment industry at 24.4x and peers at 26.1x. Is the extra premium a cushion or a thin tightrope for new buyers?
To see how those earnings multiples stack up in more detail, and what the numbers say about valuation risk versus upside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Edwards Lifesciences so far, right? Use this as a starting point, move quickly through the key numbers, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Edwards Lifesciences style investment ideas?
If Edwards Lifesciences has your attention, do not stop here. The real edge often comes from scanning wider and spotting the next opportunity early.
- Target resilience first and filter for businesses with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality and see which companies the data flags as 29 high quality undervalued stocks.
- Prioritise capital protection and shortlist 31 resilient stocks with low risk scores before committing fresh cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com