
Amplitude (AMPL) Shares Climbed, What Is Behind The Attention?
Amplitude (AMPL) has caught investor attention after a run to its 52 week high of US$15.29, coinciding with fresh AI tools on its analytics platform and deeper enterprise and international adoption.
Momentum has been building for some time, with a 90 day share price return of 67.41% and a year to date gain of 43.37% at a latest share price of US$15.67. The 1 year total shareholder return of 57.65% contrasts with a 5 year total shareholder return that is down 72.03%.
Scan how Amplitude’s AI-fueled momentum compares with other fast-moving software plays by reviewing our hand picked 39 profitable AI stocks that aren't just burning cash that are gaining traction from real revenues.
Amplitude now looks like a stronger product story than it did a year ago. After such a sharp re-rating, the real work is figuring out whether the current share price already reflects that strength.
Most Popular Narrative: 14% Overvalued
Amplitude closed at $15.67, while the most followed narrative pegs fair value at $13.77 using an 8.53% discount rate. As a result, the story hinges on whether the recent re-rating has already priced in much of the AI and product expansion upside.
The trend of digital transformation and the shift toward unified, data-driven business processes are creating tailwinds, as more customers seek to consolidate legacy and point solutions onto integrated platforms like Amplitude, driving both new logo acquisition and major upsell/cross-sell opportunities, fueling durable, long-term revenue growth and improved free cash flow visibility.
See why 9 investors see Amplitude as 14% overvalued.
Result: Fair Value of $13.77 (OVERVALUED)
Still, Amplitude’s heavy AI investment, without clear monetization and with increased reliance on larger enterprise contracts, could quickly test this upbeat narrative if adoption or retention underwhelms.
Find out about the key risks to this Amplitude narrative.
Another View: Cash Flows Point in a Different Direction
Price targets built from earnings forecasts lean toward Amplitude being overvalued, yet the Simply Wall St DCF model presents a different view and points to a future cash flow value of $23.25 per share. This is above the recent $15.67 price and frames the stock as undervalued on that measure.
The split between an earnings-based fair value of $13.77 and a cash flow estimate nearly $10 higher raises a practical question for you as an investor: which perspective seems more realistic for how Amplitude will translate today’s AI and analytics spending into long-run cash generation?
Look into how the SWS DCF model arrives at its fair value.
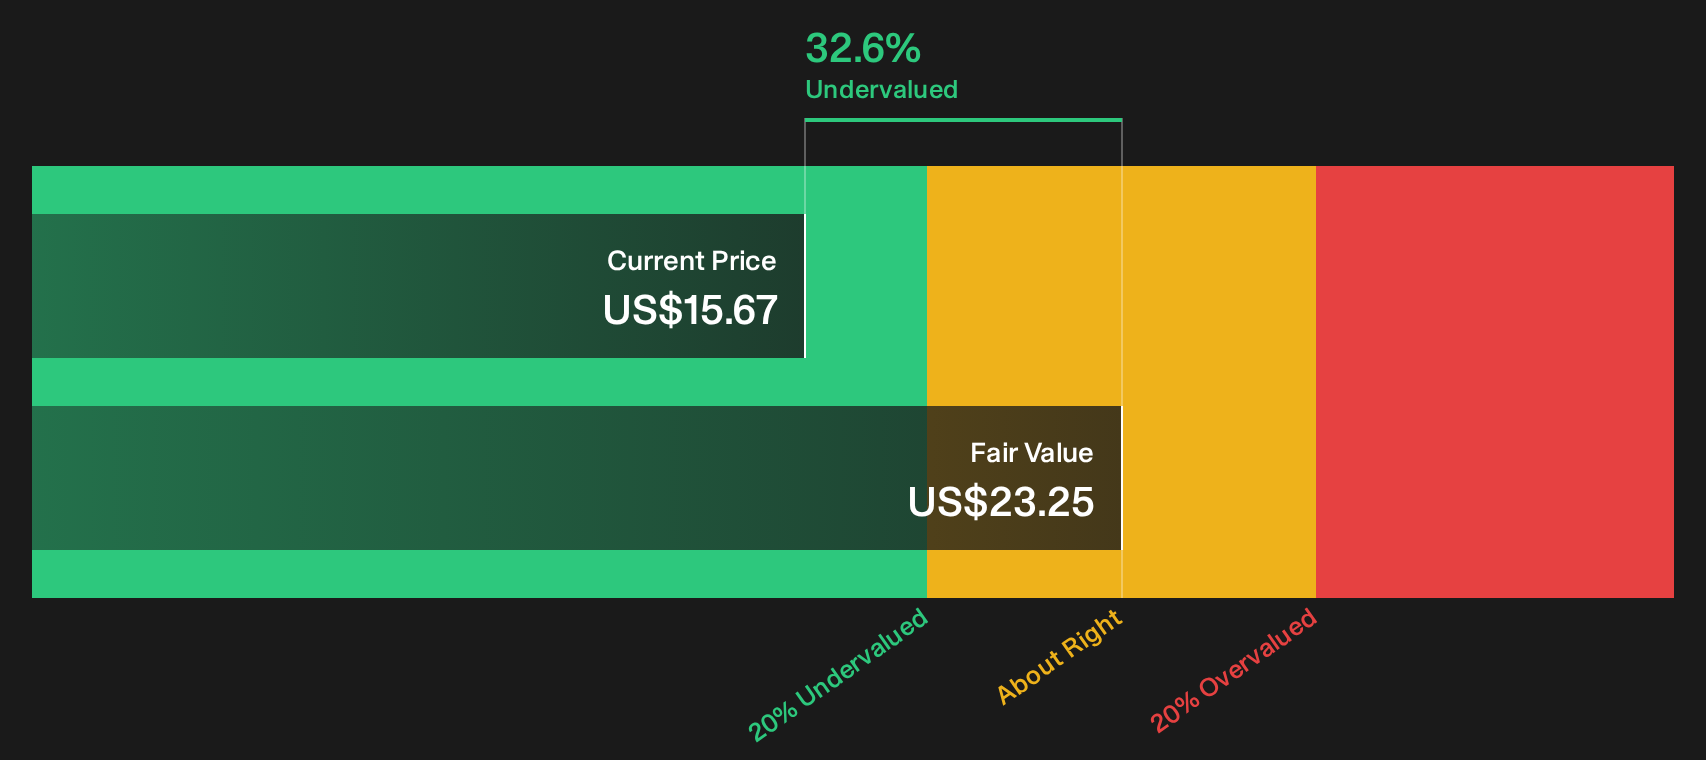
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amplitude for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Amplitude so far. If the cross currents of enthusiasm and concern feel familiar, move quickly to stress test the data yourself and weigh both the potential upside and the open questions using 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Amplitude?
If Amplitude has sharpened your view on pricing and potential, do not stop here. Broaden your watchlist with other focused ideas built from real fundamentals.
- Target reliable income streams by scanning companies that show resilient payouts and balance sheet support through our 8 dividend fortresses.
- Hunt for mispriced quality by reviewing the 29 high quality undervalued stocks that combine stronger cash profiles with underappreciated market expectations.
- Prioritise resilience first by filtering for 31 resilient stocks with low risk scores that score well on stability so you are not chasing excitement at the expense of durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com