
Armstrong World Industries (AWI) Faces A Fresh Valuation Test After Sales Leadership Change
Sales leadership transition puts Armstrong World Industries in focus
Armstrong World Industries (AWI) is entering a key sales leadership transition after Senior Vice President of Sales and Marketing Jill A. Crager announced plans to retire at the end of 2026.
Her planned departure after 28 years, along with the search for a successor, gives investors a fresh reason to look at how this building products specialist is positioned across its Mineral Fiber and Architectural Specialties segments.
Recent trading has been softer, with the share price down 17.77% year to date and the latest close at US$161.87. However, the 3 year total shareholder return of 134.86% and 5 year total shareholder return of 72.89% point to strong longer term momentum for Armstrong World Industries.
Scan how Armstrong World Industries compares with a hand picked list of solid balance sheet and fundamentals (25 results) that may be better positioned for the kind of leadership shifts influencing sales driven manufacturers.
Recent weakness and long term gains tell different stories about Armstrong World Industries. Are investors reassessing the business itself, or has sentiment simply swung? And what does that mean for the current valuation set up?
Most Popular Narrative: 23% Undervalued
Against a last close of $161.87, the most followed narrative pins Armstrong World Industries' fair value at $210.18, which frames recent share price weakness as a discount rather than a verdict on the business.
The acceleration of TEMPLOK energy-saving ceilings and related growth initiatives, supported by a project pipeline that more than doubled between Q1 and Q2 2026 and by broader use across financial institutions, healthcare, education and small business renovations, is expected to support higher Mineral Fiber revenue and help protect gross margins as customers seek energy savings and tax incentives.
See why 2 investors see Armstrong World Industries as 23% undervalued.
Result: Fair Value of $210.18 (UNDERVALUED)
Still, the thesis around Armstrong World Industries relies on commercial projects staying on track and on Architectural Specialties avoiding further investigation-driven execution setbacks.
Find out about the key risks to this Armstrong World Industries narrative.
Another View: What Multiples Say About Armstrong World Industries
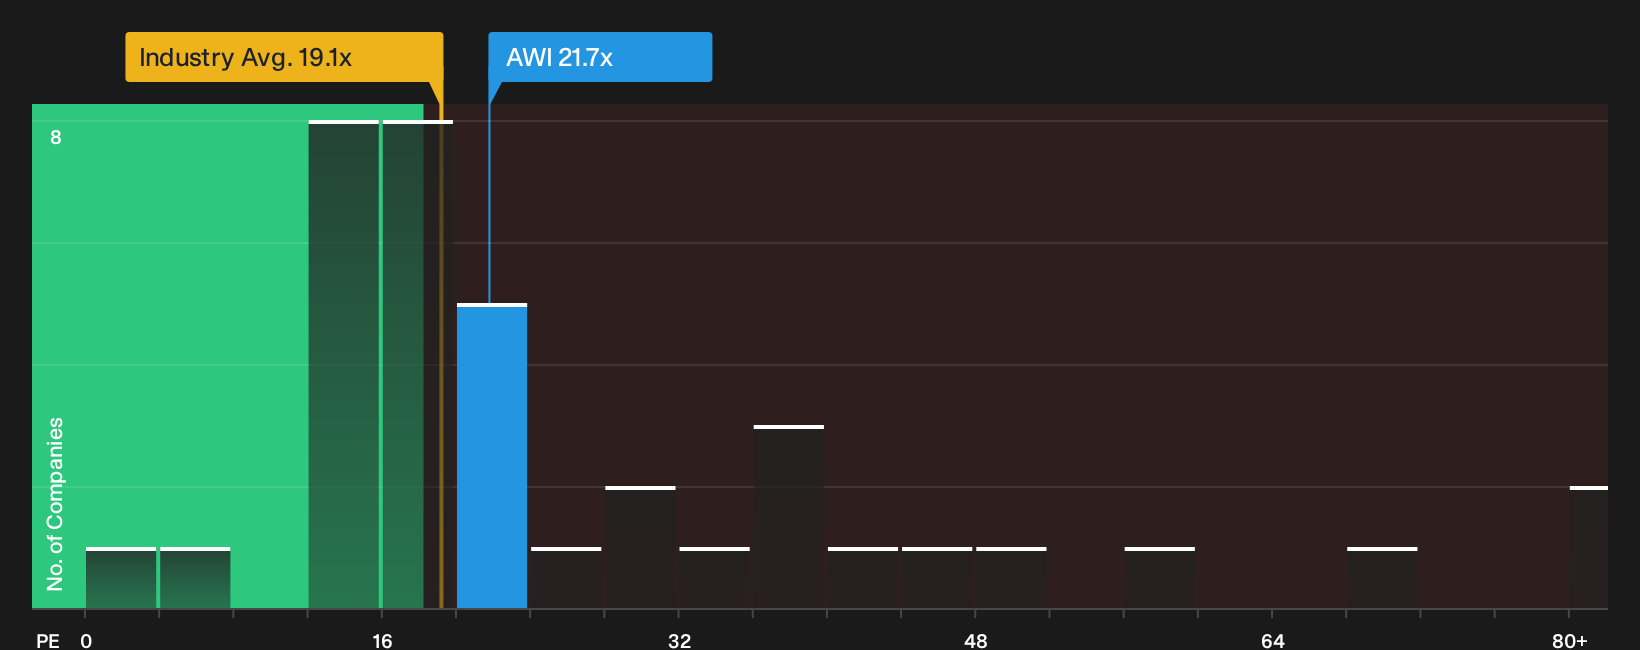
On the flip side of that fair value of $210.18, the current P/E of 21.7x paints a less generous picture. It is higher than the US Building industry at 19.1x and even above an estimated fair ratio of 20.7x, which suggests some valuation risk if sentiment cools or expectations reset.
For a closer look at how this pricing stacks up against sector peers and where the ratio could drift if the market leans back toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Armstrong World Industries is clear, with both concerns and bright spots in play. Treat this as a prompt to check the underlying data, weigh the trade offs, and decide whether the story still fits your own thesis by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Armstrong World Industries?
If Armstrong World Industries has sharpened your thinking, do not stop here. Broaden your watchlist with focused ideas built from clear financial filters.
- Target potential mispricings by scanning a 29 high quality undervalued stocks that filters for quality fundamentals paired with compressed valuations.
- Strengthen your income stream by reviewing a curated 8 dividend fortresses that screens for higher yields with backing from underlying cash flows.
- Dial down portfolio stress by focusing on resilience through a 31 resilient stocks with low risk scores built around lower risk profiles and steadier financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com