
Cellebrite DI (CLBT) Following CEO Change And Guidance Cut Looks Caught Between Risk And Value
Cellebrite DI (NasdaqGS:CLBT) is in focus after an August 13, 2026 announcement that cut full year guidance, missed its annual recurring revenue projection, and cited foreign entity permit delays.
The sharp share price drop following the August 13 announcement capped a tougher stretch for Cellebrite DI, with the stock down 30.2% on a 90 day share price return and 36.9% on a year to date share price return. However, the 3 year total shareholder return remains positive at 60.4%, suggesting long term holders have still seen gains even as recent momentum has faded.
Compare how Cellebrite DI's recent setback measures up against other software players by scanning our hand picked 20 high quality undiscovered gems that currently sit off most investors' radar.
Cellebrite DI now trades well below both analyst targets and one estimate of intrinsic value after the August reset. Is that discount compensation for real execution risk, or is the market leaning too far into caution?
Most Popular Narrative: 26.7% Undervalued
Cellebrite DI closed at $11.26, while the most followed valuation narrative places fair value at about $15.36, which implies a sizeable gap that investors now have to judge against execution risk and guidance cuts.
The continued transition to a recurring, subscription-based revenue model, with over 90% of revenues now from subscriptions and growing SaaS/cloud penetration, improves revenue visibility, predictability, and operating leverage. This is already translating into higher EBITDA and free cash flow margins and is likely underappreciated in current valuations.
See why 20 investors see Cellebrite DI as 27% undervalued.
Result: Fair Value of $15.36 (UNDERVALUED)
Still, the analyst story around Cellebrite DI can unravel if reliance on US federal contracts continues to disrupt ARR or if tighter privacy rules curb demand for its forensics tools.
Find out about the key risks to this Cellebrite DI narrative.
Another View: Cellebrite DI Looks Expensive On Earnings
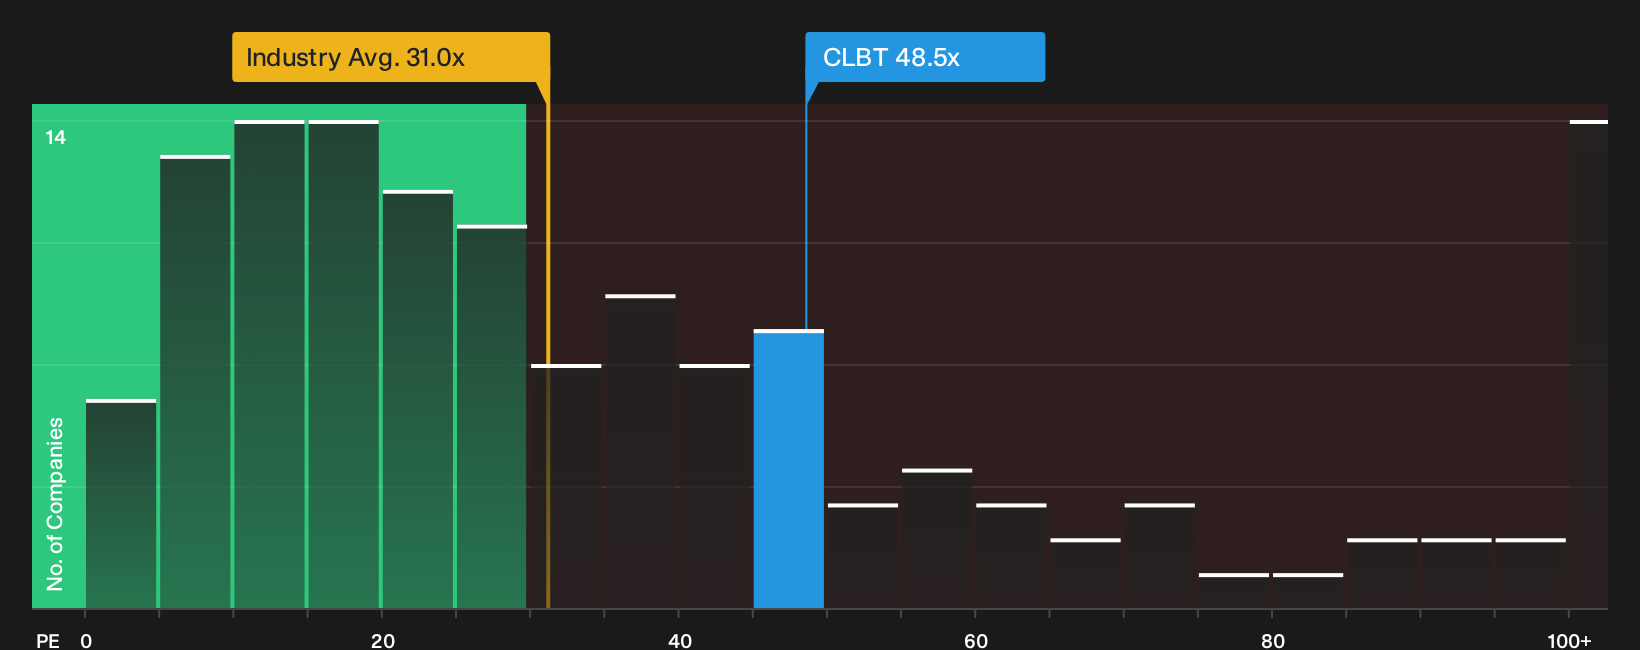
On price to earnings, Cellebrite DI tells a different story. The stock trades on a P/E of 48.5x, compared with 31x for the broader US Software group and a fair ratio of 33.8x, even though it is only roughly in line with a 49.2x peer average. That premium can signal upside conviction or simply raise the risk that any further disappointment compresses the multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Cellebrite DI story points both ways, so move quickly to review the full breakdown of risks and potential upsides for yourself with 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cellebrite DI?
If Cellebrite DI has you rethinking your portfolio, use this moment to widen your field of vision and pressure test your next moves with fresh ideas.
- Target potential mispricings by scanning a curated pool of cash generative, strong balance sheet companies using the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient payers and their payouts through the 8 dividend fortresses.
- Guard against big portfolio shocks by focusing on financially robust, historically steadier businesses via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com