
Kerry Group (ISE:KRZ) Just Gave Investors Something To Think About
Kerry Group (ISE:KRZ) has opened a coffee extraction facility in Bethlehem, Pennsylvania, and followed up with an Analyst and Investor Day, giving shareholders fresh detail on its production ambitions and profit targets.
Recent trading has reflected that story. Kerry Group’s share price has climbed 14.43% year to date to €87.25, with a 4.49% 1 month share price return. The 1 year total shareholder return of 16.70% and 3 year total shareholder return of 23.65% point to steady but not spectacular progress, contrasted with a 5 year total shareholder return that has declined 18.28%. This suggests momentum has picked up more recently as investors reassess growth prospects and risks around its expansion plans.
Compare Kerry Group’s momentum and expansion story against a hand picked group of quality food and beverage players using the 178 high quality undervalued stocks as a starting universe.
Bulls see Kerry Group’s coffee push and margin ambitions as underpriced. Bears point to the weaker 5 year return and execution risk. Which side do the current valuation signals support?
Most Popular Narrative: 12% Undervalued
The most followed narrative on Kerry Group pegs fair value at €99.00 against the latest close of €87.25, which implies the market is still applying a discount to its long term margin and growth ambitions.
The Accelerate 2.0 programme, together with portfolio mix improvements and digital initiatives, has already contributed meaningfully to EBITDA margin expansion since 2021 and is tied to 2030 targets of 20% to 21% EBITDA margins. Further execution offers scope for additional net margin and earnings improvement not fully reflected in current valuation.
See why 11 investors see Kerry Group as 12% undervalued.
Result: Fair Value of €99.00 (UNDERVALUED)
Still, if end markets stay weak and currency or input cost pressures bite harder, Kerry Group’s volume, margins and the 12% undervaluation story could unwind.
Find out about the key risks to this Kerry Group narrative.
Another View: Kerry Group On Earnings Multiples
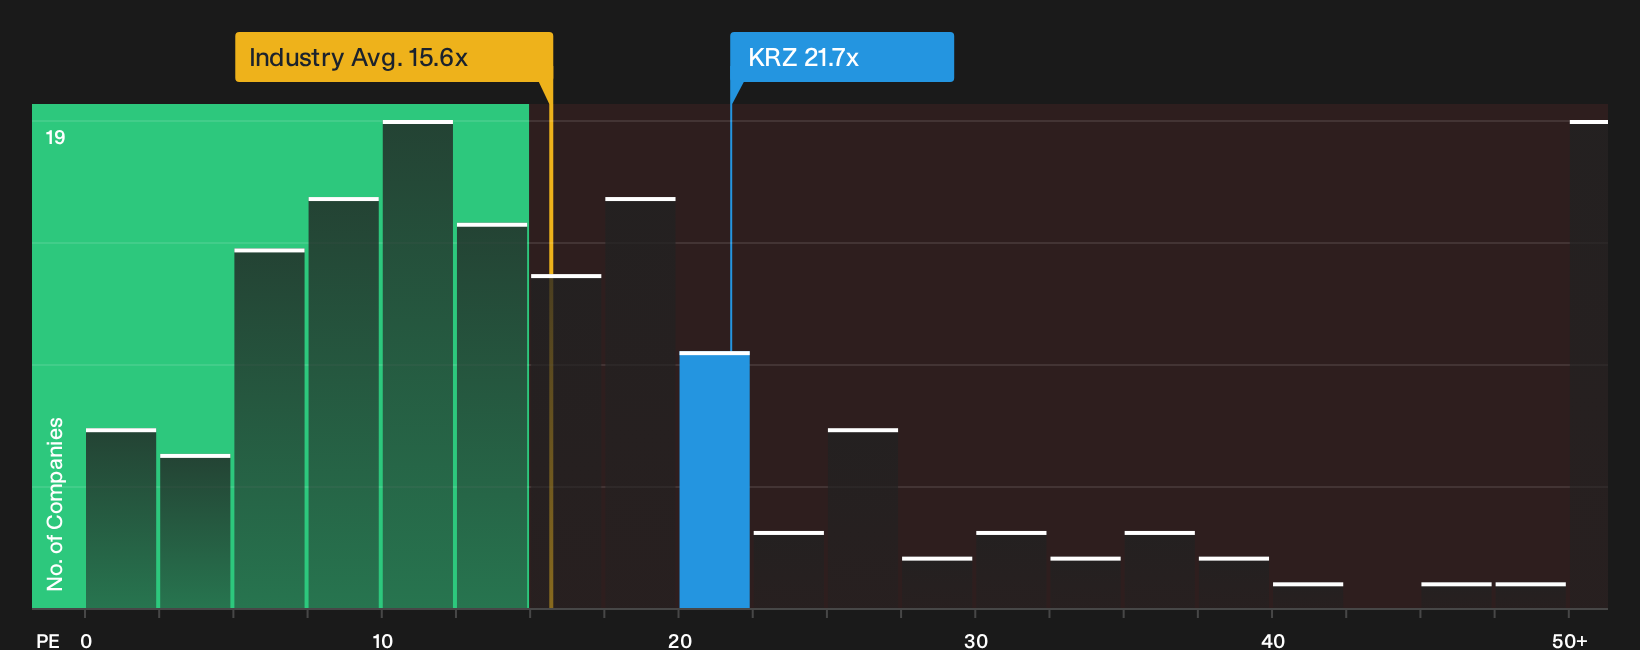
Kerry Group may look cheap on cash flow, but the picture changes when you look at what investors pay for each euro of earnings. The current P/E of 21.7x sits above the European Food sector on 15.6x and above a fair ratio of 18.7x. This points to less margin for error if profit delivery slips.
To see how this earnings multiple could shift if growth, margins or sentiment change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kerry Group is split, which is precisely why it helps to review the data yourself and move quickly while the market debates the story. To see what is driving the more optimistic side of the thesis, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Kerry Group?
If Kerry Group has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few targeted sets of opportunities built from the same data driven process.
- Target stronger balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (204 results) that may better handle shocks and funding needs.
- Hunt for potential mispricings by scanning the 618 high quality undiscovered gems where fundamentals and current prices can look out of sync.
- Dial back volatility risk by assessing the 223 resilient stocks with low risk scores and see which businesses line up with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com