
Viper Energy (VNOM) Looks Repriced After Oil Supply Shocks Lift The Sector
Oil markets snapped higher after a Gulf tanker attack and hurricane related shutdowns squeezed supply, lifting benchmark crude prices and pushing Viper Energy (VNOM) shares up 3.9% in the sector wide rally.
Beyond the one day move, Viper Energy has logged a 5.8% 7 day share price return. However, the 30 day share price performance is down 3.9%, and the 1 year total shareholder return of 24.4% suggests momentum has been building over a longer stretch as investors reassess potential risks and cash flow sensitivity to higher crude prices.
Scan sector moves like Viper Energy's against a curated 29 high quality undervalued stocks that may offer a different balance of price, quality, and resilience to future oil shocks.
Viper Energy looks like a solid royalty business exposed to higher crude prices after this latest spike. The harder question is whether that strength is already fully reflected in the current share price or not.
Most Popular Narrative: 23% Undervalued
Against a last close of $42.99, the leading narrative on Viper Energy anchors fair value at $56. This gap focuses attention on what investors are really buying with each share, not just on the recent oil spike.
"Viper is not merely a stream of today's royalty checks. It is ownership of a large Permian mineral estate through which thousands of existing wells already produce, thousands more are being developed or contemplated, and future operators can continue turning buried geology into royalty income largely with somebody else's capital.
That is what I had failed to value."
See why 24 investors see Viper Energy as 23% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, Viper Energy's narrative can be tested quickly if drilling on its acreage slows sharply or if related party deals with Diamondback start to look expensive.
Find out about the key risks to this Viper Energy narrative.
Another View On Viper Energy’s Valuation
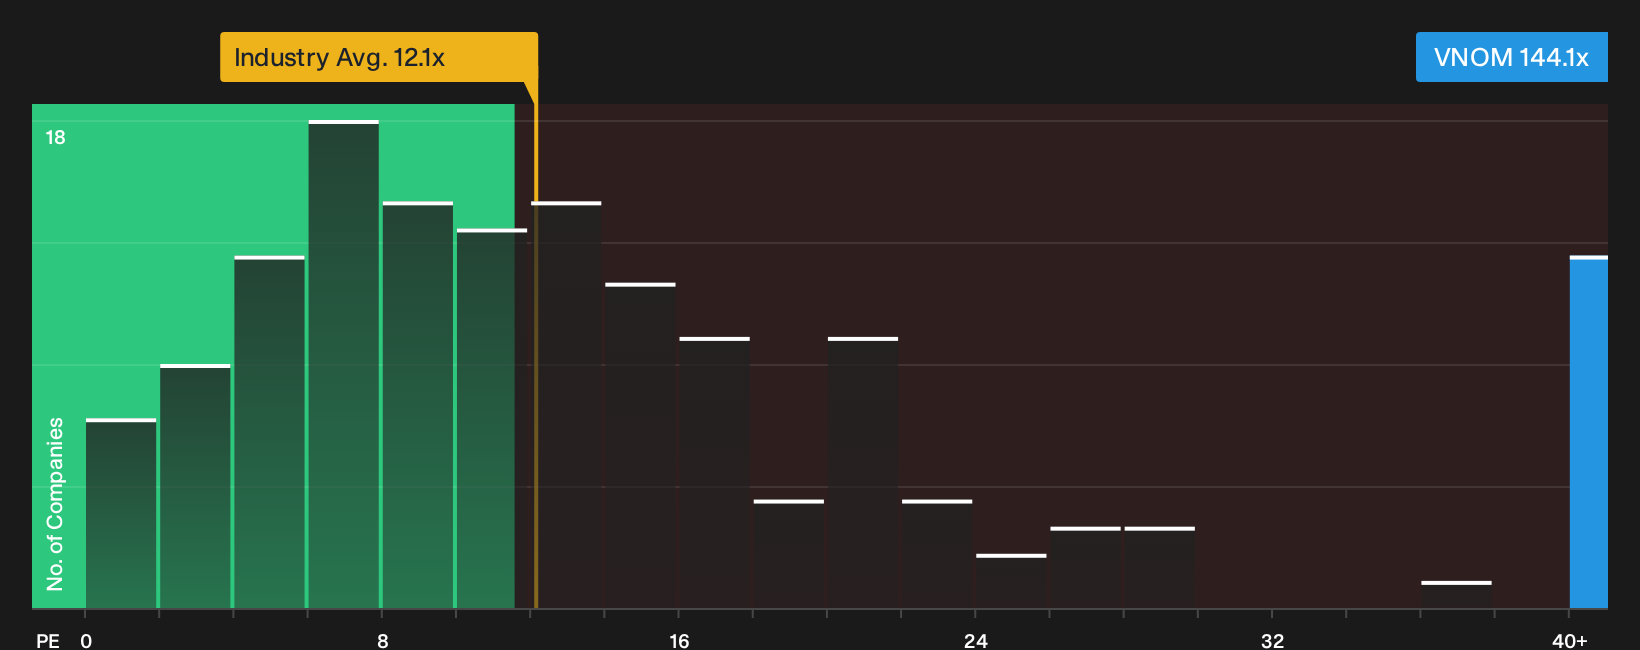
On the flip side of that $56 fair value narrative range, the market is currently putting a very different lens on Viper Energy through its P/E. At 144.1x earnings, the stock trades at a much richer level than direct peers on 10.3x, the broader US Oil and Gas group on 12.1x, and even the estimated fair ratio of 26.7x. That kind of gap can mean investors are paying up heavily for future profit growth, which raises a simple question: What needs to go right for this premium to hold up over time?
For readers who want to pressure test this richer earnings multiple against a fuller breakdown of valuation drivers, it is worth going back to the underlying numbers in our ratio workup. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Viper Energy feels familiar, act while the numbers are fresh and form your own judgment using our breakdown of 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Viper Energy?
Do not stop with a single royalty player. Use the Simply Wall Street Screener to compare Viper Energy with other opportunities and keep your watchlist working harder for you.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that can help cushion portfolio swings when conditions turn rough.
- Hunt for mispriced quality through a focused 29 high quality undervalued stocks that filters for stronger fundamentals at potentially more appealing entry points.
- Build a steadier income stream using a 8 dividend fortresses that highlights higher yielding payouts supported by underlying cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com