
Is General Motors (GM) A Bargain Following Its Oshawa Silverado Production Shift?
General Motors (GM) is reshaping its truck production, confirming it will end light-duty Silverado 1500 assembly in Oshawa this November while ramping up heavy-duty Silverado output and keeping employment levels unchanged.
For investors watching General Motors, the production reshuffle comes after a mixed run in the share price. The 7-day share price return is 5.70%, while the 30-day share price return declined 3.38%. At the same time, the 1-year total shareholder return is 50.76% and the 3-year total shareholder return is 187.45%, which points to stronger momentum over the longer period than in the past month.
Spot emerging truck and auto opportunities by scanning the 29 high quality undervalued stocks that share some of General Motors' mix of scale, capital intensity, and sensitivity to product shifts.General Motors now trades at a clear discount to both analyst targets and intrinsic value estimates after this truck reshuffle and choppy recent returns. Is that a pricing error, or is the market correctly pricing execution risk around its product mix shift?
Most Popular Narrative: 20.6% Undervalued
General Motors closed at $82.73, while the most widely followed narrative pegs fair value at $104.22 using a 12.54% discount rate. As a result, the Oshawa truck reshuffle sits inside a broader story about free cash flow, software, and powertrain spending rather than a simple truck-cycle trade.
Although General Motors is investing heavily in next generation batteries and digital and subscription services, the company is also committing significant capital to new V8 and diesel engines and high annual capex. This increases execution risk and the possibility that these investments do not produce sufficient incremental revenue and margin improvement to support long term earnings growth.
See why 97 investors see General Motors as 21% undervalued.
Result: Fair Value of $104.22 (UNDERVALUED)
Still, quality disputes and federal probes into key engines, along with a reduced EV and hybrid footprint, could quickly challenge the General Motors free cash flow story.
Find out about the key risks to this General Motors narrative.
Another View: General Motors On Earnings Multiples
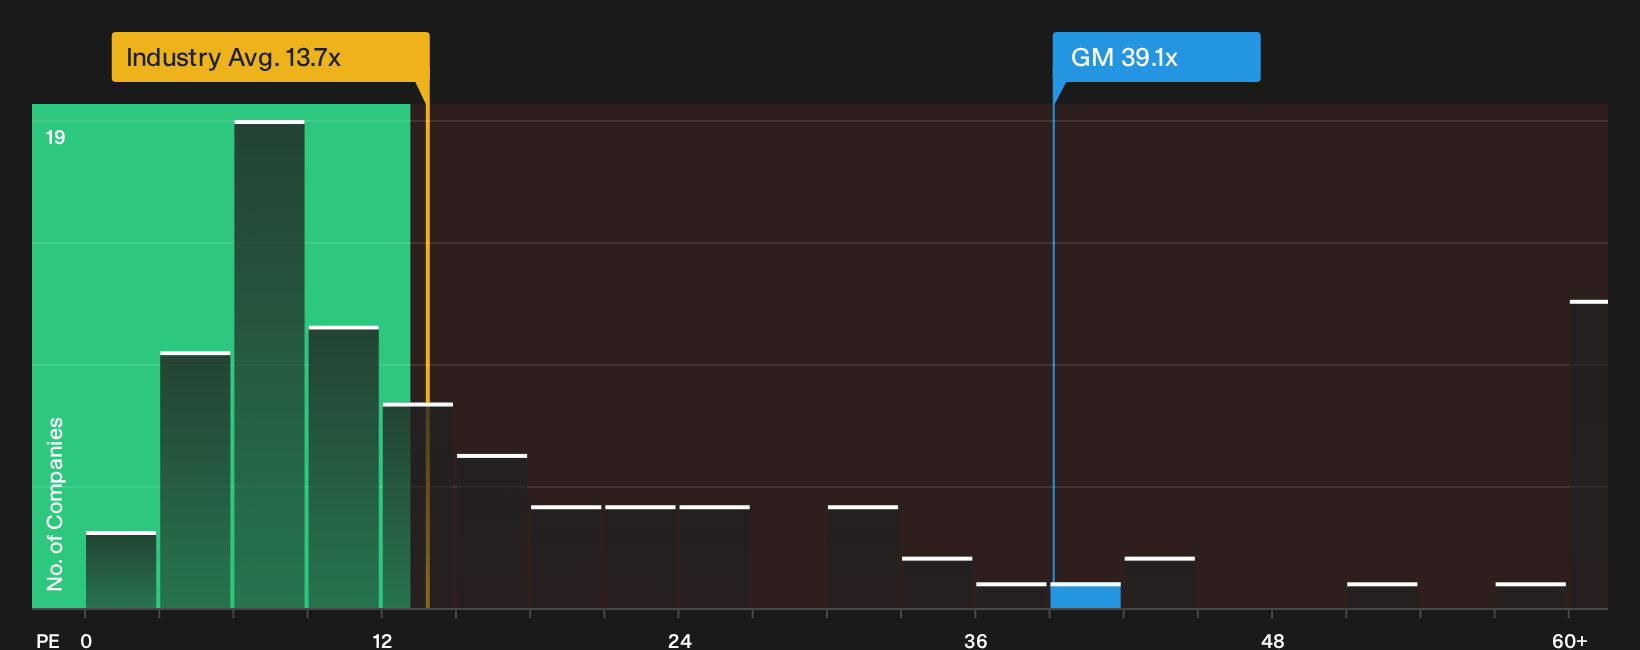
On the flip side of that cash flow story, General Motors currently trades on a P/E of 39.1x, while the fair ratio is 25.8x and the global auto group sits closer to 13.7x with peers around 26.7x. That kind of gap can signal valuation risk rather than a simple bargain. Which signal should an investor focus on in this case?
To stress test this earnings based view against the cash flow case, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity? If General Motors keeps you on the fence, move quickly to check the full picture of 3 key rewards and 4 important warning signs
Looking for more General Motors style ideas?
If General Motors has you thinking bigger about your portfolio, keep going. The right watchlist today can shape the decisions you are ready to make tomorrow.
- Target resilience first and hunt for companies with healthy finances using the list of solid balance sheet and fundamentals (25 results).
- Focus on value and see which opportunities look mispriced on quality and fundamentals with the 29 high quality undervalued stocks.
- Round out your watchlist with income ideas that aim for staying power through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com