
Why Did Nomura Research Institute (TSE:4307) Climb Today?
Nomura Research Institute (TSE:4307) drew investor attention after rising on a weak day for the Nikkei 225, as traders gravitated toward established AI and IT businesses with confirmed FY2027 guidance.
Recent trading has been punchy, with a 5.09% 1 day share price return and a 10.60% 7 day share price return helping Nomura Research Institute reach ¥5,613. This is despite the share price return year to date being down 6.81% and the 1 year total shareholder return being roughly flat at 0.03%. Meanwhile, the 3 year total shareholder return of 52.48% and 5 year total shareholder return of 42.37% indicate that longer term investors may still view the earlier thesis as intact.
Scan for other established AI and IT stocks showing similar resilience to Nomura Research Institute by focusing on the curated 92 AI infrastructure stocks that are underpinning this shift in market preference.
Nomura Research Institute now trades about 6% below the average analyst price target after this sharp rebound. Is that a genuine valuation gap, or a fair discount for the risks the market still sees?
Most Popular Narrative: 5% Undervalued
On the most followed narrative, Nomura Research Institute screens as modestly undervalued, with a fair value of ¥5,914 against the last close at ¥5,613 and a 7.4% discount rate anchoring that estimate.
The analysts have a consensus price target of ¥5913.57 for Nomura Research Institute based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of ¥6700.0, and the most bearish reporting a price target of just ¥5190.0.
See why 0 investors see Nomura Research Institute as 5% undervalued.
Result: Fair Value of ¥5,914 (UNDERVALUED)
Still, the narrative around Nomura Research Institute can shift quickly if high capital demands in overseas projects or weak property related earnings undercut those analyst assumptions.
Find out about the key risks to this Nomura Research Institute narrative.
Another View On Nomura Research Institute’s Valuation
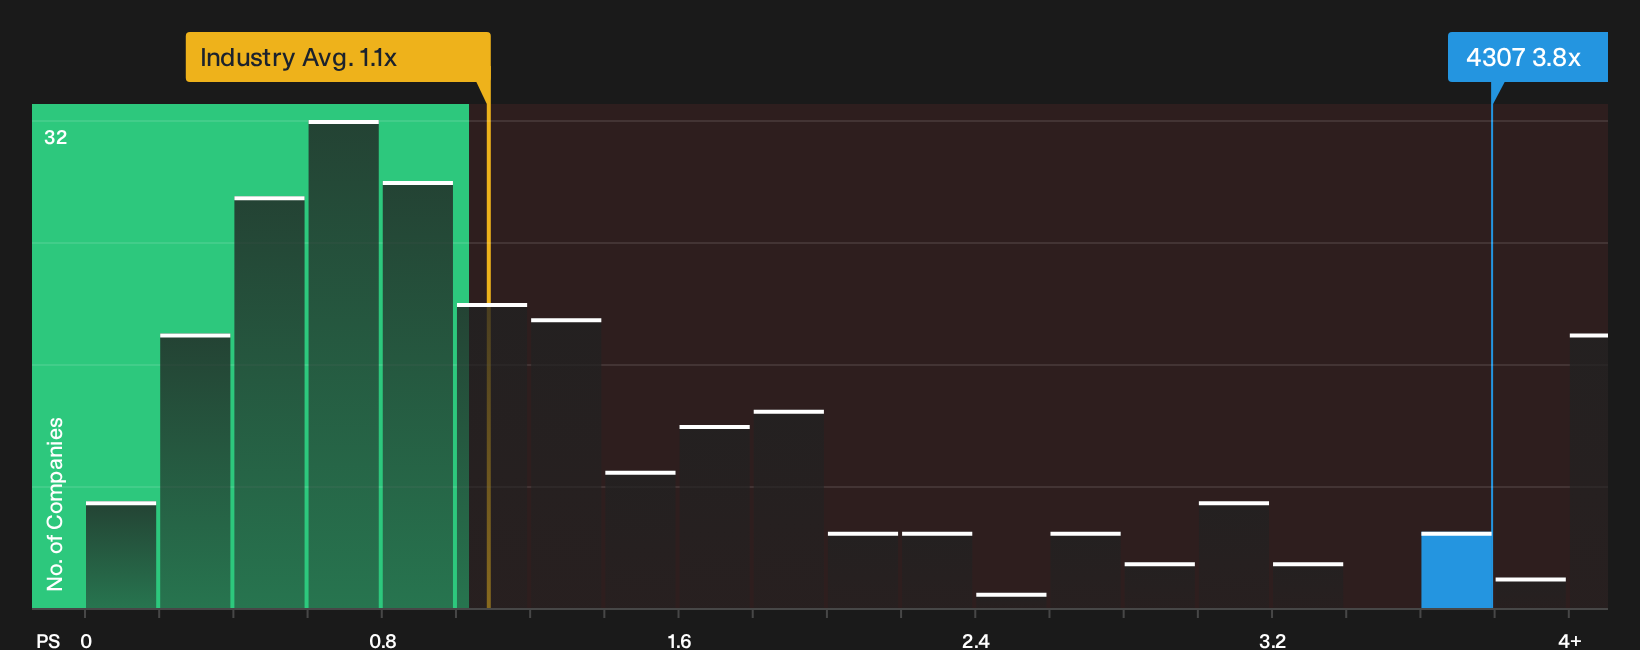
On a simple P/S lens, Nomura Research Institute looks expensive at 3.8x compared with 1.1x for the broader JP IT group. The fair ratio sits higher at 4.9x though, which points to a market that already prices in quality but still leaves some room if sentiment shifts.
That kind of gap cuts both ways. It can reward investors if the share price edges toward the fair ratio, or it can punish latecomers if the sector multiple compresses first, so which side of that trade-off feels more realistic to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Nomura Research Institute so far, with both concerns and bright spots in the data. Consider the details while they are still fresh in mind and weigh those signals yourself by digging into the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Nomura Research Institute?
Do not stop with one opportunity. Broaden your watchlist with fresh candidates that share some of the quality markers you are looking for in Nomura Research Institute.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (23 results) that can help you focus on financially steady businesses when conditions turn choppy.
- Hunt for potential value by reviewing the 13 high quality undervalued stocks that filter for companies combining stronger fundamentals with prices that lag their underlying metrics.
- Spot quieter opportunities early by checking the 74 high quality undiscovered gems that highlight stronger businesses before they draw wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com