
DIC (TSE:4631), Why Is This Materials Name Drawing Fresh Attention?
DIC stock: ECOVART roll out puts low solvent technology in focus
DIC (TSE:4631) has kicked off a global roll out of its low solvent gravure ink ECOVART, targeting packaging printers in Japan, China and Southeast Asia, with an emphasis on reduced use of naphtha based solvents.
Recent trading has reflected growing interest, with DIC’s share price at ¥5,022 and a 30-day share price return of 8.09% building on a 38.35% year-to-date share price return and a 47.91% 1-year total shareholder return. This suggests that momentum has been strengthening.
Spot emerging materials leaders that reflect the same sustainability and momentum trend as DIC in our hand picked 74 high quality undiscovered gems.DIC’s recent run and ECOVART-driven attention create a clear fork in the road for investors. Is it better to lean into this momentum now, or wait for a softer entry as valuation comes into focus next?
Preferred P/E Multiple of 8.4x: Is it justified?
DIC screens as attractively priced on earnings, with the shares at ¥5,022 trading on a P/E of 8.4x against our estimate of good value on this metric.
The P/E ratio compares what investors pay per share with the profit that DIC generates per share. For a materials and chemicals group that already earns money rather than chasing distant break-even, this lens gives you a direct read on how the market prices current profitability relative to peers.
DIC has a few data points that matter here. Earnings grew by 101.7% over the past year and have risen by an average of 26.1% per year over five years. Net profit margins are 5%, higher than last year’s 2.7%, and the business is described as having high quality earnings. In that context, a P/E of 8.4x compared with an estimated fair P/E of 13.8x suggests the market is taking a cautious stance on how durable these profits will be, even though recent growth has been strong.
The relative picture is just as important. DIC trades on a P/E of 8.4x compared with 12.7x for the JP Chemicals industry and 19.1x for the peer average. That is a steep discount. The estimated fair P/E of 13.8x is presented as a level that the valuation could reasonably move towards if profitability and earnings quality stay aligned with recent trends.
Explore the SWS fair ratio for DIC.
Result: Price-to-earnings of 8.4x (UNDERVALUED)
Still, the DIC story can change quickly if ECOVART uptake slows or if raw material costs pressure that 5% net margin and reset earnings expectations.
Find out about the key risks to this DIC narrative.
Another view on DIC’s value
The earlier P/E work paints DIC as inexpensive. A second lens, the SWS DCF model, values the shares at ¥8,580.55 versus today’s ¥5,022, which implies the stock trades at a steep discount. That gap raises a simple question: Is the market mispricing future cash flows or seeing risks this model does not?
Look into how the SWS DCF model arrives at its fair value.
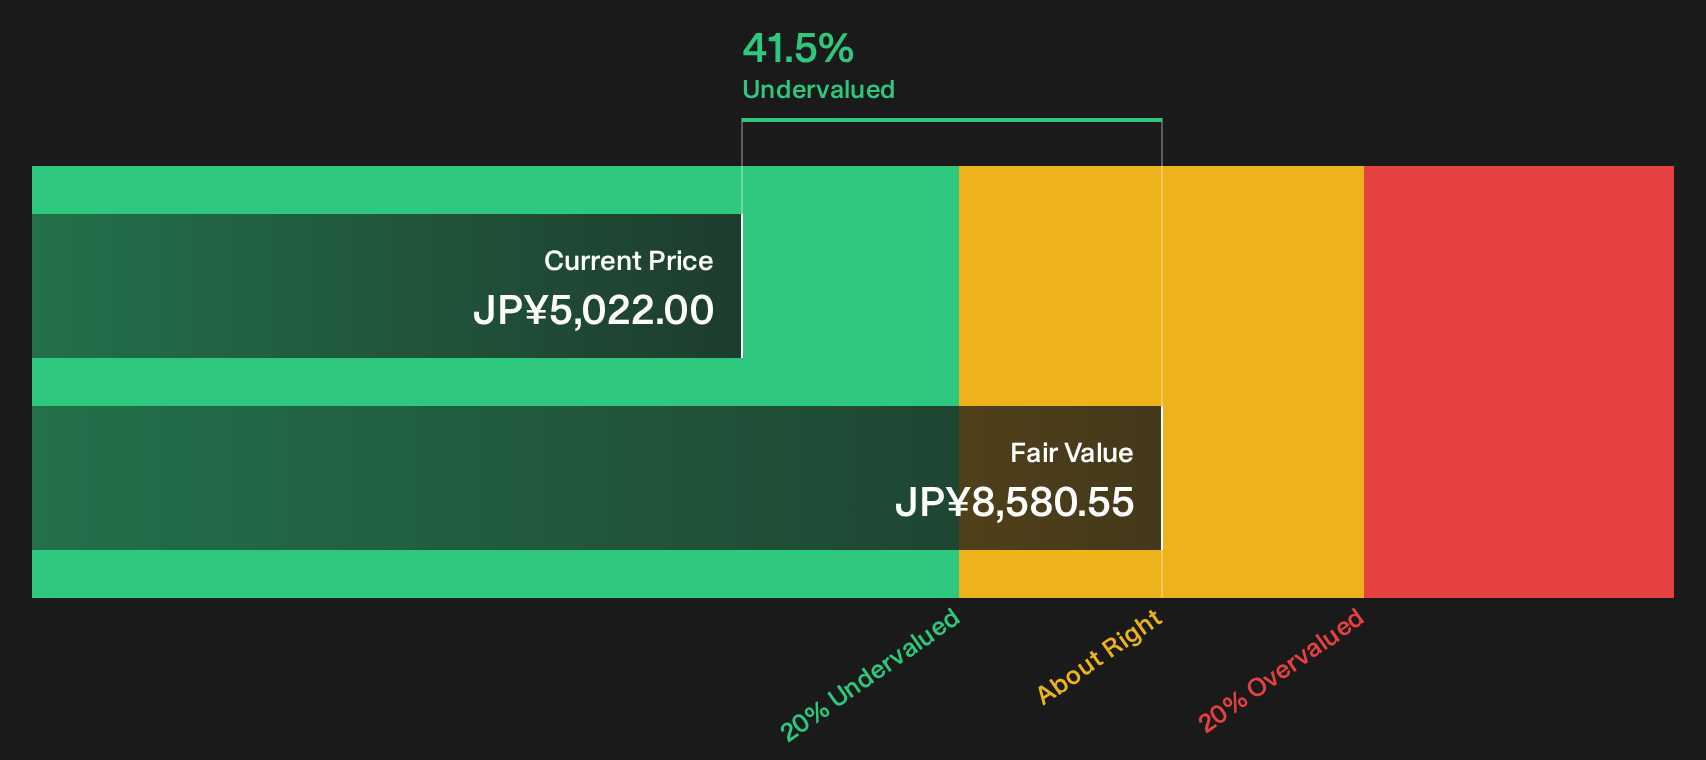
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DIC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the optimism around DIC matches its underlying risk profile? Act promptly, review the data for yourself, and consider both perspectives through the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond DIC?
Do not stop with one promising story. Use this moment to widen your watchlist and pressure test DIC against other opportunities built on different strengths.
- Target resilience first and check out companies that clear our balance sheet and fundamentals filters through the list of solid balance sheet and fundamentals (23 results).
- Hunt for value and scan for companies that look attractively priced relative to quality using the 12 high quality undervalued stocks.
- Seek stability in choppy markets and focus on income payers by reviewing our hand picked 28 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com