
Sanmina (SANM) Could Be 16% Undervalued After Its AI And Cloud Growth Narrative
Sanmina (SANM) is back in focus after fresh attention on its role as an integrated manufacturing partner to major industrial, medical, defense, automotive, communications, and cloud infrastructure customers highlighted its scale and diversification.
The recent attention comes after a sharp year-to-date share price return of 36.54% and a very large 5-year total shareholder return of 450.33%. A 7-day share price pullback of 5.04% contrasts with steady gains over 30 and 90 days, which hints that momentum is still broadly intact despite short-term swings.
Spot similar manufacturing and electronics specialists showing strong multi-year momentum by scanning our hand picked 20 high quality undiscovered gems alongside Sanmina's latest move.After a near 5x total return in five years and a US$217.49 share price, Sanmina now sits at a crossroads. Is the recent surge the end of the rerating, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 16% Undervalued
On the most followed view, Sanmina's fair value of $260 sits above the last close at $217.49. This puts the recent rally in a different light and shifts attention to whether the AI and cloud build out can keep supporting that gap.
The integration of ZT Systems into Sanmina is now contributing several billions of dollars of annualized revenue, and management continues to point to a path toward at least US$16b of revenue in fiscal 2027. If executed, this would materially lift overall revenue and earnings power.
See why 17 investors see Sanmina as 16% undervalued.
Result: Fair Value of $260 (UNDERVALUED)
Still, the narrative around Sanmina can unwind quickly if elevated inventory tied to AI racks proves mistimed or if further governance issues reignite concern after the whistleblower case.
Find out about the key risks to this Sanmina narrative.
Another View: Sanmina On Earnings Multiples
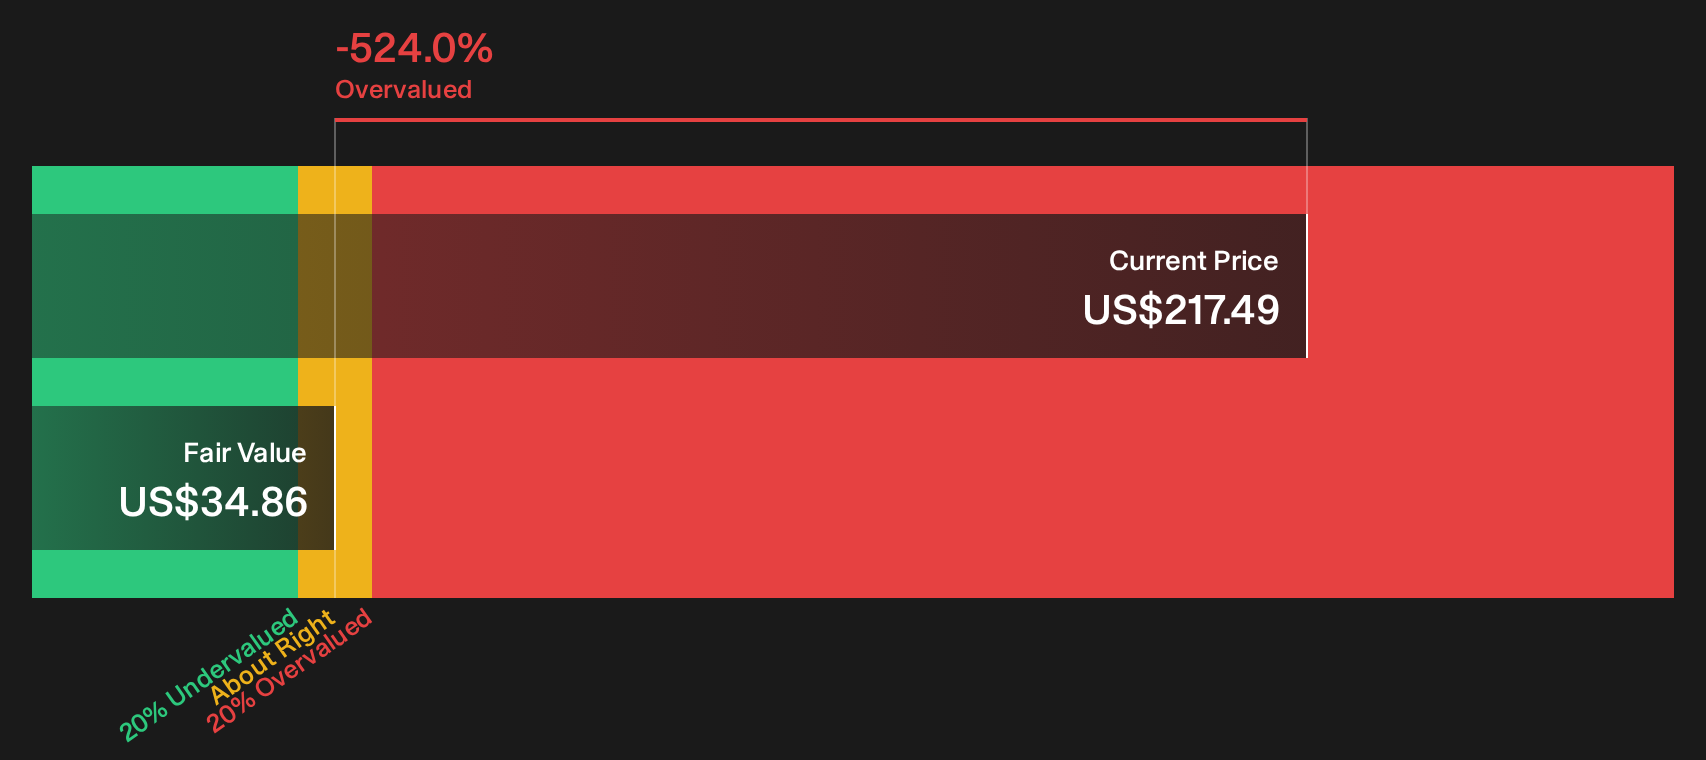
The SWS DCF model points to a fair value well below the current $217.49, with Sanmina trading above an estimated future cash flow value of $34.86. That presents a very different story compared with the $260 fair value narrative and raises a simple question: Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Sanmina is divided, so it is important to review the underlying data yourself and decide where you stand. To consider both sides of the story, take a closer look at the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Sanmina?
If you stop with Sanmina, you risk missing other opportunities that fit your style, so use the screener to surface fresh ideas fast.
- Spot potential turnarounds early by scanning 14 elite penny stocks with strong financials that pair smaller market values with underlying fundamentals that may differ from what many expect.
- Focus on quality at a sensible price by reviewing 28 high quality undervalued stocks that combine cash generation with balance sheets that can support company plans.
- Build a watchlist aimed at stability by focusing on 31 resilient stocks with low risk scores designed to prioritise financial resilience and lower measured risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com