
United Parcel Service (UPS) Could Be 22% Below Fair Value As Security Rollout Lands
United Parcel Service (UPS) is heading into the 2026 holiday rush with new tools focused squarely on security and visibility, including RFID-powered tracking and PIN-based Protected Delivery for high value parcels.
The new security and tracking rollout lands at a time when United Parcel Service shares have been under pressure in recent months, with a 90 day share price return down 15.9% and year to date share price return down 6.4%. However, the 1 year total shareholder return of 21.6% points to momentum that has cooled rather than completely reversed as investors weigh these product launches against longer term cash flow and risk expectations.
Compare how United Parcel Service’s security-focused pivot stacks up against other logistics players by scanning our hand picked list of 31 resilient stocks with low risk scores screening for resilience rather than just headline momentum.
United Parcel Service now trades well below its recent highs while rolling out new security services into peak season. Does that reset offer a reasonable entry today, or does it argue for patience until sentiment and pricing settle further?
Most Popular Narrative: 18% Undervalued
United Parcel Service’s most followed valuation view pegs fair value at $115.81, which sits well above the recent close at $94.57 and frames the current price as a discount rather than a premium.
Expansion of automated facilities and RFID deployment, with 68.5% of U.S. volume now running through automated buildings where cost per piece is about 28% lower and hundreds of millions of manual scans removed through RFID, is expected to lower unit costs and support operating margin and cash flow.
See why 218 investors see United Parcel Service as 18% undervalued.
Result: Fair Value of $115.81 (UNDERVALUED)
Still, the United Parcel Service story can break if labor costs climb faster than automation savings, or if the rich dividend crowds out planned US$2b growth investments.
Find out about the key risks to this United Parcel Service narrative.
Another View On United Parcel Service’s Valuation
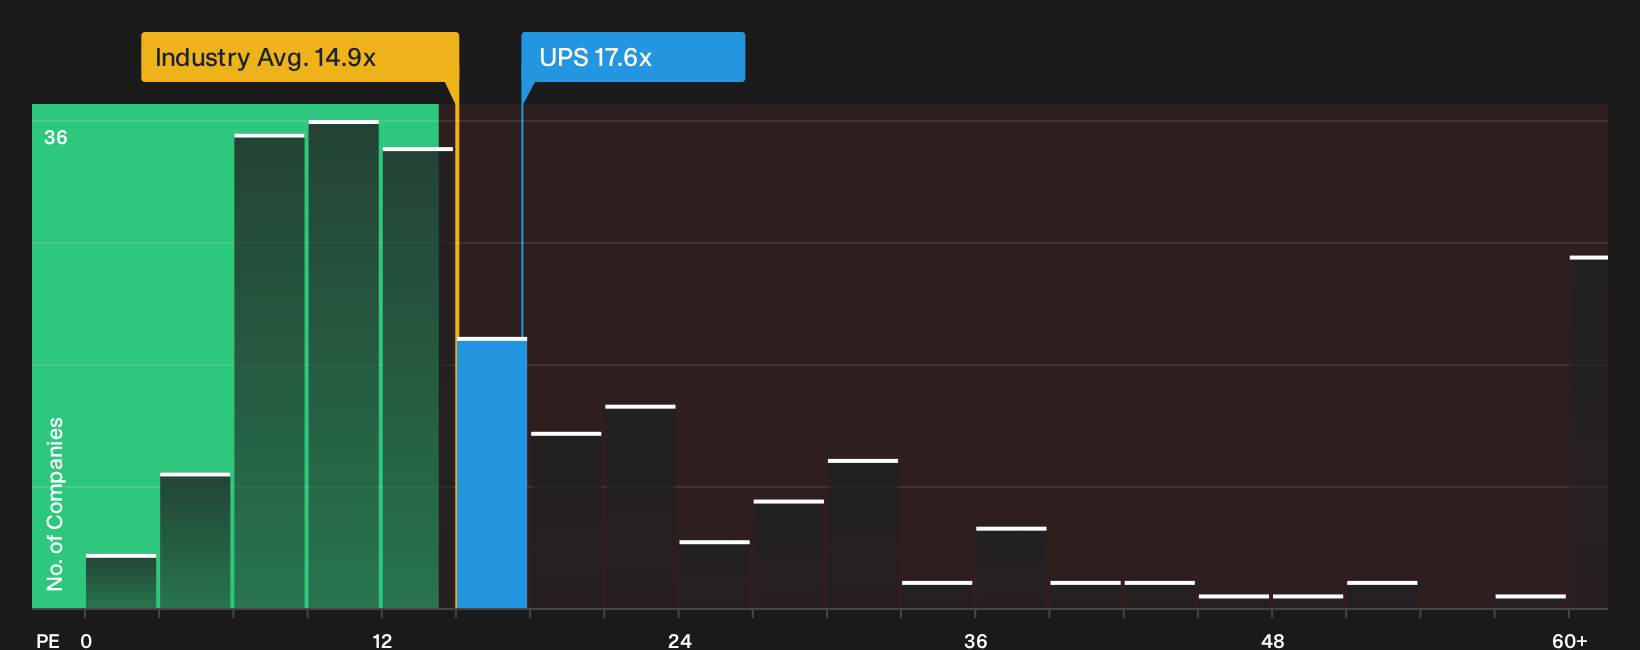
That $115.81 fair value comes from a narrative built on cash flow potential. A different lens focuses on what investors actually pay today. UPS trades on a P/E of 17.6x, richer than the global logistics average at 14.9x, yet below a fair ratio of 22.2x that the data suggests the market could move toward. Is that a sensible margin of safety or a signal that expectations are already demanding?
To see how this price tag compares with the earnings profile in more detail, including how that fair ratio is calculated, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The signals are mixed so far, right। If United Parcel Service appears both promising and risky to you, act quickly on your own research and carefully weigh the 3 key rewards and 3 important warning signs.
Looking for more United Parcel Service investment ideas?
Do not stop your research at United Parcel Service. Broaden your watchlist with fresh ideas that match how you like to balance risk, income, and upside.
- Target potential upside by scanning companies that combine quality fundamentals with attractive pricing using the 28 high quality undervalued stocks.
- Strengthen your income stream by reviewing stocks that feature reliable yields in the 8 dividend fortresses.
- Prioritise resilience by focusing on businesses with robust finances through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com