
Ørsted (CPSE:ORSTED) Starts Blackwater Solar Construction On A Valuation That Still Looks Cheap
Blackwater Solar construction puts Ørsted stock back in focus
Ørsted (CPSE:ORSTED) just broke ground on Blackwater Solar, a 200 MW project in Roosevelt County, New Mexico, its first development in the state and a fresh data point for investors.
For context, Ørsted’s share price is now DKK132.45, with a 1-day share price return of 2.24% after the Blackwater Solar update. However, the 90-day share price return is down 9.84% and the 5-year total shareholder return is down 72.15%, so recent momentum appears more like a short-term bounce than a sustained trend.
Scan beyond Ørsted and this single project update by sifting through a curated list of resilient infrastructure players in the 43 power grid technology and infrastructure stocks.
A near 48% intrinsic discount and almost 30% gap to analyst targets meet a business that just posted an annual net loss. Is the market being too cautious on Ørsted after this Blackwater Solar bounce, or not cautious enough?
Preferred multiple of 2.1x P/S: Is it justified?
On valuation terms, Ørsted looks inexpensive relative to peers, with a P/S ratio of 2.1x at a DKK132.45 share price. Our model-based fair value work points to a much higher level.
The P/S metric compares the market value of the equity to its DKK83,672m of trailing revenue. It focuses on what investors are paying for each unit of sales rather than profits, which matters because Ørsted is currently loss making with a net loss of DKK3,118m.
This low P/S ratio suggests the market is assigning a discounted tag to Ørsted’s existing revenue base, even though earnings are forecast in the data to grow 34.01% per year and analysts are in statistically tight agreement on a price target of DKK172.09, which is 29.9% above the current quote.
Compared with the European Renewable Energy industry average P/S of 2.3x and a peer group average of 12.4x, the stock trades on a clearly lower multiple. This indicates investors are pricing Ørsted’s sales far more conservatively than both its sector and its closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 2.1x (UNDERVALUED)
Still, Ørsted’s recent annual loss and the sharp 5-year total shareholder return decline suggest sentiment could sour again if cash generation or project execution disappoints.
Find out about the key risks to this Ørsted narrative.
Another view on Ørsted using the SWS DCF model
The previous section framed Ørsted as inexpensive on a 2.1x P/S multiple. Our DCF model presents a different perspective, with a future cash flow value of DKK252.70 per share versus the current DKK132.45 price, a 47.6% gap that indicates a very different risk reward profile.
That kind of discount can reflect genuine concern about execution and funding, or it can mark an overreaction that may take years to close. Look into how the SWS DCF model arrives at its fair value.
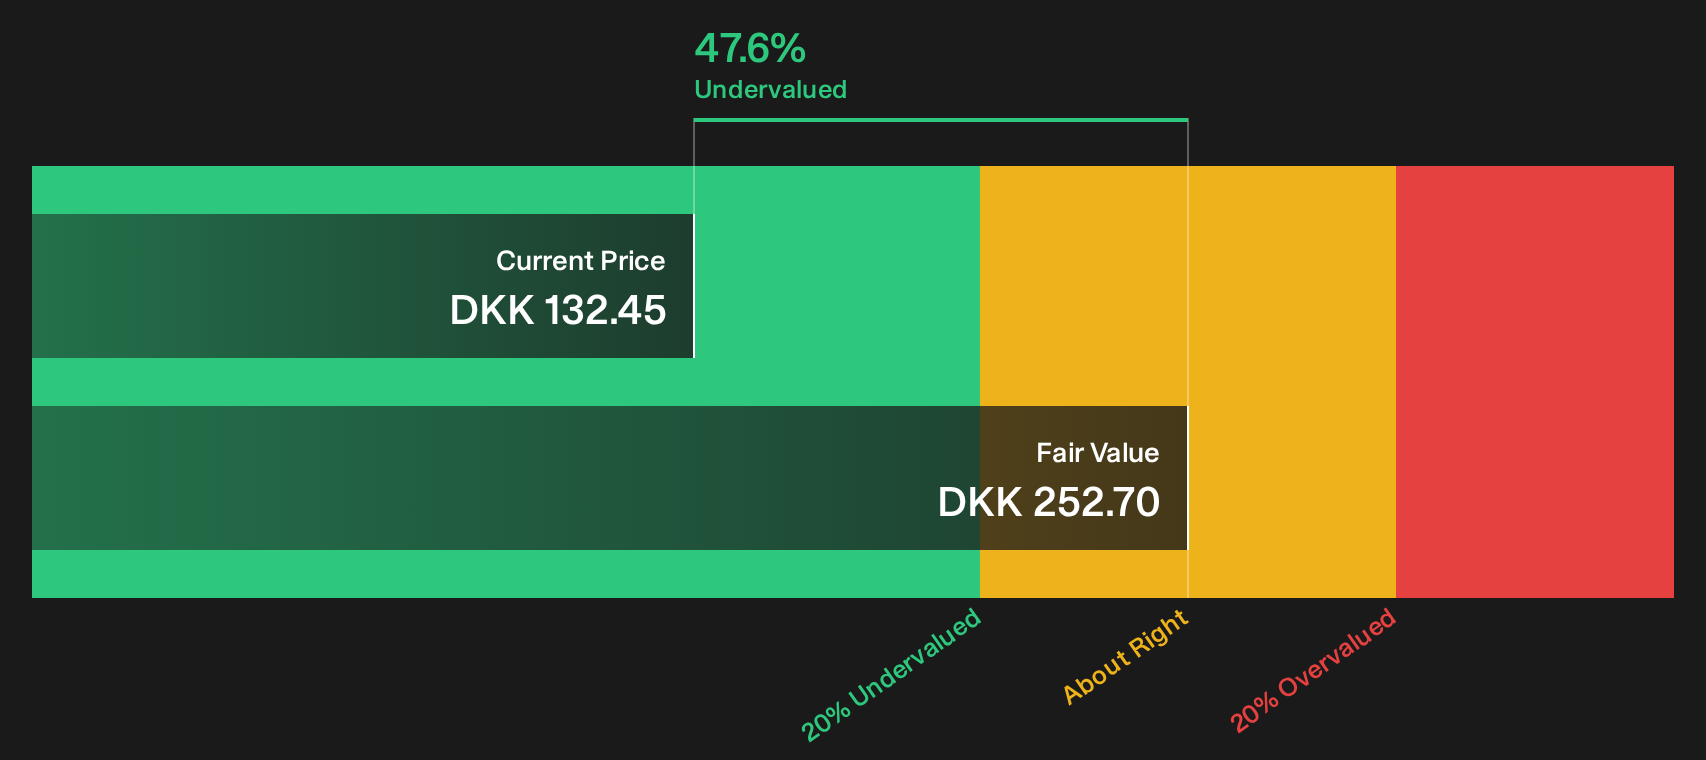
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ørsted for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ørsted so far. If this feels like a close call, move quickly to test the assumptions, pressure test the risks and weigh the 3 key rewards.
Looking for more Ørsted-sized investment ideas?
Do not stop your research with Ørsted. Broaden your watchlist using structured screeners that surface opportunities you might otherwise miss.
- Target potential mispricings by reviewing a focused set of quality companies that currently look out of favor in the 174 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for balance sheets that look built to handle stress through the list of solid balance sheet and fundamentals (204 results).
- Spot under-the-radar prospects before they hit the mainstream by scanning the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com