
Will Oil Supply Squeeze Change ExxonMobil Stock Narrative
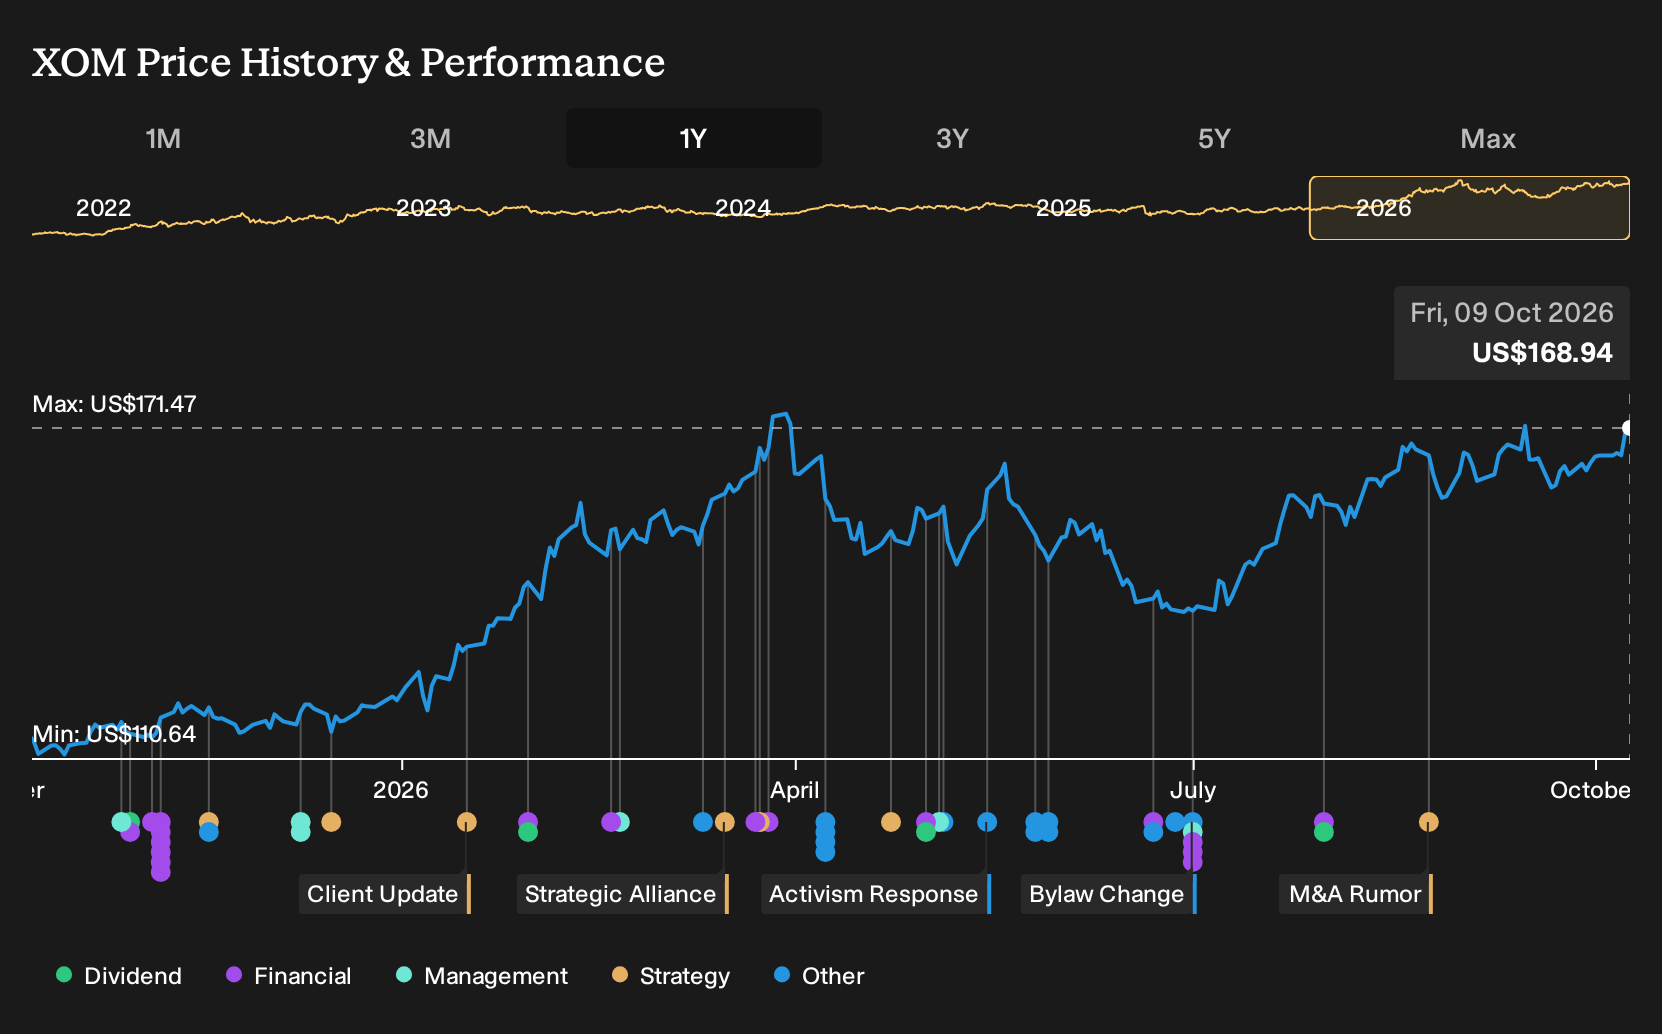
- ExxonMobil Holdings is reacting to a supply squeeze after a Gulf tanker attack and hurricane related shutdowns in the Gulf of Mexico lifted crude prices and supported stronger revenue expectations for integrated producers.
- The same supply shock hits ExxonMobil on multiple fronts at once, feeding into upstream pricing, refinery crack spreads, and cash flow sensitivity to short term commodity swings.
- This article examines how ExxonMobil's investment narrative interacts with the recent crude price spike triggered by supply disruptions.
Scan how ExxonMobil Holdings stacks up against other integrated producers by checking out the hand-picked 43 power grid technology and infrastructure stocks riding the same supply and pricing shocks shaping today’s energy trade.
ExxonMobil Holdings Investment Narrative Recap
To own ExxonMobil Holdings, you need to believe the integrated model, from Permian and Guyana barrels to refining and chemicals, can keep turning a volatile commodity stream into steady cash generation. The recent crude price spike from the Gulf disruptions mostly reinforces that story in the near term, but the key short term catalyst remains execution on high return upstream projects and cost savings.
The biggest operational risk right now is that oil and gas demand or regulations tighten faster than the project slate and early low carbon bets can adapt, which could pressure margins. The latest supply shock moves the needle on quarterly earnings sensitivity, but it does not materially change that broader risk reward equation.
Among recent developments, the progress in Guyana is most relevant. Guyana has already recovered about US$55b of investment and operating costs almost two years ahead of schedule, and upstream volumes outside the Middle East are at a multi decade high. For a shareholder watching this crude spike, the question is how efficiently ExxonMobil can keep bringing those lower cost barrels into the system.
That early payback, together with structural savings of US$16.3b since 2019 and a target of at least US$20b by 2030, frames the catalyst investors are really tracking. Supply shocks may swing quarterly results, but the medium term story depends on whether ExxonMobil can keep costs flat, stick to disciplined capex and convert Guyana and Permian output into durable free cash flow despite commodity volatility.
ExxonMobil Holdings' current analyst narrative points to revenues of US$373.7b and earnings of US$45.7b by 2029. That profile assumes 1.2% yearly revenue growth and an earnings increase of about US$12.9b from US$32.8b today.
Uncover why ExxonMobil Holdings' fair value indicates that ExxonMobil Holdings is in line with its current price.
Exploring Other Perspectives
Some of the most optimistic ExxonMobil analysts lean hard into regulatory relief as a swing factor. Before this Gulf supply shock, the bullish cohort was already penciling in US$508.7b of revenue and US$55.2b of earnings by 2029. You can see how a fresh, supply-driven price spike could push those optimistic views even further or prompt a rethink, so it is worth exploring a range of expectations rather than anchoring on one forecast set.
Explore 5 other ExxonMobil Holdings fair value estimates, including one that suggests there may be as much as 15% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ExxonMobil Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ExxonMobil Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExxonMobil Holdings' overall financial health at a glance.
Looking for more ExxonMobil Holdings style investment ideas?
Once you have formed a view on ExxonMobil Holdings, it can help to line it up against other opportunities using the Simply Wall St Screener so you can see where the risk, income and quality profiles differ.
- For investors who care most about resilient balance sheets and fundamentals, start with a curated list of solid balance sheet and fundamentals (25 results) that can help you focus on financially sturdier businesses.
- If you are hunting for mispriced opportunities, use the hand picked 20 high quality undiscovered gems to surface lesser known stocks with strong underlying metrics.
- Income focused readers who want steadier cash returns can scan a targeted 8 dividend fortresses built around higher yielding dividend payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com