
The pre-increase in subsidiary performance by 190 times fueled investment sentiment. Is Dongyue Group (00189) looking forward to an inflection point?
Dongyue Group (00189), whose stock price has experienced a round of roller coasters, seems to have seen a hint of steady bottoming out. Zhitong Finance noticed that on October 9, Dongyue Group changed its declining performance in recent months and fluctuated upward throughout the day, hitting an intraday high of HK$11.1, closing at HK$10.99, an increase of 3.29%. In the end, it traded HK$240 million on the same day. The volume increased compared to the previous period. According to the news, Dongyue Group revealed on the evening of October 8 that Dongyue Silicon, its non-wholly-owned subsidiary, released a performance forecast for the first three quarters of 2026. Dongyue Silicon expects to achieve net profit attributable to shareholders of listed companies of 547 million yuan to 567 million yuan in the first three quarters. Net profit for the same period last year was 2,8567 million yuan, an increase of more than 190 times over the previous year.
Stimulated by the above news, Dongyue Silicon's stock price opened high on the 9th, and closed the stock market soon after opening. Driven by this, Dongyue Group's stock price also followed the rise. It is worth mentioning that if you look at it over a long period of time, Dongyue Group's stock price trend this year has been tortuous. Since starting at a low point at the beginning of the year, the stock once hit a high of HK$23.74 in late June due to the rising refrigerant boom, implementation of quota policies, and a high overall market trend. The biggest increase during this period was more than 1.3 times. However, since then, the stock price has turned downward. In July, it fell by more than 40% in a single month, and the cumulative retracement has exceeded 50% so far, almost equalizing the entire increase during the year. The clock is set to October. After the previous round of sharp decline, has Dongyue Group's stock price fully absorbed pessimistic expectations? Looking ahead to the future market, will the subsidiary's performance far exceeding expectations help reverse Dongyue Group's stock price decline?
Is the pre-increase in profits of subsidiaries over 190 times fueling investment sentiment?
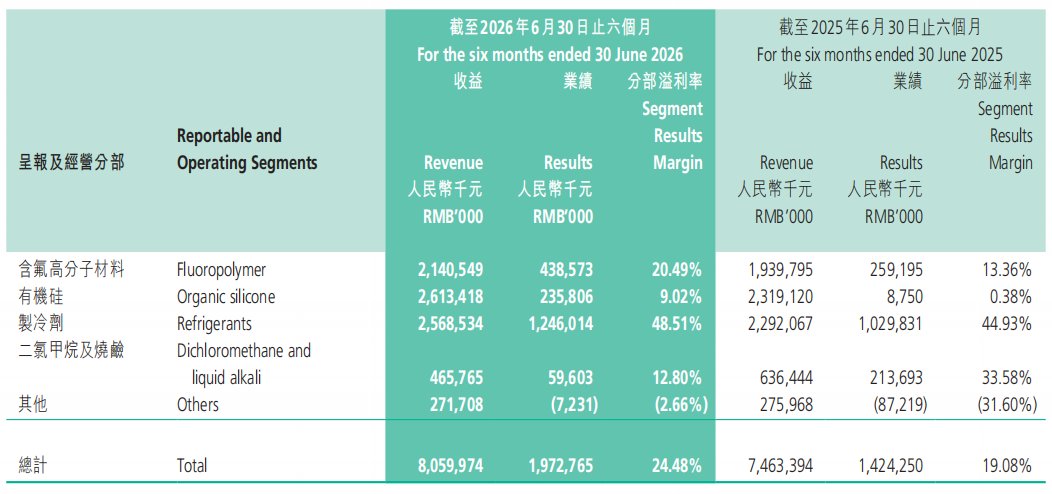
The direct catalyst for this change in Dongyue Group's stock price comes from the performance forecast of its subsidiary Dongyue Silicon. According to the announcement, Dongyue Silicon's net profit for the first three quarters of 2026 increased by more than 190 times year-on-year. Compared with last year's performance of hovering near the break-even line, it can be said that it has experienced qualitative changes. Judging from the relationship between the two, Dongyue Silicon is the core operator of Dongyue Group's silicone sector, so it is self-evident that this high-gold performance is guiding the overall performance of Dongyue Group. Looking back at Dongyue Group's semi-annual report, the silicone business revenue for the first half of the year was 2,613 billion yuan, up 12.7% year on year; segment profit was 236 million yuan, a significant improvement over 8.75 million yuan in the same period last year, and the division's net profit margin was restored from 0.38% to 9.02%. This Q3 forecast further confirms the sustainability of the improvement in the supply and demand pattern of the silicone industry. At this stage, the overall market has limited short-term new capacity investment, downstream demand is growing steadily, DMC prices have rebounded from the bottom, and the industry is experiencing a round of recovery driven by supply contraction.
However, back on the market, Dongyue Group's stock price had previously been trading sideways around HK$11 for many days, rising on the 9th. This is probably an attempt by capital to build a short-term bottom. However, it goes without saying that at present, Dongyue Group's stock price is still suppressed by the 5th, 10th, and 20th EMAs. The EMA system has not yet formed a bullish arrangement, and the trend reversal still requires more signals to confirm. However, considering that Dongyue Group's stock price has retreated more than 50% from its high point, almost all of its gains during the year, pessimistic expectations have at least partially been digested, so from a technical perspective, the possibility that the company's stock price will drop further in the future may be relatively low.
When will value revaluation under multiple catalysis come?
Dongyue Silicon's promising performance provided a direct catalyst for Dongyue Group's rebound on the 9th. However, if we take our eyes off the profit jump of subsidiary companies and re-examine the industrial cycle and valuation coordinates of the Dongyue Group, we may be able to more clearly understand the changes this fluorosilicone faucet is experiencing.
Refrigerants remain a key clue to grasping changes in fundamentals. Since the third quarter, the overall price of mainstream refrigerants has been rising steadily, and the price of Changxie increased further by 500 yuan/ton in the fourth quarter. As far as Dongyue Group is concerned, the company's basic market under the quota system is still stable, with the largest R22 quota in China and the top R32 quota. As the R32 project reaches production, it is expected that the problem of underutilization of quotas due to the installation adaptation period will gradually be alleviated, and the profit stability of the refrigerant sector will continue to increase.
In the fluoropolymer sector, market news shows that Nvidia's next-generation Rubin Ultra platform is evaluating the introduction of PTFE materials in switch boards. Due to its extremely low dielectric loss, this material is regarded as a key candidate for M10 grade high-frequency PCB core resins. Currently, the localization rate of high-end electronic-grade modified PTFE is less than 5%, and the core market has long been dominated by overseas companies. Dongyue Group has previously made it clear that the unused funds raised will be used for the PTFE ultra-high purity quality improvement project. If it can obtain a substantial share in the AI computing power hardware material upgrade, its contribution to the group's overall valuation may also be very impressive.
Additionally, it is worth mentioning that Shandong Dongyue Future Hydrogen Energy Materials Co., Ltd., a subsidiary of Dongyue Group, has submitted guidance and filing. This is the fourth time that the company has impacted its IPO. According to reports, the company is mainly engaged in the development and sale of high-performance fluorine-containing functional films and key materials, and has formed a collaboration with Dongyue Group in the fluorine-containing industry chain. If successfully listed, Dongyue's asset value in the field of new fluorine-containing materials is expected to be re-evaluated.
Back at the valuation level, Dongyue Group's current dynamic price-earnings ratio is around 8 times, which is at a historically low level. It is certainly reasonable for the market to undervalue it. After all, fluctuating chemical prices, management complexity brought about by diversification of business, combined with the liquidity discount of Hong Kong stocks, all of these are objective suppressing factors. However, at the current time point, the profit stability of refrigerants continues to increase under the quota system. Silicone has completed bottom restoration, and fluoropolymers have the potential to be realized. If the market still uses the framework of strong cycle chemical stocks to price Dongyue Group, there may be differences in expectations in the middle.
Taken together, the strong expectations for Dongyue Silicon's performance provided strong evidence for the improvement in the profits of Dongyue Group's silicone sector, and also mitigated the market's pessimistic expectations about the company's fundamentals to a certain extent. However, the single-day volume rebound is not enough to confirm a trend reversal. In the future, it is still necessary to observe whether Dongyue Group's trading volume can continue to expand and whether the stock price can effectively stabilize above the short-term moving average. Overall, however, at a time when there are negative factors or full pricing, the author believes that investors at this stage may have more optimistic expectations for Dongyue Group's future market.