
Singapore Exchange (SGX:S68) Could Be 14% Undervalued On Its Push Beyond Equities
Singapore Exchange (SGX:S68) is drawing fresh attention as its push into FX, commodities and crypto futures gains traction, widening its role beyond traditional equity trading for investors watching multi asset risk management.
Recent trading tells a mixed story. After a 16.3% decline in the 30 day share price return and a 14.5% drop over 90 days, Singapore Exchange still carries a 21.6% year to date share price return and a 5 year total shareholder return of 149.8%. This indicates that longer term momentum remains intact even as shorter term sentiment cools around its expansion into FX, commodities and crypto futures.
Scan a curated set of exchanges and financial infrastructure plays that reflect Singapore Exchange's multi asset expansion by checking out the list of solid balance sheet and fundamentals (204 results).
So is the recent pullback in Singapore Exchange mainly a reset in sentiment after a strong multi year run, or a signal that the underlying business is mispriced? It is time to test that against the current valuation.
Most Popular Narrative: 14% Undervalued
Against a last close of SGD20.73, the most followed narrative pegs Singapore Exchange's fair value at SGD24.15, pointing to a valuation gap that rests on its multi asset build out and capital markets role rather than short term sentiment.
The exchange's multi-asset strategy, expanding into FX, commodities, and new products like crypto perpetual futures and tailored index products, reduces its reliance on traditional equities and positions SGX to capture demand from Asia's growing wealth and the diversification needs of global investors, supporting both revenue and EBITDA growth. Digital product development, technology modernization, and enhancements like the T+1 trading session, proprietary trading workflows, and cross-selling opportunities are strengthening SGX's competitive edge, improving operating leverage, and expected to drive recurring earnings.
See why 35 investors see Singapore Exchange as 14% undervalued.
Result: Fair Value of SGD24.15 (UNDERVALUED)
Still, two pressure points could upset this story: tougher competition from larger regional and alternative venues, and heavier regulatory and technology costs that squeeze SGX's profitability.
Find out about the key risks to this Singapore Exchange narrative.
Another Take On Singapore Exchange’s Valuation
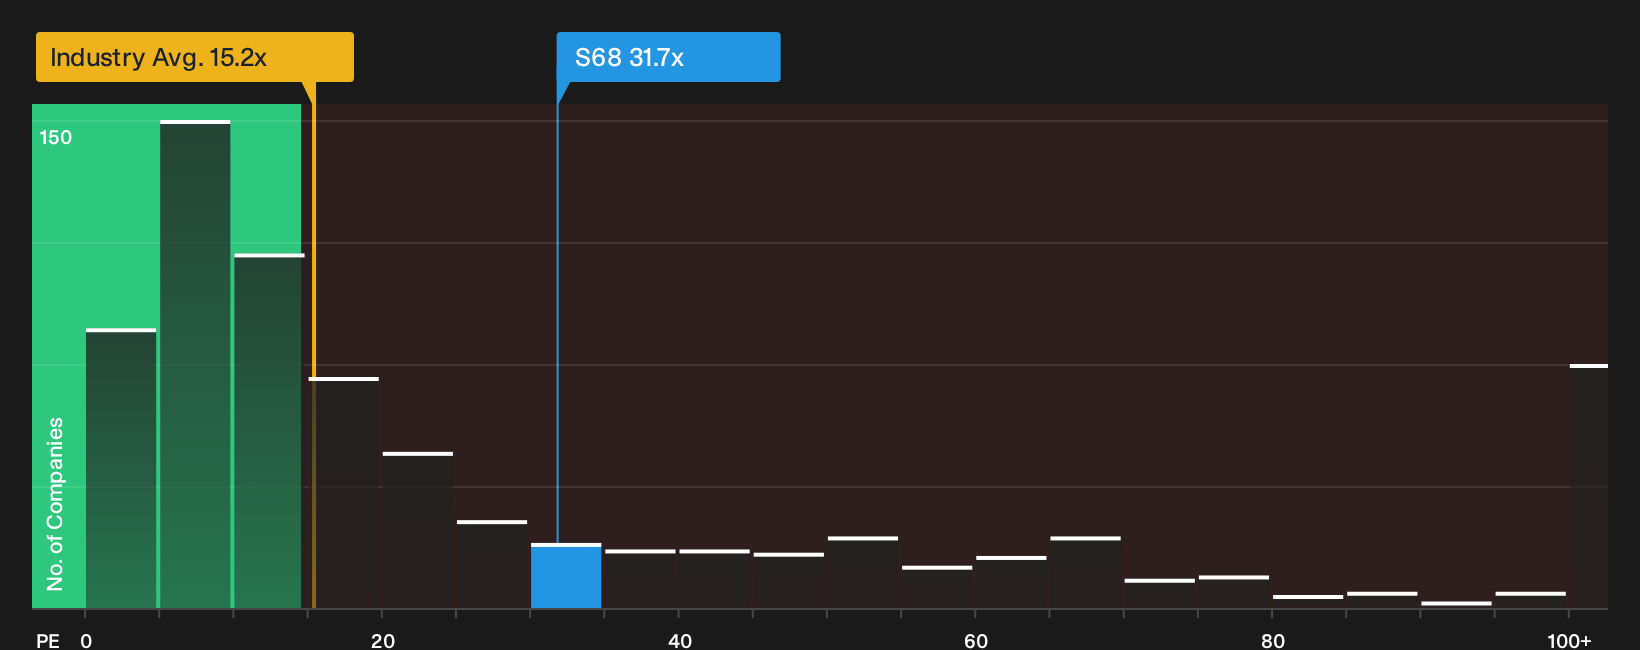
The narrative points to Singapore Exchange trading 14% below a fair value of SGD24.15. Yet on earnings, the picture is flipped. The stock trades on a P/E of 31.7x, while peers average 20.3x and the fair ratio sits at 20.9x. That premium raises a simple question: Is the story strong enough to justify paying so far above both peers and the fair ratio?
For a clearer sense of how that earnings multiple stacks up against alternatives, take a look at the valuation breakdown built around this ratio, including where the market could move if pricing drifts closer to the fair ratio, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and concern around Singapore Exchange leaves you uncertain, take a closer look at the underlying data now and compare the narrative with your own expectations. To see what those bright spots are that investors are focusing on, start with the 3 key rewards.
Looking for more investment ideas beyond Singapore Exchange?
Do not stop with Singapore Exchange. Broaden your watchlist now with focused stock ideas filtered by quality, value and resilience so you are not leaving opportunities on the table.
- Target resilient compounding potential by scanning a 222 resilient stocks with low risk scores that filters for businesses with sturdier risk profiles.
- Hunt for mispriced quality using a curated 618 high quality undiscovered gems that highlights strong fundamentals the wider market may be overlooking.
- Sharpen your income game by zeroing in on a 223 dividend fortresses designed to surface higher yield opportunities with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com