
Fukuyama Transporting (TSE:9075) Looks Pricey As Security Sale Gain Meets 13.9x P/E
Fukuyama Transporting (TSE:9075) has drawn attention after its 6 October 2026 board meeting, where directors discussed an expected gain from selling investment securities and how that one off profit could feed into upcoming results.
That boardroom update lands on a stock that has already been in motion, with Fukuyama Transporting’s share price up 36.47% year to date and its one-year total shareholder return at 62.93%. This points to momentum that recent corporate actions may be reinforcing rather than creating from scratch.
Capitalize on the momentum around Fukuyama Transporting by scanning a curated 12 high quality undervalued stocks that combine strong balance sheets with cash flows that support one off gains more sustainably.After a 62.93% one year return and a fresh one off gain on investment securities in the mix, the real call now is simple: pay up at today’s ¥6,100 or wait for valuation to cool.
Preferred P/E of 13.9x: Is it justified for Fukuyama Transporting?
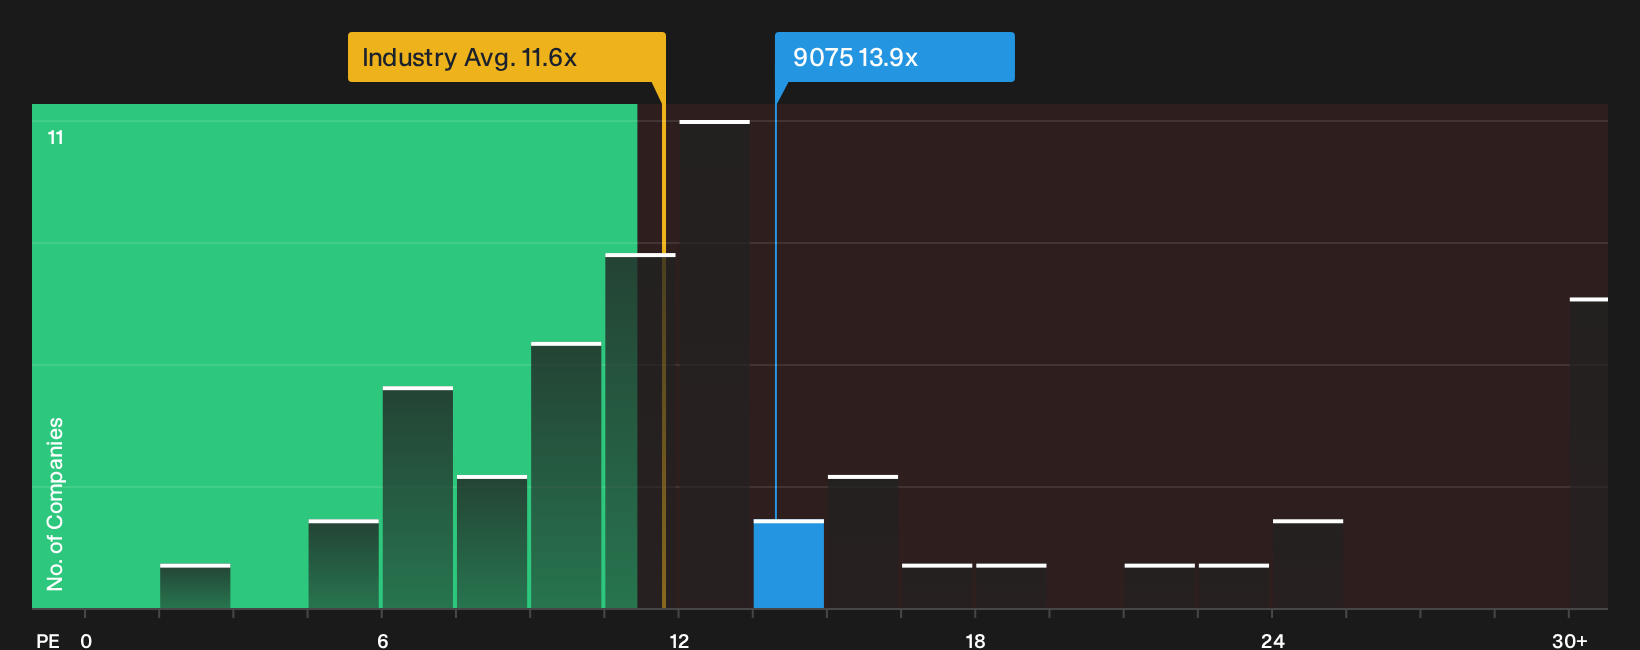
On valuation, Fukuyama Transporting trades on a P/E of 13.9x, which screens as good value against its direct peers at 18.6x but looks more demanding than the broader JP Transportation industry at 11.6x.
The P/E ratio compares the current share price with earnings per share. For a logistics group like Fukuyama Transporting, where investors often focus on steady cash generation rather than rapid expansion, P/E can give a quick sense of how much the market is paying for each unit of profit.
Here the market is assigning a lower P/E than the peer average. This suggests investors are paying less for each yen of earnings than for similar stocks. At the same time, the multiple is above both the industry average and the estimated fair P/E of 11.9x. This signals that the current pricing is richer than the level the market could eventually move toward if sentiment cools.
Compared with the rest of the JP Transportation industry, the 13.9x P/E is firmly higher than the 11.6x sector average, indicating a premium tag relative to many listed transport operators rather than a discount.
Explore the SWS fair ratio for Fukuyama Transporting.
Result: Preferred multiple of price-to-earnings of 13.9x (OVERVALUED)
Still, Fukuyama Transporting’s reliance on one off security gains and its P/E premium to the wider JP Transportation group could quickly look exposed if earnings disappoint or sentiment fades.
Find out about the key risks to this Fukuyama Transporting narrative.
Another take on Fukuyama Transporting’s value
The P/E view paints Fukuyama Transporting as richer than its 11.6x industry average, yet cheaper than peers at 18.6x and above a fair ratio of 11.9x. That gap points to real valuation risk if sentiment softens. Is this price stretching the elastic or simply reflecting recent enthusiasm?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fukuyama Transporting for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Fukuyama Transporting’s risks and rewards can make the picture feel murky at first glance, so move quickly, review the underlying data, and decide what really matters to you by weighing the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Fukuyama Transporting?
If Fukuyama Transporting has sharpened your focus on valuation and momentum, broaden your watchlist now so you are not relying on a single story.
- Target potential mispricings by scanning a hand picked 74 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise resilience with a 23 resilient stocks with low risk scores so you can focus on businesses where risk scores stay in a tighter range.
- Strengthen your long term income plan through a 28 dividend fortresses built around higher yield payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com