
MedinCell (ENXTPA:MEDCL) Jumped, But What Is Drawing Fresh Attention?
MedinCell (ENXTPA:MEDCL) is back in focus after the U.S. FDA approved WELTRUZA™ (olanzapine). Management has called a special meeting for investors to unpack what this new schizophrenia treatment could mean.
The sharp 1-day share price return of 16.89%, building on a 7-day move of 30.90% and a 30-day share price return of 31.97%, suggests investors are rapidly repricing MedinCell after the WELTRUZA™ approval. At the same time, the 3-year total shareholder return of very large multiples of the initial investment points to a story that has been developing over a much longer period.
Spot opportunities around MedinCell by scanning a curated 618 high quality undiscovered gems that are also building high-conviction stories off regulatory milestones and under-the-radar product pipelines.MedinCell now has a high-profile schizophrenia franchise and a share price that has sprinted ahead in days. Does the current valuation still reflect the fundamentals, or has enthusiasm already priced in much of the story?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, MedinCell’s fair value sits at €35.07 against the latest close of €29.06. This puts the recent FDA excitement alongside a longer running valuation story that is grounded in forecasts for growth, profitability and risk.
MedinCell's financial performance is currently reliant on the successful commercialization and continued growth of just two products, UZEDY and Olanzapine LAI, making it vulnerable to clinical, regulatory, or competitive setbacks in either. Any delays or failures would significantly impact future revenue and net earnings. The company's future profitability is predicated on timely regulatory approvals (especially for Olanzapine LAI in 2026 and broader UZEDY indications), but any increase in regulatory rigor or unexpected demands for additional studies could delay launches and defer revenue generation.
See why 6 investors see MedinCell as 17% undervalued.
Result: Fair Value of €35.07 (UNDERVALUED)
Still, the MedinCell story leans heavily on UZEDY and Olanzapine LAI, so any regulatory delay or partnership setback could quickly challenge the current fair value narrative.
Find out about the key risks to this MedinCell narrative.
Another View: MedinCell Through A Sales Multiple Lens
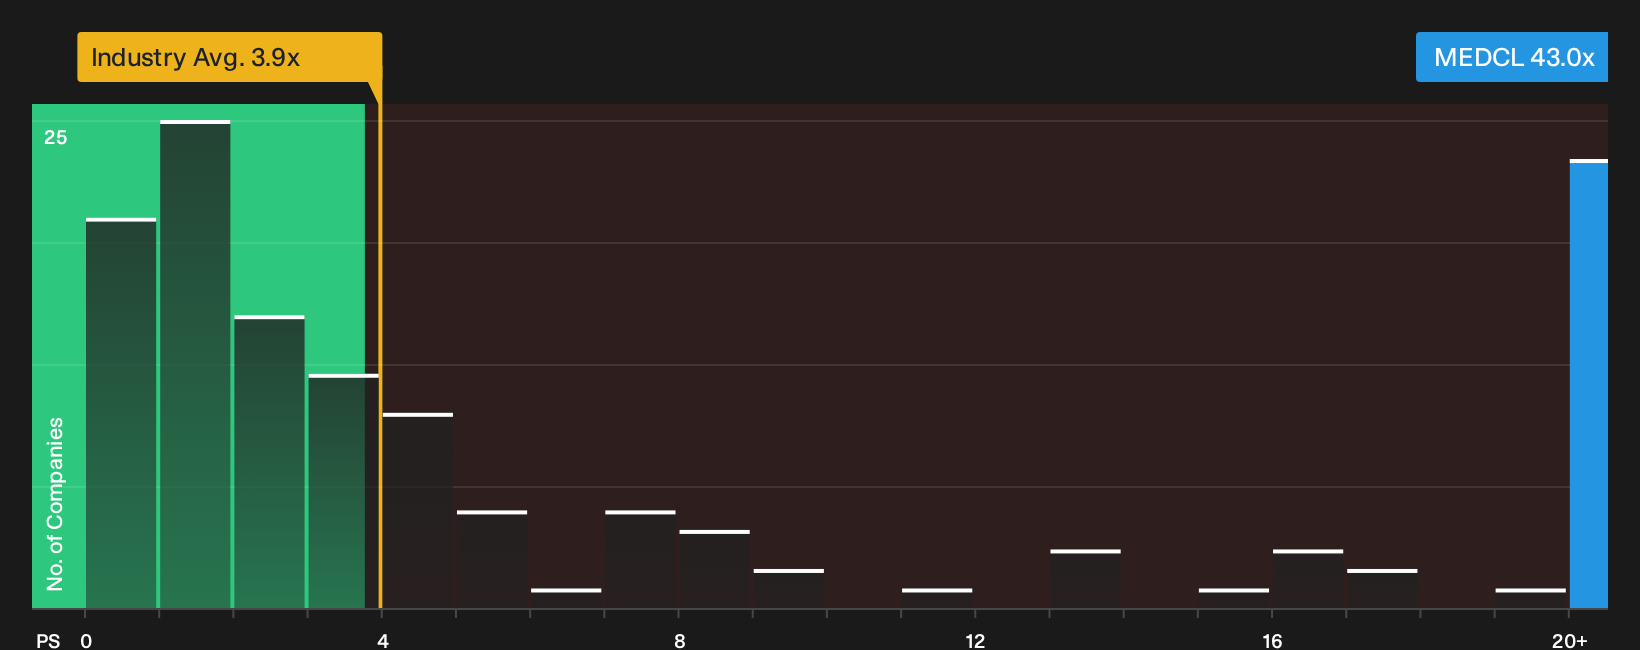
Our DCF work suggests MedinCell trades at a large discount to estimated future cash flows, yet the current P/S ratio of 43x is far above the European pharmaceuticals average of 3.9x and a fair ratio of 8.7x. That gap points to meaningful valuation risk if sentiment turns.
To see how that gap is built from the bottom up, including where the fair ratio could shift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far, with MedinCell carrying both clear risks and real upside. Review the situation while the story is fresh and stress test the 3 key rewards and 1 important warning sign.
Looking for more MedinCell style opportunities?
If you like how MedinCell’s story is unfolding, do not stop here. Use focused screens to uncover other ideas before the crowd pays attention.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (204 results) that filters for companies pairing funding strength with underlying business quality.
- Zero in on potential value by reviewing a 175 high quality undervalued stocks that highlights stocks where fundamentals and price appear out of sync.
- Lean into stability and income by checking a 223 dividend fortresses that focuses on higher yielding companies with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com