
Why Dell Stock Is Worth Buying Before It Touches $735
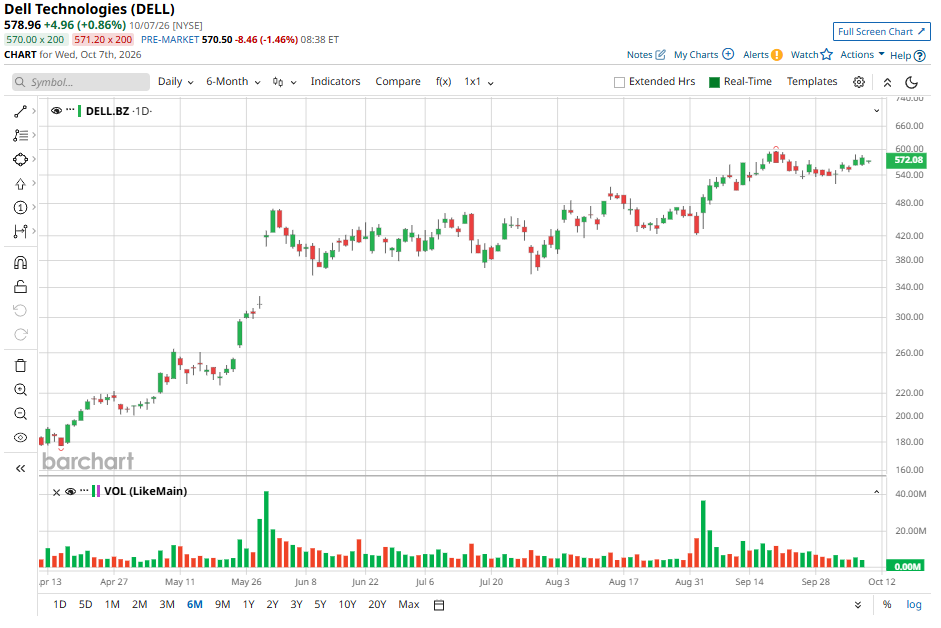
Dell Technologies (DELL) has been one of the strongest performers among top technology stocks, with shares climbing 366% year-to-date (YTD). The surge reflects rising demand for artificial intelligence (AI) infrastructure, particularly AI servers, along with increased enterprise investment in IT upgrades, data storage, and infrastructure modernization.
Despite DELL stock’s remarkable gains, Dell could still have room to advance further. Management’s latest guidance indicates that the company expects earnings to continue expanding rapidly in the coming periods, while demand across key product categories remains solid. Its improving financial performance, driven by sustained demand, could further support the stock, suggesting the recent rally may not be over yet.
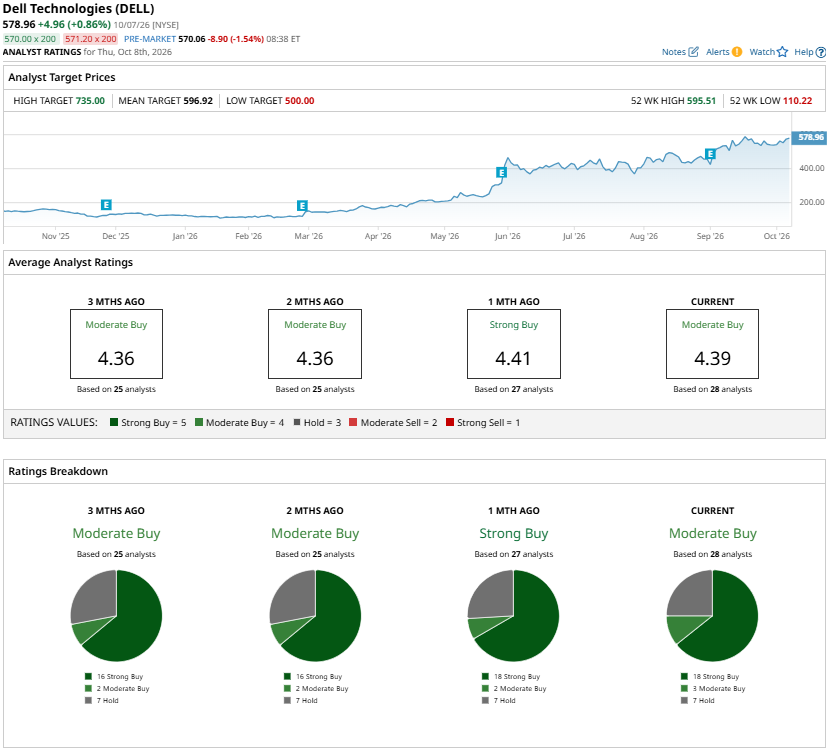
Wall Street’s highest price target for Dell is currently $735. With shares closing at $586.06 on Oct. 9, reaching that target would imply approximately 25% additional upside from here.
What could drive Dell Technologies stock higher from here? There are several factors worth examining.
Dell to Grow Earnings at Exceptional Pace
Dell is positioned for robust earnings growth, which could provide further support to its stock price. In the second quarter, revenue reached $47 billion, up 58% year-over-year (YOY). At the same time, non-GAAP diluted EPS surged 203% to $7.04. Strong operating efficiency is helping Dell expand profits faster than revenue.
Dell closed the quarter with an AI-related backlog of $95 billion and booked $60.9 billion in AI orders. Its pipeline continued to grow sequentially and remains several times larger than the current backlog. Over the last 12 months, Dell has converted $131.7 billion in backlog into orders.
The company's customer base is also becoming more diverse, with demand coming from neocloud providers, sovereign customers, and large enterprises. This expands Dell's addressable market and supports further growth.
Demand for traditional servers has also strengthened considerably, with category revenue up 122% YOY. Existing customers upgrading and modernizing their data centers drove much of this increase. Companies are investing in infrastructure to support traditional workloads while improving security, resilience, and performance. Meanwhile, AI and agentic workloads are generating additional demand for conventional CPU-based systems.
Dell’s storage segment also returned to growth, increased its market share, and improved profitability. Rising demand from AI applications is expected to drive its storage revenue.
The firm expects momentum to accelerate in the second half. For Q3, Dell projected revenue of $49 billion at the midpoint, representing about 81% YOY growth. Infrastructure Solutions Group (ISG) revenue is expected to increase by roughly 145%, supported by $19 billion in AI server revenue, while Client Solutions Group (CSG) revenue is projected to rise about 15%.
Dell’s operating expenses are expected to decrease by low-single digits sequentially, while operating income is forecast to climb by about 120%. Adjusted EPS is also expected to reach $6.50, up more than 150%.
Dell also raised its full-year revenue forecast by $25 billion to $192 billion at the midpoint, implying approximately 70% YOY growth. Adjusted EPS for the full year is now expected to reach $25.50 per share, up 150% YOY.
Analysts remain optimistic, forecasting earnings growth of 172% in fiscal 2027, and continued double-digit bottom-line growth thereafter.
The Valuation Supports Further Upside in DELL Stock
Although Dell stock has already posted massive gains, its valuation doesn’t look stretched. At 23 times, its forward price-to-earnings (P/E) ratio remains reasonable given the company’s solid expected earnings growth ahead.
This relatively moderate valuation and high growth suggest that DELL stock has additional upside ahead.
Should You Buy Dell Stock Now?
Analysts maintain a consensus “Moderate Buy” rating on DELL stock following the sharp rally. However, Dell’s strong earnings growth, record AI infrastructure demand, and expanding backlog support further gains.
With fiscal 2027 earnings expected to grow sharply and Dell stock trading at 23 times forward earnings, Dell’s valuation remains relatively reasonable compared with its growth prospects. Wall Street’s highest price target of $735 represents roughly 25% potential upside from current levels, making the stock attractive before it touches that milestone.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.