
Nike (NKE) Trimmed China Sales Disclosure In Its Latest 10Q
- Nike (NYSE:NKE) used its latest 10Q to scale back regional sales detail, including a narrower breakout for Greater China.
- The filing reduced disclosure on comparable store sales, limiting visibility into store performance across key geographies.
- Analysts have flagged the slimmer China reporting as a transparency setback, given existing scrutiny on the brand's performance there.
- The cutback in China and regional sales disclosure is only one piece of what investors need to weigh in this filing. We have also flagged 2 other big wins for NIKE.
For more ideas in this corner of the market, explore companies that return cash to shareholders through regular payouts via 8 dividend fortresses.
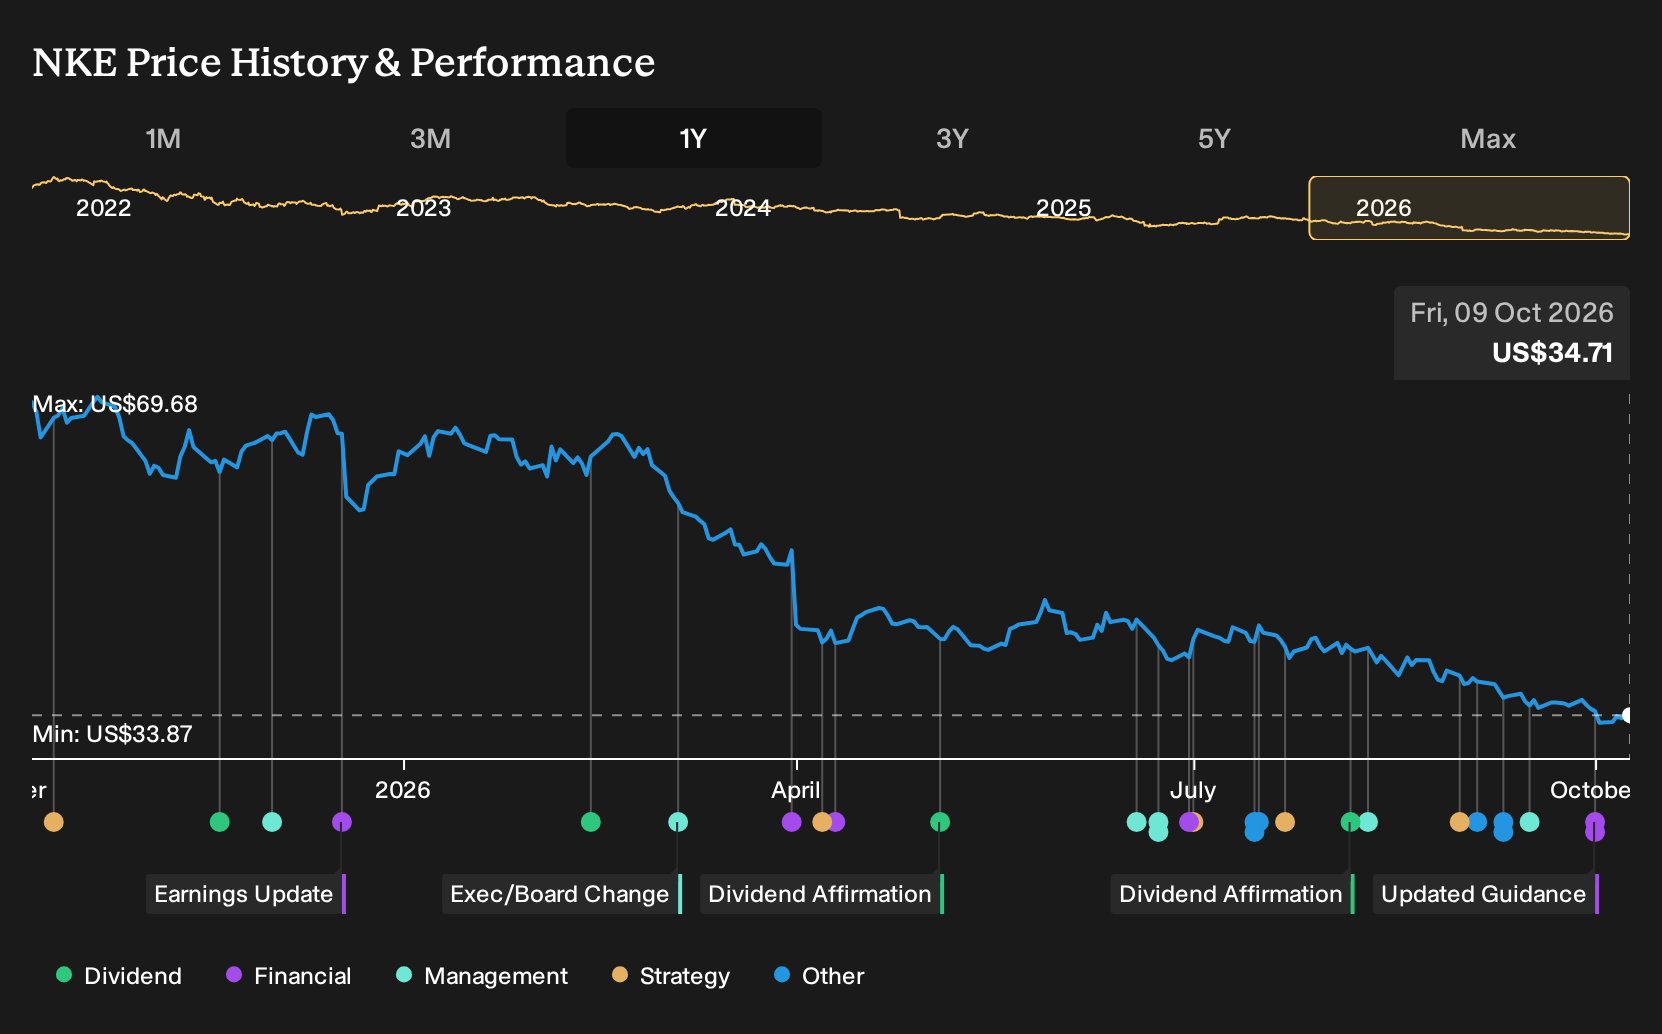
Nike operates as a global athletic footwear and apparel business across North America, Europe, the Middle East, Africa, Greater China, the Asia Pacific, and Latin America, so any change in how it reports regional trends affects how you gauge where this US$51.6b player is strongest or most exposed.
See how NIKE's balance sheet measures up.
Why does Nike’s reduced China disclosure matter if the headline financials are still available?
You still see total sales, net income and EPS, but you lose some of the granularity that helped separate Greater China trends from the rest of Asia or specific store formats. That makes it harder to link a 26% China revenue drop and planned high single digit revenue decline in fiscal 2027 to how different channels or cities are really performing. For you, it means more guesswork when judging whether the clean up in China is stabilising or still worsening underneath the consolidated line.
Does this change the Nike Narrative investors have been using to frame the reset?
The Narrative leans on a product pivot toward sport performance, tighter digital discounts and inventory clean up to support modest revenue growth and slightly better margins over time. Thinner regional disclosure pulls some colour away from key risks flagged there, including revenue pressure in Greater China, high inventories and the impact of fewer promotional days on digital traffic. The story still hinges on those same levers, but you now get less official visibility into how quickly the China clean up and channel shift are tracking against those assumptions.
See how these catalysts shape NIKE's path to a $45.63 fair value.
What should you watch next to judge whether this disclosure shift really matters for Nike?
Focus on the next couple of quarterly 10Q filings and earnings calls to see if management offers alternative indicators for China, such as qualitative commentary on digital sell through, wholesale orders or inventory in that region. Cross check those updates against any continued high single digit revenue decline guidance for fiscal 2027. If detail stays slim while top line pressure in China persists, the information gap around one of Nike’s most scrutinised markets will have effectively widened rather than just been repackaged.
The big Nike question news headlines skip
All the quarterly noise still leaves one gap for you as a shareholder: what a disciplined estimate of the whole business is worth when you only run the math on its future cash generation. Find out exactly what NIKE is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com