
Is ERG (BIT:ERG) Overvalued Even With New Contracted Revenue?
ERG has delivered a 3 year gain of 11.1%, yet the real question for you today is whether that share price still lines up with what the business earns. Recent news around fresh power purchase agreements adds more contracted revenue to the story, which brings the focus squarely onto the value the market is placing on those earnings.
- An 11.1% return over 3 years means long term holders have seen progress, so the issue now is whether that performance already reflects the earning power of ERG.
- The new five year power purchase agreement with Glencore covering Polish wind farms adds visibility to future cash inflows, which can influence how investors think about the durability and quality of ERG's profits.
- There is a second opinion on ERG worth weighing. See what analysts think ERG's shares could be worth.
The stock's next move may depend on whether ERG's current price can be fully explained by its earnings profile today.
If you are weighing ERG against other renewable-focused opportunities, it can help to compare it with a wider set of power and grid players using the 43 power grid technology and infrastructure stocks.
Has ERG Run Too Far on Earnings?
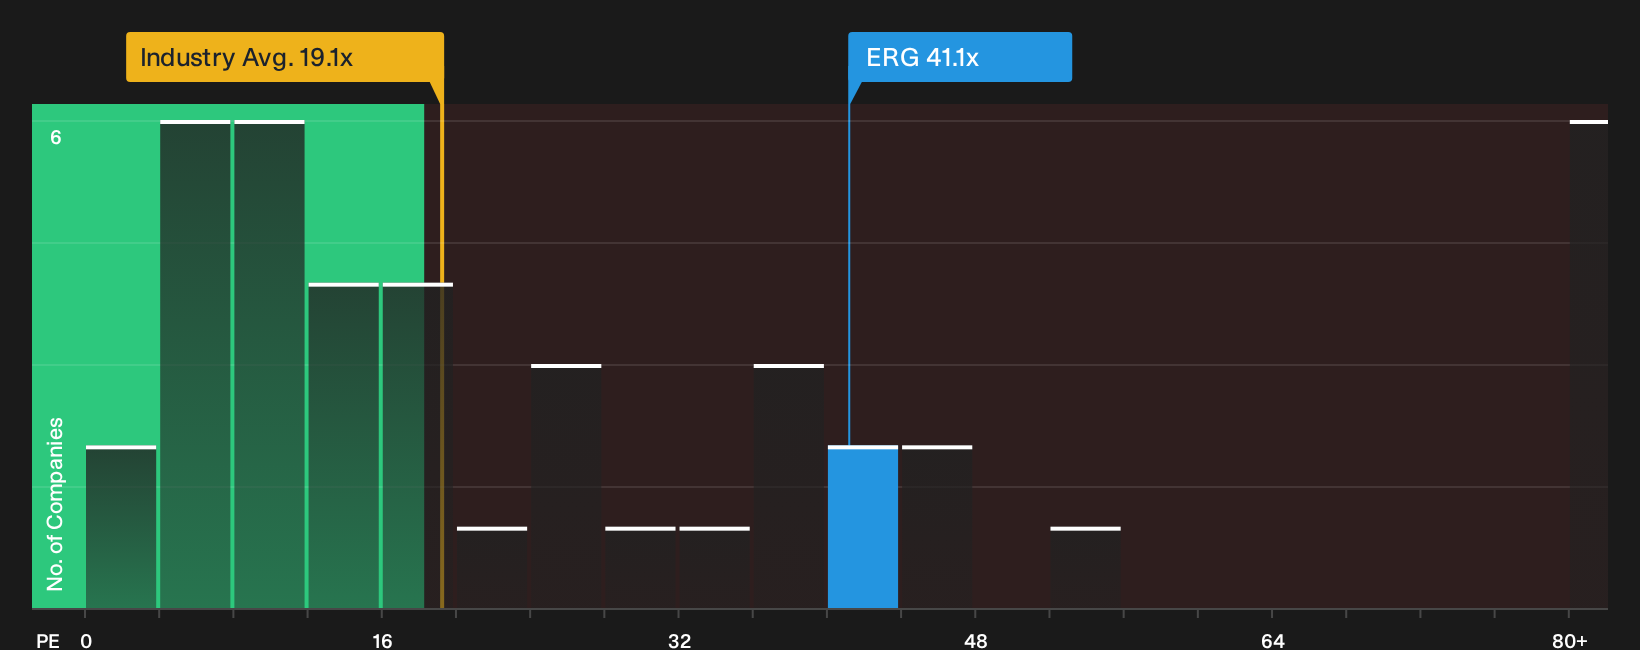
The P/E ratio suits ERG because earnings still sit at the center of how investors look at regulated and contracted utilities. On this lens the stock trades on roughly 41.1x earnings, which is well above the Renewable Energy sector average of about 14.9x and also above the peer group around 21.6x. That gap means each euro of ERG earnings currently carries a richer price tag than many listed renewable operators.
The tailored fair P/E that factors in ERG specific growth profile, profitability and risk sits lower than the current market multiple, so the shares screen as overvalued on this framework. Because the fresh five year Glencore PPA in Poland increases future revenue visibility, some of that premium may reflect investors paying up for contracted cash flows rather than purely near term profit. If you hold or are considering ERG, the key question is whether the quality and stability of those earnings are strong enough to justify paying such a high earnings multiple relative to sector and peer benchmarks. Explore the numbers behind ERG's P/E valuation.
The ERG Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where ERG's valuation puzzle leaves off. Narratives spell out which paths for ERG's growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than it does today. Each one treats fair value as a thesis about the business that you can watch over time rather than a one off snapshot, all housed on Simply Wall St's Community page.
ERG attracts two distinct readings in the community, with one group seeing a bit more upside while the other treats the current level as roughly in line with its risks.
Bull case: 11% undervalued
"Diversification, capacity expansion, and long-term power agreements enhance revenue stability and position ERG to meet rising renewable energy demand..."
Discover why this Narrative puts ERG at 11% undervalued.
Bear case: roughly fairly valued
"Rising financing costs and regulatory delays are eroding profit margins and constraining ERG's project expansion in key regions..."
Explore why this Narrative puts ERG at roughly fairly valued.
Before acting on ERG's valuation, there is one more angle to check
Price multiples tell you what the market pays for ERG today, but professional projections for revenue, earnings and cash flows a few years out offer a very different reference point for judging that price. Explore where analysts expect ERG to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com