
Cipher Digital (CIFR) Stock Could Be Expensive On Its 463% Three Year Run
Cipher Digital has delivered a very large three year share price gain, yet the recent pullback leaves a clear question for you as an investor. Is the current US$13.52 price still aligned with what this business is generating, and expected to generate, in sales?
- Over the past three years, Cipher Digital has returned about 463.3%, which puts a lot of weight on whether its sales can support that kind of re-rating.
- The extended Fluidstack agreement at Barber Lake lifts contracted revenue to US$16.5b across 700 MW of capacity, which can shape how investors think about the durability and timing of Cipher Digital's future top line.
- There is a second opinion on Cipher Digital worth weighing. See what analysts think Cipher Digital's shares could be worth.
The issue now is whether Cipher Digital's current share price is justified by its sales profile once you set that performance and contract backlog against how the market is valuing its revenue stream.
If you want more context for Cipher Digital's recent move and contract story, a focused stock screen built around AI infrastructure and data-center themes can help. You can start with 92 AI infrastructure stocks.
Is Cipher Digital Getting Expensive on Sales?
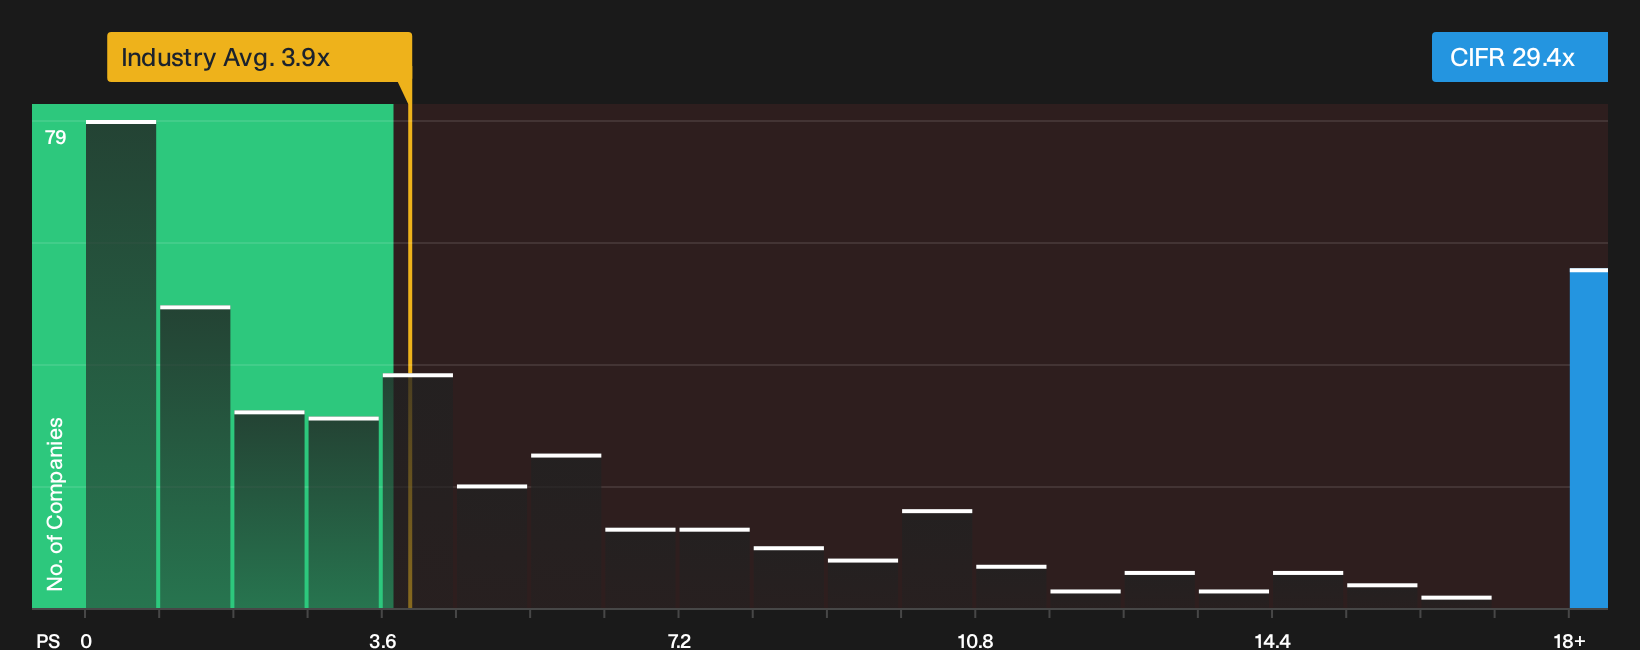
P/S fits Cipher Digital because investors are focusing on revenue potential rather than current earnings. On that basis, the stock trades on a P/S of 29.4x, versus about 3.9x for the broader software group and roughly 14.5x for closer peers, so the share price is already attaching a heavy value to each dollar of current sales.
Because the extended Fluidstack and AWS contracts give Cipher Digital multi year visibility on booked revenue, the valuation model pushes the tailored fair multiple far below the current P/S and flags the shares as overvalued on this framework. The gap looks extreme partly because the model is heavily penalising ongoing free cash flow losses and execution risk, so the fair figure is better read as a warning signal that the stock screens as very expensive rather than as a precise target. Despite the Barber Lake extension lifting long term revenue commitments to US$16.5b across 700 MW, the market multiple already assumes a lot of that contracted top line converts cleanly into value. Explore the numbers behind Cipher Digital's P/S valuation.
The Cipher Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Cipher Digital's valuation puzzle leaves off by spelling out what kind of future growth, profitability and earnings path would need to play out for the shares to look materially higher or lower than today. Each scenario ties its number to a clear view on how Cipher Digital's revenue trajectory, margins and key risks might evolve, which you can come back to as fresh information comes through.
One of the top community narratives on Cipher Digital: 56% undervalued
"The thesis on Cipher Digital has shifted from viewing it primarily as a Bitcoin miner with optionality in high performance computing to treating it as an emerging hyperscale AI and data center landlord..."
Discover why this Narrative puts Cipher Digital at 56% undervalued.
One more crucial piece on Cipher Digital that the valuation does not answer
Cipher Digital's pricing story only tells part of what you need to weigh, because our broader checks have raised separate concerns that could change how you see the whole setup. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com