
bioMérieux (ENXTPA:BIM) Stock Climbed, What Is Behind The Fresh Attention?
bioMérieux (ENXTPA:BIM) has rolled out its SPINCHIP point of care platform alongside a CE marked high sensitivity cardiac troponin I test, a launch closely tied to acute cardiac diagnostics and near patient testing.
Recent trading implies investors are warming back up to bioMérieux, with a 30 day share price return of 16.0% and a 90 day gain of 19.2%. However, the year to date share price return is down 24.0% and the 1 year total shareholder return has declined 26.5%, so momentum has picked up in the short term while the longer track record remains weak.
Scan how bioMérieux's momentum compares with other healthcare diagnostics players by checking the hand picked 127 healthcare AI stocks that are drawing attention right now.
Short-term gains have arrived quickly, while the longer track record still shows damage. At around €83 a share, does bioMérieux now offer a fair balance between risk and potential reward, or has the easy upside already gone?
Most Popular Narrative: 5% Overvalued
On the most followed narrative, bioMérieux’s fair value sits at about €79 per share, a touch below the recent €83.2 close. This puts more pressure on the growth story to do the heavy lifting.
Volatility in BIOFIRE placements and the impending expiration of 5-year contracts signed during the pandemic could potentially lead to a decline in new installations, affecting future revenue growth. The potential for increasing competition, particularly from new entries in the U.S. respiratory market such as Diasorin, poses pricing pressure on bioMérieux's core syndromic testing business, potentially impacting net margins.
See why 5 investors see bioMérieux as 5% overvalued.
Result: Fair Value of €79.04 (OVERVALUED)
Still, if BIOFIRE contract roll offs hit installations harder than expected or if U.S. respiratory competitors squeeze pricing, the current bioMérieux narrative could change quickly.
Find out about the key risks to this bioMérieux narrative.
Another View: bioMérieux Through The Cash Flow Lens
The first narrative frames bioMérieux as roughly 5% overvalued around €83 by comparing price with an estimated fair value of about €79. A different prism tells another story. Our DCF model suggests a future cash flow value of €112.55, which is well above the current share price and implies the stock is undervalued on this framework.
That split between a DCF based fair value and a lower target built on earnings expectations raises a simple question for investors. Which set of assumptions feels more realistic for how bioMérieux will actually convert its pipeline and contracts into long run cash generation, and which feels too generous?
Look into how the SWS DCF model arrives at its fair value.
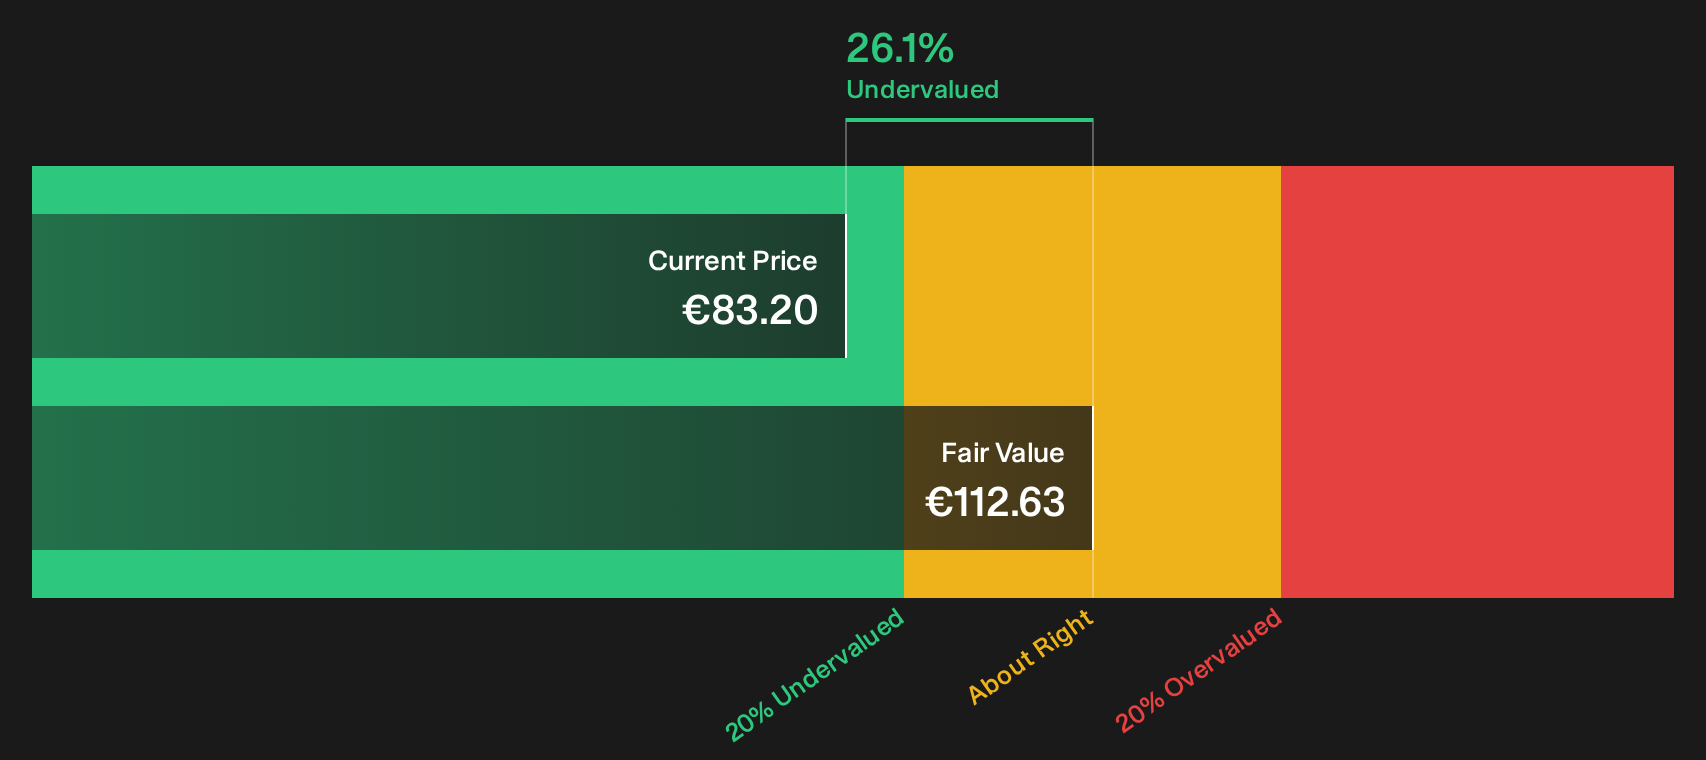
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out bioMérieux for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 175 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this review of bioMérieux is mixed, so consider acting promptly and stress test the numbers yourself, then weigh up the 3 key rewards.
Looking for more investment ideas beyond bioMérieux?
Do not stop with a single diagnostics stock when you can quickly scan wider markets for fresh ideas that match your own risk, income, and value checklist.
- Chase potential mispricing by scanning companies that screen as high quality and undervalued in the market through the 175 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a 221 resilient stocks with low risk scores that focuses on resilience when conditions get tougher.
- Hunt for tomorrow's potential leaders early by checking a 618 high quality undiscovered gems that filters for strong fundamentals before broader attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com