
Verbio (XTRA:VBK) Climbed, What Is Behind The Fresh Attention?
Verbio (XTRA:VBK) moved into focus after its recent Capital Markets Day, where management highlighted the commissioning of a new ethanolysis plant for bio-based speciality chemicals and outlined priorities for earnings, cash flow and capital discipline.
Recent trading has been volatile for Verbio. The share price has climbed 8.47% over the past day yet is still down 15.03% on a 30 day share price return and 11.45% on a 90 day share price return, while the 1 year total shareholder return of 108.53% contrasts with a weaker 3 and 5 year total shareholder record. This points to momentum that has picked up more recently than over the longer haul.
Scan how Verbio compares with other renewables-focused players by reviewing our hand picked list of solid balance sheet and fundamentals (204 results).After Verbio’s sharp one-day rebound and a still weak three- and five-year record, the key issue now is simple. Does the current valuation still compensate you for that choppy history and the execution risk ahead?
Most Popular Narrative: 39% Undervalued
Verbio’s most followed narrative points to a fair value of €44 per share compared with the last close at €26.90. This puts the current debate squarely on whether the long-term story justifies that valuation gap under a 5.41% discount rate.
The anticipated tightening of biofuel supply as higher-cost competitors reduce output, combined with gradual policy improvements, such as stricter fraud controls and quota increases across Europe, is likely to support a material recovery in greenhouse gas (GHG) quota prices. This would directly impact Verbio’s revenue and EBITDA, as each €1 rise in quota price increases annual EBITDA by €1 million.
Verbio’s technology-led ramp-up in U.S. ethanol and renewable natural gas plants positions the company to capitalize on global market openings (for example, the U.K. opening to U.S. ethanol) and on increasing efficiency. This supports higher utilization, improved net margins, and materially higher EBITDA from North American operations over the next fiscal years.
See why 10 investors see Verbio as 39% undervalued.
Result: Fair Value of €44 (UNDERVALUED)
Still, Verbio’s reliance on supportive regulation and exposure to volatile feedstock costs could quickly undermine this undervaluation story if policy or pricing moves against it.
Find out about the key risks to this Verbio narrative.
Another View: Verbio Looks Expensive On Earnings
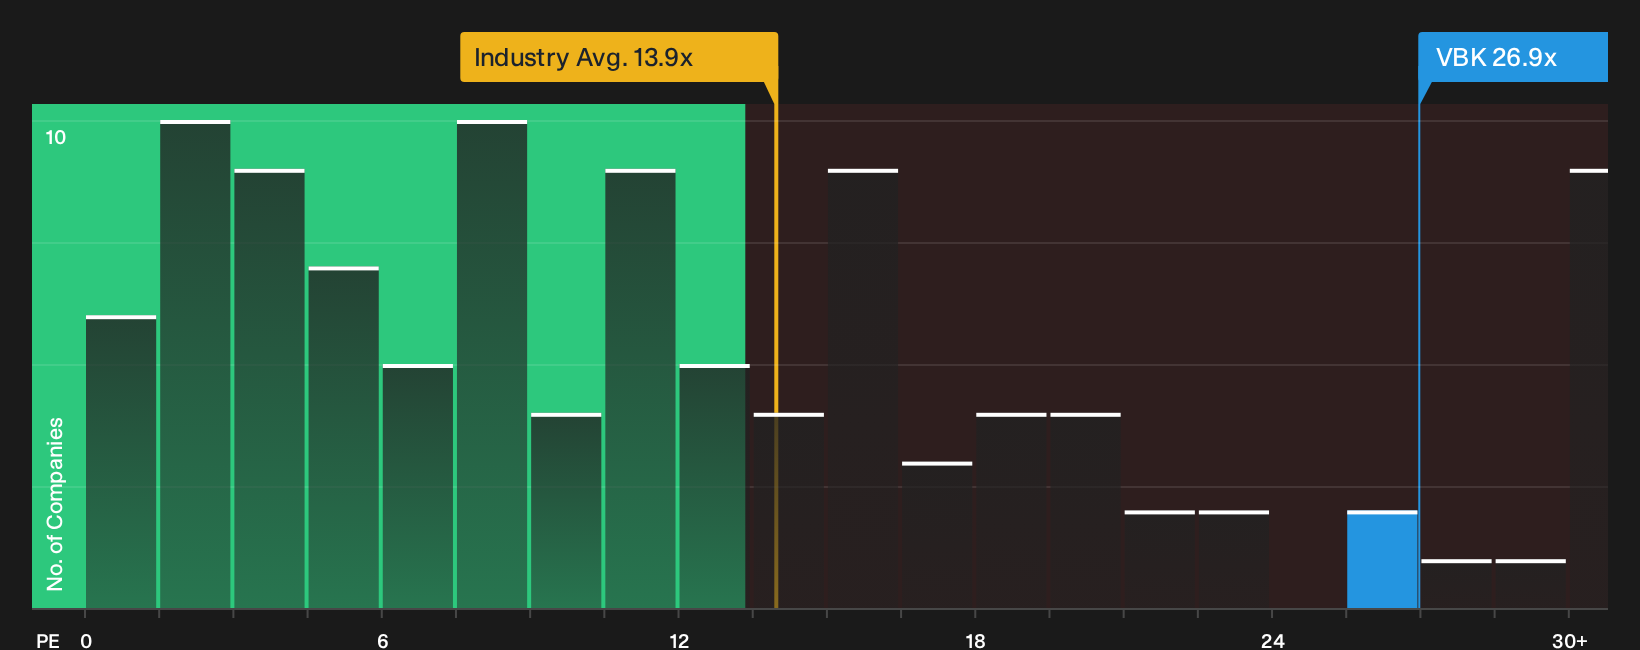
Look past the headline 39% undervaluation claim and the picture shifts. On a simple earnings yardstick, Verbio trades on a P/E of 26.9x. That is almost triple the European Oil and Gas industry at 13.9x and above its own fair ratio of 24.1x.
In practice, that means the market is already paying a premium versus peers and even relative to where the P/E ratio could move if it gravitated toward the fair ratio. For anyone leaning on the undervalued story, the question becomes clear: How comfortable are you paying up today for a business with this backdrop of execution and policy risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The narratives around Verbio cut both ways. Treat this as your cue to move fast, test the assumptions and weigh the upside yourself with 3 key rewards.
Looking For More Ideas Beyond Verbio?
Do not stop with Verbio. Broaden your watchlist now, or you risk missing solid businesses and income ideas that could fit your portfolio better.
- Target potential upside in quality companies trading below estimated value with the Simply Wall St screener focused on 618 high quality undiscovered gems.
- Strengthen your income stream by scanning for companies with resilient payouts through the screener highlighting 221 dividend fortresses.
- Prioritise resilience by reviewing the screener built around 221 resilient stocks with low risk scores and focus on businesses with sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com