
Will Longer Snow Lake Mine Life Change Hudbay Minerals' (TSX:HBM) Narrative
- Hudbay Minerals recently published an updated mine plan for its Snow Lake operations in Manitoba, outlining 27.0 million tonnes of mineral reserves containing about 2.0 million ounces of gold and a reserve life to 2043.
- The plan points to longer use of existing infrastructure and a larger reserve base at Snow Lake, which can influence Hudbay Minerals' long term production mix and capital allocation across its North and South American portfolio.
- We will now look at how Hudbay Minerals' investment narrative is affected by the expanded Snow Lake reserves and extended mine life.
Compare Hudbay Minerals' extended mine life with other producers positioning for the next leg of the metals cycle by scanning our curated list of 36 elite gold producer stocks in one place.
Hudbay Minerals Investment Narrative Recap
To own Hudbay Minerals, you need to believe the copper and gold portfolio can convert a concentrated set of projects into sustained cash generation, without major stumbles at assets like Copper World or Snow Lake. The updated Snow Lake mine plan supports that thesis by extending reserves and clarifying a longer operational runway, but it does not change the fact that execution remains central.
In the near term, the key catalyst is still consistent delivery against production and cost guidance in Manitoba, Peru and British Columbia, backed by the balance sheet flexibility already in place. The biggest risk remains project and jurisdictional disruption, where wildfires, protests, cost inflation or permitting setbacks could quickly pressure margins and delay the payoff from the expanded reserve base.
The updated Snow Lake mine plan is the most relevant recent disclosure for this story, because it directly affects how dependable Hudbay Minerals’ Manitoba complex may be as a cash flow engine. Management now has line of sight on 27.0 million tonnes of reserves, 2.0 million ounces of contained gold and a reserve life to 2043, which frames how long existing processing facilities can be utilized.
That matters for every other catalyst investors are watching, from Copper World development pacing to further mill optimization, because a longer, more defined life at Snow Lake can support funding decisions and sequencing. It also sharpens the risk picture, since any operational issues, ESG constraints or cost surprises in Manitoba would now affect a larger, more extended plan rather than a short dated mine schedule.
Hudbay Minerals’ current analyst narrative points to revenues of $3.5 billion and earnings of $847.8 million by 2029, built on 12.6% yearly revenue growth and an earnings increase of about $169.6 million from $678.2 million today.
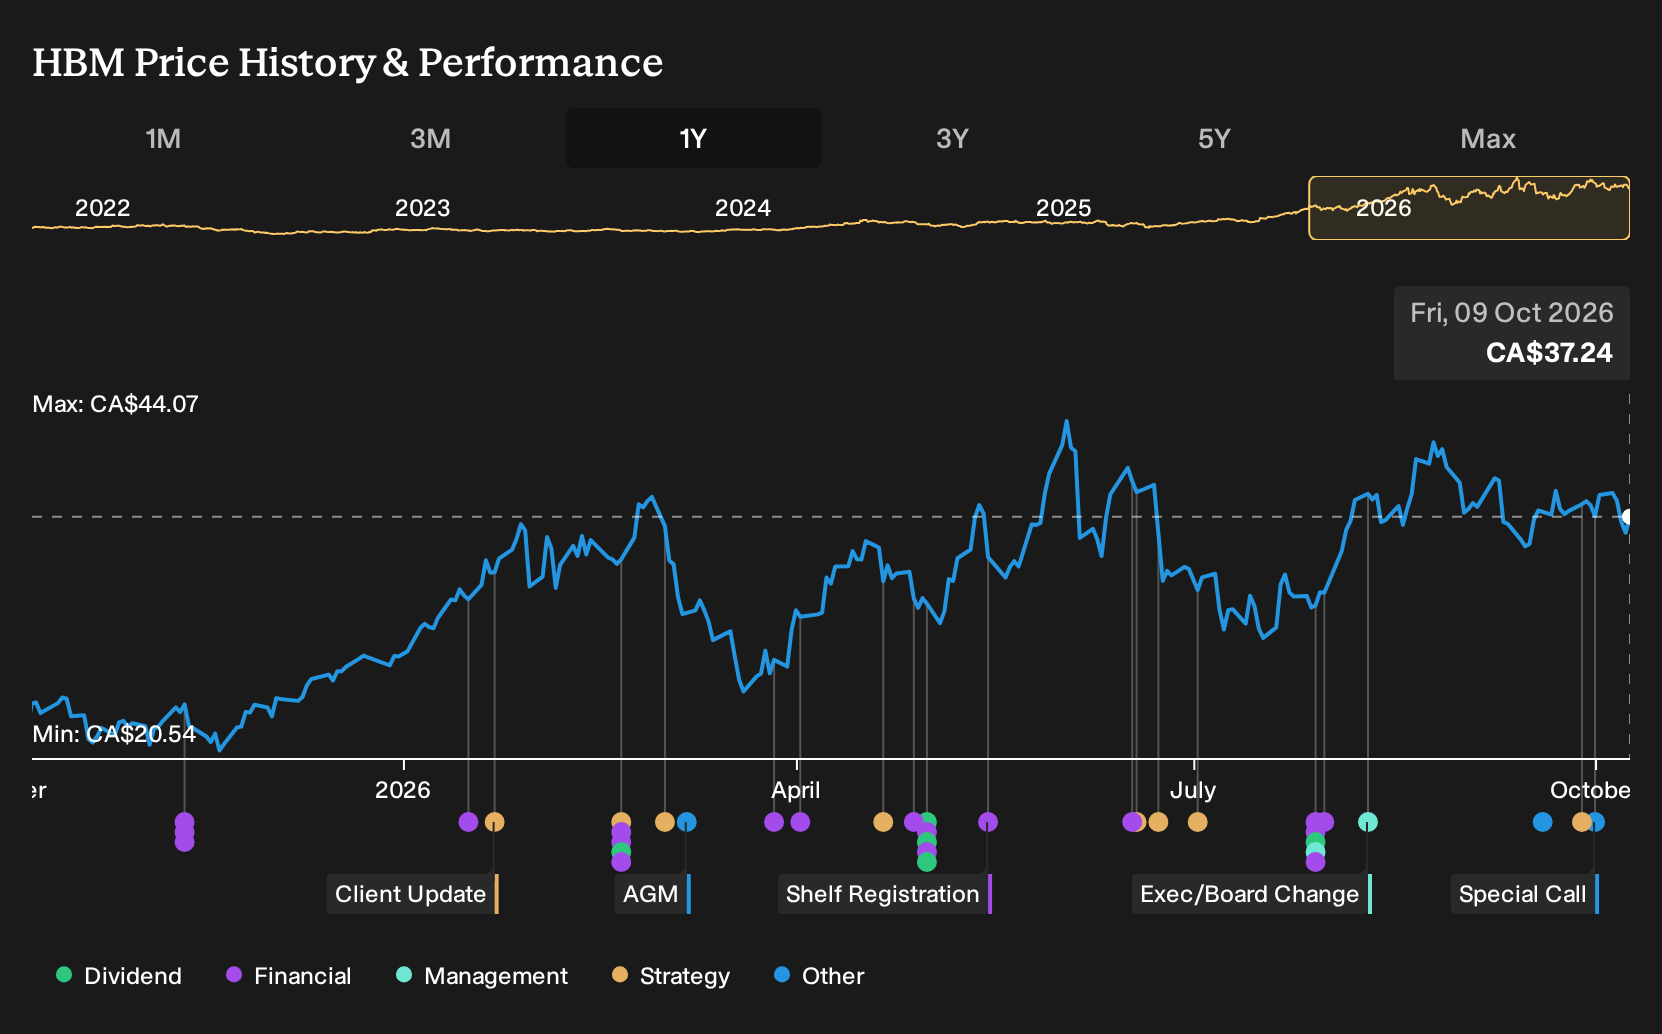
Uncover why Hudbay Minerals' fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Copper World front and center. You see Hudbay Minerals as heavily tied to one big United States build, so permitting or cost surprises there could matter more than extra Snow Lake reserves. The most cautious analysts were assuming only $3.0b of revenue and $452.5m of earnings by 2029. That is a far more muted story than the consensus and it has not yet absorbed the latest Snow Lake plan, so future revisions could shift those expectations in either direction. If you want a fuller picture, compare both sets of assumptions and decide which feels closer to your own outlook.
Explore 4 other Hudbay Minerals fair value estimates, including one that suggests it could be worth just CA$35.61.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hudbay Minerals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hudbay Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hudbay Minerals' overall financial health at a glance.
Looking for more Hudbay Minerals sized ideas?
If Hudbay Minerals has you thinking about position sizing, risk and upside in a more structured way, it can help to line it up against a wider watchlist built with consistent rules.
- For investors hunting for quality at a discount, start with a hand picked set of 9 high quality undervalued stocks that combine solid fundamentals with more modest valuation multiples.
- If capital protection is front of mind, focus on businesses that score well on stability and balance sheet strength by screening across 7 resilient stocks with low risk scores and stress testing your comfort with drawdowns.
- To surface opportunities that are not yet widely followed, broaden your research to a curated pool of 9 high quality undiscovered gems that pair cleaner financials with lighter analyst coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com