
8% Undervalued OGE Energy (OGE) As Grid Growth Narrative Meets Zacks Comparison
OGE Energy (OGE) is back in focus after fresh Zacks research compared the utility with German peer RWE AG, highlighting differences in earnings outlook, valuation grades, and current Zacks Rank ratings.
Recent trading has been mixed for OGE Energy, with the 1-day share price return of 0.85% and 7-day gain of 2.56% offset by a 90-day share price decline of 4.42%. The 5-year total shareholder return of 70.10% reflects a much stronger long-run picture. At a latest share price of US$46.50, that pattern suggests near term momentum has cooled even as long term holders have seen solid compounding. This helps frame the fresh Zacks comparison with RWE AG as part of a broader debate about earnings quality, valuation, and risk for utility investors looking across markets.
Scan the regulated power space beyond OGE Energy by comparing peers in our curated 43 power grid technology and infrastructure stocks to see which utilities align best with your risk and return preferences.
OGE Energy trades at a single digit discount to analyst targets while carrying a much larger gap to some fair value estimates after a recent 90 day pullback. Is the caution in that pricing mismatch earned?
Most Popular Narrative: 8% Undervalued
Against the last close of $46.50, the most followed narrative pegs OGE Energy’s fair value at about $50.45. This frames the recent pullback as a pricing gap that rests heavily on big-ticket grid and large-load projects actually getting built and earning a return.
Ongoing and planned investments in generation capacity and transmission infrastructure are now backed by a draft 2026 resource plan that identifies about 1.9 gigawatts of incremental capacity needs by 2031, as well as specific projects such as 550 megawatts of capacity additions in 2026, the 300 megawatt Frontier Storage project in 2027, and Southwest Power Pool assigned 765 kV transmission work. Together these initiatives extend the capital cycle and rate base growth potential, supporting future earnings.
See why 2 investors see OGE Energy as 8% undervalued.
Result: Fair Value of $50.45 (UNDERVALUED)
Still, this story can break if regulators continue to push back on cost recovery, or if industrial and oilfield demand stays weak despite large data center wins.
Find out about the key risks to this OGE Energy narrative.
Another View: OGE Energy On Earnings Multiples
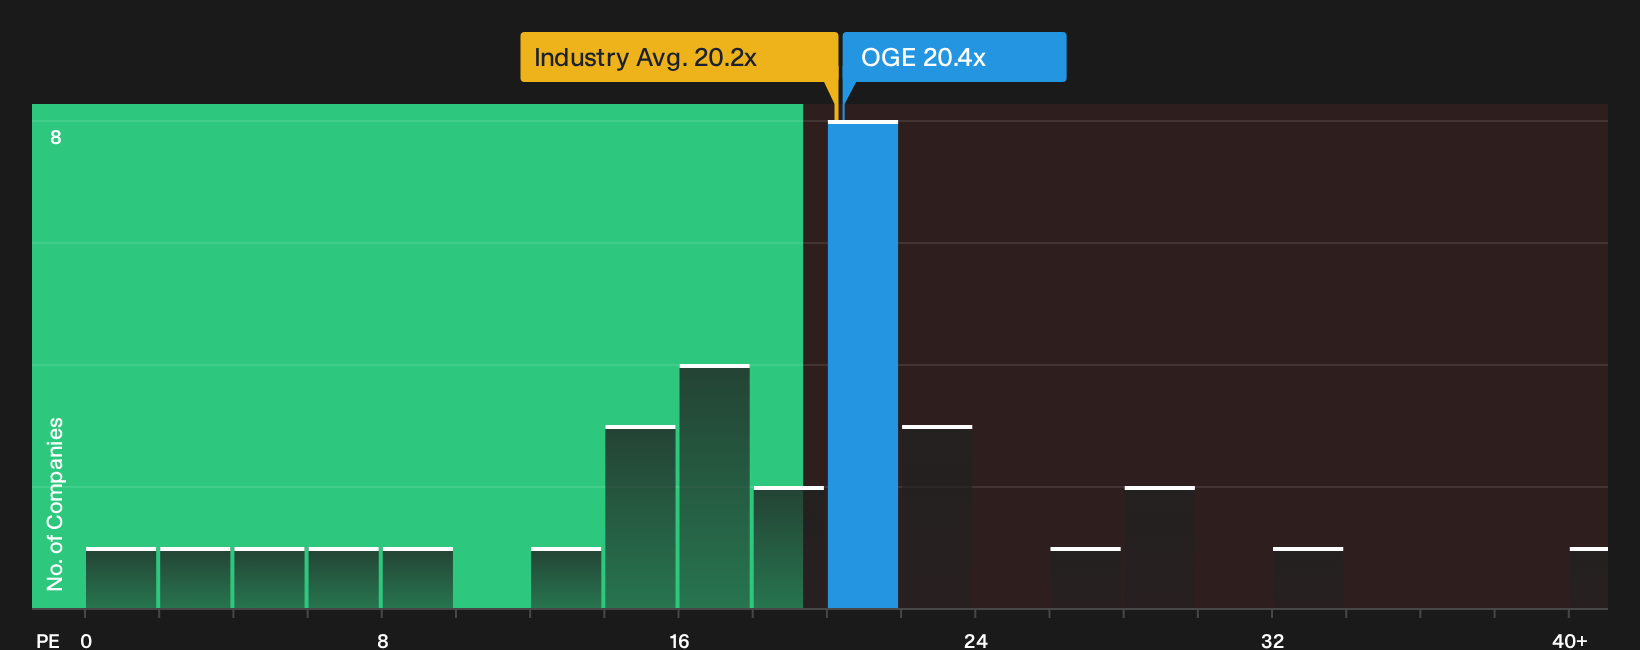
The fair value narrative around OGE Energy leans on long term load growth and capital plans, yet the current P/E of 20.4x tells a different story. It sits slightly above the US electric utilities industry at 20.1x and above the 19x fair ratio, which points to limited valuation cushion if execution slips.
For investors who prefer to anchor decisions on earnings multiples and peer comparisons, this gap raises a practical question: Is the premium a reasonable price for OGE Energy’s large project pipeline, or does it leave too little room for regulatory or financing setbacks before the share price has to adjust, one way or the other?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around OGE Energy can be confusing, so move quickly, pull up the full data set, and weigh both sides of the story for yourself with 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond OGE Energy?
Do not stop with one ticker when a broader watchlist can sharpen your decisions and help you spot better combinations of return potential and risk control.
- Target long term value by scanning companies that combine quality fundamentals with discounted pricing using our 27 high quality undervalued stocks.
- Prioritize resilience and capital preservation by sorting for businesses with stronger financial footing through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities with healthier metrics and quieter coverage by reviewing the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com