
Is Wolters Kluwer (ENXTAM:WKL) A Bargain As Its AI Rollout Expands?
Wolters Kluwer (ENXTAM:WKL) has rolled out new AI driven tools across tax, legal, and healthcare workflows, capped by TaxWise agentic preparation capabilities that automate document handling while keeping professionals in control of final reviews.
Despite the latest AI launches across tax, legal, and healthcare, Wolters Kluwer’s 1 year total shareholder return is down 28.57%, even as recent momentum has picked up with a 23.97% 90 day share price return and a 12.28% 30 day move.
Scan how Wolters Kluwer’s AI push compares with other automation driven plays by zeroing in on 37 profitable AI stocks that aren't just burning cash that pair real earnings with sector level momentum.
Wolters Kluwer now trades at what looks like a steep discount to both analyst targets and some fair value estimates after a sharp 90 day rebound. Is that a genuine opportunity, or a market warning signal?
Most Popular Narrative: 5% Overvalued
Wolters Kluwer last closed at €75, which sits modestly above the narrative fair value of €71.44. The story therefore tilts toward a small premium rather than a deep bargain.
So the investment case is this: you are buying a high-quality company with durable characteristics at a time when sentiment is weak. If management proves that AI becomes an enhancement rather than a disruption, today’s valuation could look attractive in hindsight.
See why 13 investors see Wolters Kluwer as 5% overvalued.
Result: Fair Value of €71.44 (OVERVALUED)
Still, two things can break this story quickly: AI tools that erode pricing power faster than expected, or regulatory shifts that raise Wolters Kluwer’s compliance costs.
Find out about the key risks to this Wolters Kluwer narrative.
Another View On Wolters Kluwer Valuation
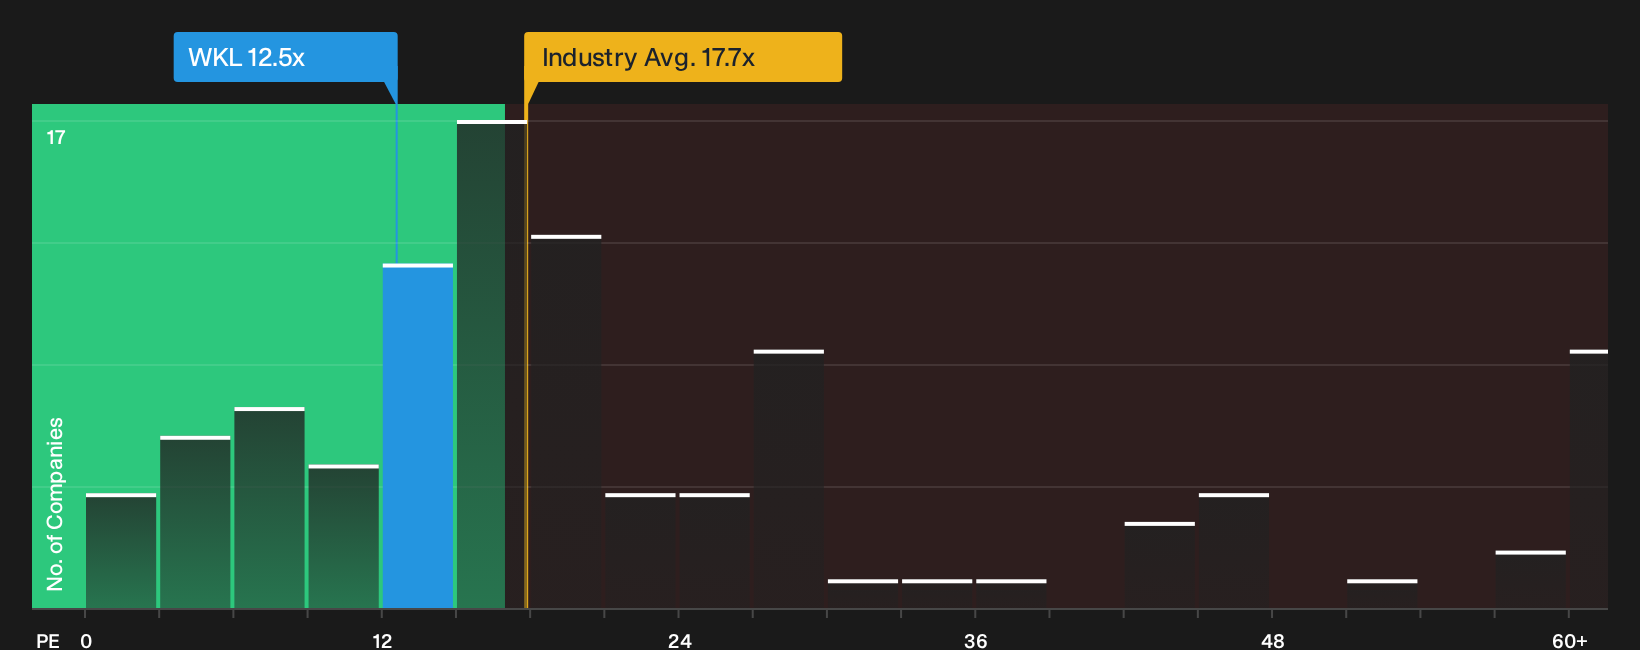
While the narrative fair value pegs Wolters Kluwer at €71.44 and labels the stock 5% overvalued at €75, the current 12.5x P/E tells a different story. That multiple sits well below the 16.3x fair ratio, the 17.7x industry average, and the 26.7x peer level. This points to a sizeable valuation gap investors need to interpret as either a margin of safety or a signal that the market is pricing in real structural risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Wolters Kluwer is clearly mixed right now. Move quickly, pull up the full data set, and weigh the 5 key rewards and 1 important warning sign.
Looking for more Wolters Kluwer sized opportunities?
If Wolters Kluwer has sharpened your focus on valuation and quality, do not stop here. Use the Simply Wall Street Screener to uncover fresh ideas you might otherwise miss.
- Target potential mispricings by scanning a curated 172 high quality undervalued stocks that blend healthy fundamentals with price tags the market may not fully appreciate yet.
- Strengthen your income game by reviewing a hand picked set of 221 dividend fortresses designed for investors who want yield backed by real balance sheets.
- Protect your capital by filtering for 222 resilient stocks with low risk scores that score well on financial resilience so big surprises are less likely to catch you off guard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com