
Ameresco (AMRC) Could Be 51% Undervalued Following New Utility Contract Wins
Ameresco (AMRC) just landed a citywide Advanced Metering Infrastructure project in Columbia, Missouri, a US$42 million contract that slots into its awarded backlog and expands its utility modernisation work.
These Columbia and Roseburg contract wins arrive at a tough moment for Ameresco’s listing, with the share price at US$21.01 after a 30-day share price return that declined 12.2% and a 1-year total shareholder return that fell 46.85%, signaling pressure rather than momentum building.
Scan beyond Ameresco and line up other grid and utility upgrade plays using our curated list of 43 power grid technology and infrastructure stocks before the next round of contracts reshapes the sector.
Ameresco trades at a steep discount to both its estimated intrinsic value and published analyst targets, even after the recent slide. Is that caution a sensible read on risk, or is it mispricing that upcoming valuation work will challenge?
Most Popular Narrative: 51% Undervalued
Ameresco is priced at $21.01 while the most followed narrative puts fair value at $42.70, which frames a wide gap between market skepticism and modeled cash flows and puts execution risk under the spotlight.
Growing recurring O&M contract revenue and a rising base of operating energy assets, now above 820 megawatts with more than US$1.5b of long term O&M backlog and over 2.5 gigawatts of third party assets under service, continue to shift Ameresco's mix toward higher margin, more predictable income that can support earnings quality and cash flow consistency.
See why 7 investors see Ameresco as 51% undervalued.
Result: Fair Value of $42.70 (UNDERVALUED)
Still, supply chain setbacks on large projects and any need for fresh funding that dilutes existing holders could quickly challenge the case that Ameresco is 51% undervalued.
Find out about the key risks to this Ameresco narrative.
Another View: Ameresco Through The P/E Lens
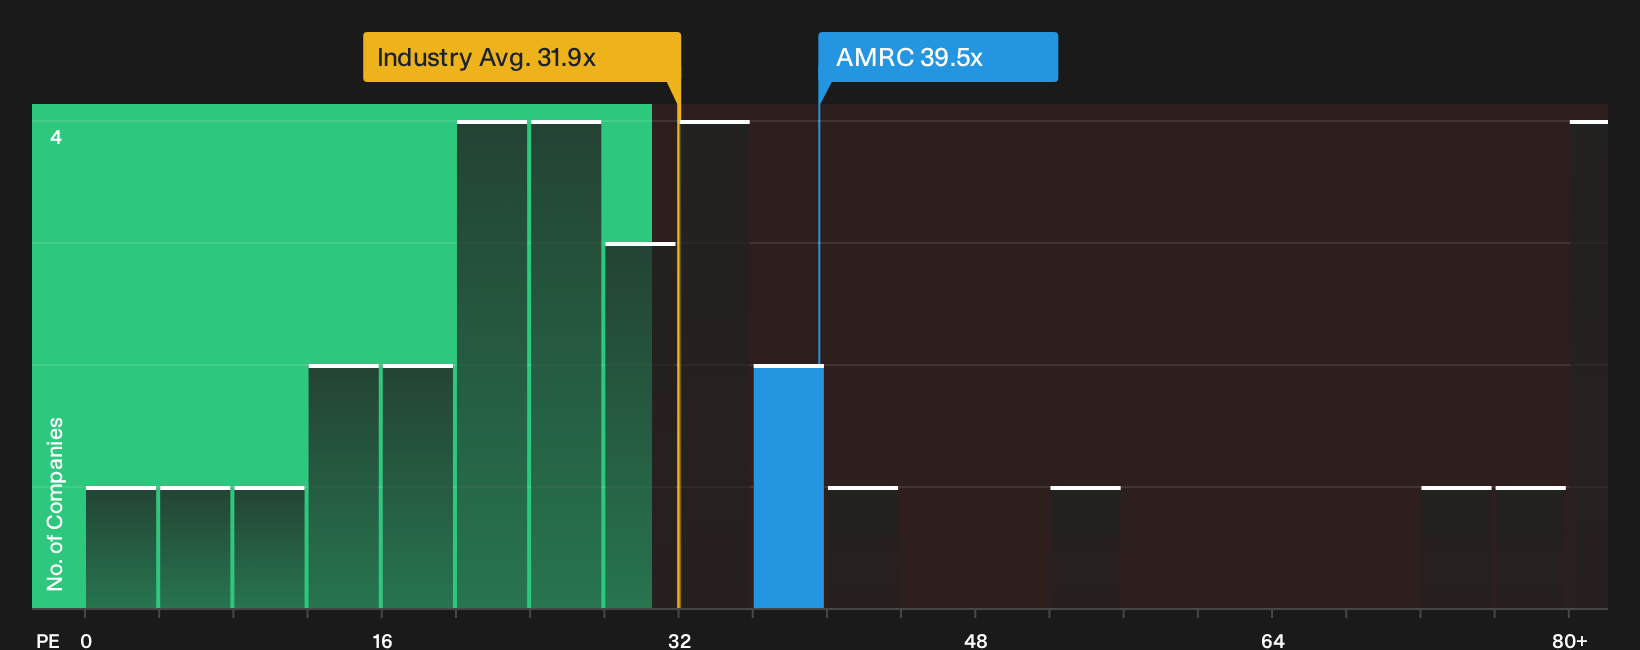
Ameresco might screen as undervalued on fair value estimates, yet its P/E of 39.5x sits above both the US Construction industry at 31.7x and a fair ratio of 37.5x. That richer multiple points to less margin for error. If growth or backlog conversion disappoint, how forgiving will the market be?
To see how these earnings multiples stack up against peers and the fair ratio the market could move toward, go through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Ameresco is split between pressure on the share price and optimism in the underlying contracts, so move quickly, review the data, and judge the balance of 2 key rewards and 3 important warning signs.
Looking for more Ameresco investment ideas?
Before you move on, give yourself an edge by lining up a few fresh angles, because the next compelling idea rarely waits around for long.
- Target quality at a discount and scan a focused 27 high quality undervalued stocks that filters for companies with strong fundamentals trading below their estimated worth.
- Prioritise resilience and review a curated 31 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and fewer red flags.
- Spot tomorrow's potential before the crowd by working through a 20 high quality undiscovered gems that surfaces high quality opportunities hiding in plain sight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com