
How Investors Are Reacting To Sony (TSE:6758) Positive Outlook Revision
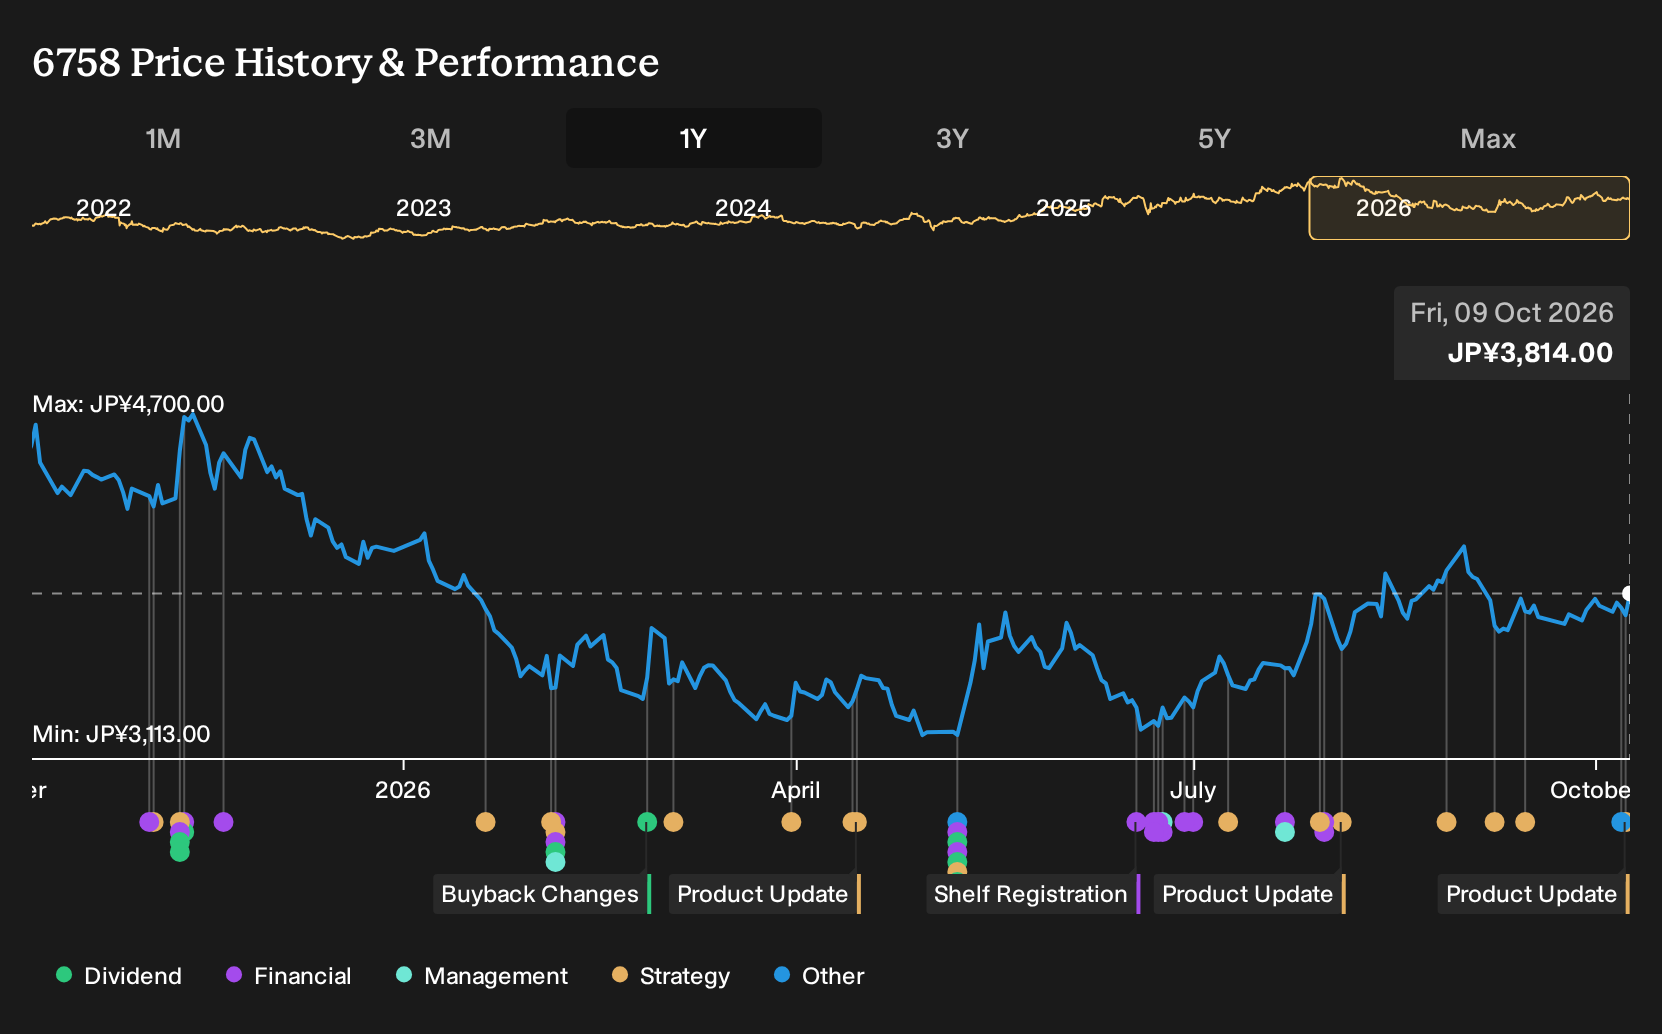
- Sony Group is in focus after Moody's revised its outlook on the group to positive while affirming its A2 issuer rating, alongside fresh product news including the ECM-AX10 Eclipsa Audio-certified smartphone microphone and an ongoing share repurchase that has reached 74,473,700 shares for ¥263,357.99 million.
- The combination of a positive credit outlook, investor attention on the upcoming earnings release, and visible product development in spatial audio tools points to a business that leans on diversified earnings, recurring revenue streams, and smartphone-centric content creation to support its broader operating story.
- We will look at how Sony Group's investment narrative is influenced by Moody's positive outlook shift and what that development might indicate.
What Is Sony Group's Investment Narrative?
The core belief behind owning Sony Group is that a broad entertainment and technology platform, from PlayStation and sensors to music and pictures, can keep throwing off solid cash even when one product cycle is soft. The ECM-AX10 launch fits that idea but in a modest way. It reinforces a smartphone creator ecosystem and leans into higher value audio tools, yet on its own it does not shift near term earnings drivers that still hinge on consoles, games, sensors and content performance.
What matters more in the short run is execution on capital heavy areas like image sensors, disciplined spend on content, and how pricing and demand hold up into the PlayStation cycle and GTA VI driven console interest. The completed ¥263.4b buyback and Moody's positive outlook suggest balance sheet and cash flow confidence, but slower expected revenue growth and a 20.1x P/E leave little room for operational missteps.
Even so, there is a less comfortable angle to the Sony Group story once you factor in...
There's only one way to know the right time to buy, sell or hold Sony Group. Head to Simply Wall St's company report for the latest analysis of Sony Group's Fair Value.
Exploring Other Perspectives
Some of the lowest analysts on Sony Group lean hard into console cycle risk. They were modeling revenue to slip about 1.3% a year and still only reach around ¥12,209.9b by 2029, with earnings at roughly ¥1,118.9b. That is a much more cautious story than consensus, and the ECM-AX10 launch plus buybacks may eventually push those views to shift. You do not need to pick a side today; instead, you can treat this new spatial audio push as one more input when comparing those different forecasts.
Explore 2 other Sony Group fair value estimates, including one that suggests it could be worth just ¥4,398.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sony Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sony Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sony Group's overall financial health at a glance.
Looking For More Ideas Beyond Sony Group?
Once you have a handle on Sony Group, it can help to compare it with other companies that offer different mixes of income, value and balance sheet strength. The Simply Wall St Screener gives you a convenient way to scan across these profiles without losing sight of your own risk tolerance and time horizon.
- If you want potential income plus resilience, check out a basket of yield focused companies in our 28 dividend fortresses that aim to balance strong payouts with sturdier fundamentals.
- For investors who care most about capital preservation and steadier business profiles, filter for companies in the 23 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- If balance sheet quality is your anchor, narrow your search to companies with cleaner debt positions and solid fundamentals using the list of solid balance sheet and fundamentals (23 results) so you can compare Sony Group with businesses that carry different financial risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com