
How Investors Are Reacting To Lindt & Sprüngli (SWX:LISN) Analyst Downgrades
- Chocoladefabriken Lindt & Sprüngli recently issued full year 2026 guidance that points to 4% to 6% organic sales growth and a slight EBIT margin improvement, setting expectations for measured expansion in its premium chocolate business.
- The new outlook puts more focus on how Lindt balances cocoa and other input costs with pricing and product mix, while some analysts now question how execution and current valuation align with these steadier growth ambitions.
- Attention now turns to how Chocoladefabriken Lindt & Sprüngli's investment narrative holds up against this measured guidance and the more cautious debate around execution.
Chocoladefabriken Lindt & Sprüngli Investment Narrative Recap
To own Chocoladefabriken Lindt & Sprüngli, you need to be comfortable with a steady premium chocolate story rather than a fast growth one. The key near term swing factor is how effectively Lindt balances cocoa and broader input costs with pricing and mix, while still keeping higher end consumers loyal during cost of living pressure.
The biggest operational risk is that elevated cocoa costs and softer category volumes squeeze gross margin if further price increases meet resistance. The 2026 guidance for 4% to 6% organic growth with only slight EBIT margin improvement does not fundamentally change that risk reward equation; it mostly clarifies that management is aiming for measured, incremental progress.
The clearest recent datapoint is that Chocoladefabriken Lindt & Sprüngli explicitly guided to 4% to 6% organic sales growth and a small uplift in EBIT margin for 2026. That target anchors expectations for mid single digit top line expansion, supported by premium gifting, geographic diversification and direct to consumer channels that are already in place.
For catalysts, that guidance now acts as a reference point for each trading update. Delivery on organic growth while holding or gently lifting profitability would support the idea that pricing power and store economics remain resilient, despite cautious analyst views and execution questions. Any stumble on volumes or margin could quickly refocus attention on cocoa costs, competition and the risks of a larger retail footprint.
Chocoladefabriken Lindt & Sprüngli's current analyst narrative points to revenues of CHF6.7 billion and earnings of CHF838.9 million by 2029, based on an assumed 4.1% yearly revenue growth rate and an earnings increase of about CHF108.4 million from CHF730.5 million today.
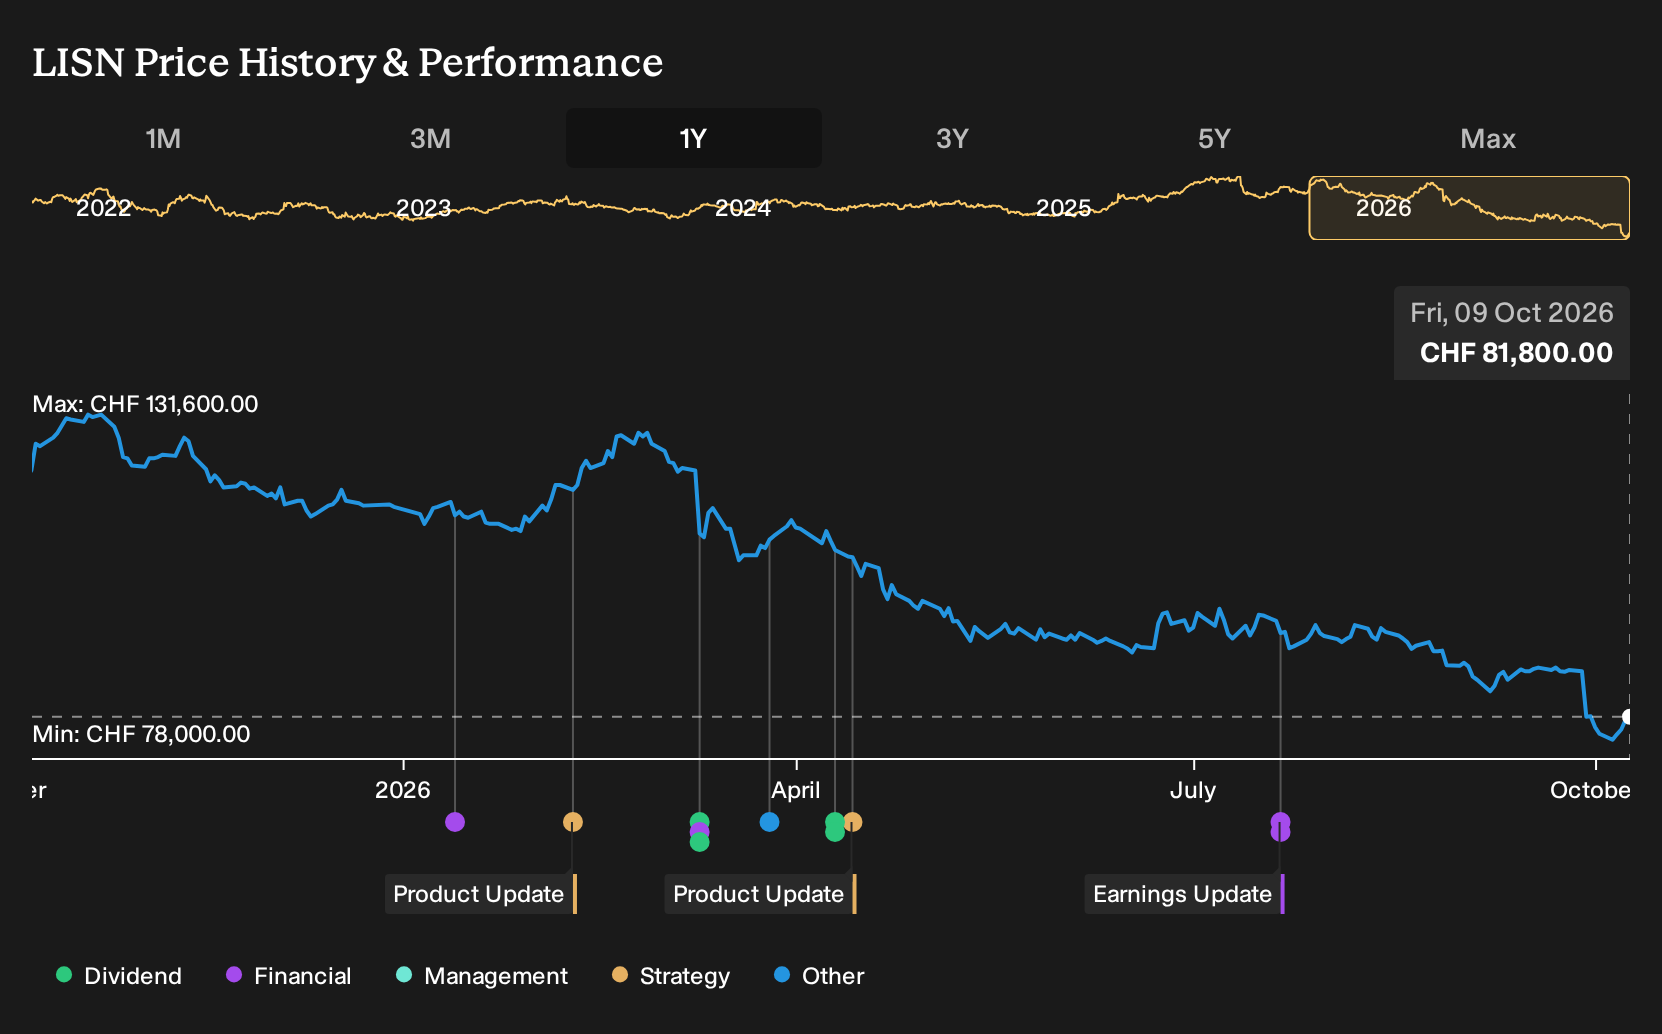
Uncover why Chocoladefabriken Lindt & Sprüngli's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative, more optimistic angle on Chocoladefabriken Lindt & Sprüngli leans heavily on retail and direct to consumer expansion as a strong upside catalyst. The most bullish analysts were pencilling in CHF7.1b of revenue and CHF1.0b of earnings by 2029, far above the CHF6.7b and CHF838.9m consensus, so today’s softer guidance and downgrades may prompt those forecasts to shift. You do not need to pick a side right now. Use the gap between these stories as a prompt to explore which assumptions on growth and margins feel realistic to you.
Explore 5 other Chocoladefabriken Lindt & Sprüngli fair value estimates, including one that suggests as much as 21% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Chocoladefabriken Lindt & Sprüngli research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Chocoladefabriken Lindt & Sprüngli. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chocoladefabriken Lindt & Sprüngli's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chocoladefabriken Lindt & Sprüngli?
If Chocoladefabriken Lindt & Sprüngli has sharpened your focus on quality and pricing power, it can help to compare that profile with other businesses that share similar strengths but operate in different corners of the market.
- For investors who care most about balance sheet strength, start with a list of solid balance sheet and fundamentals (204 results) that can help you focus on financially resilient businesses first.
- If you want income on top of potential capital gains, use a screener built around dependable payouts, such as the 221 dividend fortresses, that highlight stronger yield candidates.
- When the goal is to find tomorrow's standouts before they are widely followed, you can scan a curated pool of promising opportunities with the 618 high quality undiscovered gems, which already clear basic quality hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com