
How to Play Unusual Options Activity in Oracle Stock
Thursday saw tech stocks take a hit as the Nasdaq Composite was down 1.25%, dragging the S&P 500 down 0.47%. At least the Dow managed to eke out a 0.10 gain, while small-cap investors got a break from selling, gaining 0.03%.
Oracle (ORCL) was one of the tech stocks taking it on the chin, losing 5.5% on the day. It’s now down 52% over the past 52 weeks, but up from its July 52-week lows.
I don’t spend much time following ORCL stock. However, its share volume of 42.2 million, 41% higher than the 30-day average, and options volume of 635,702, 49% higher than the 30-day average, made me take a closer look at its unusual options activity from Thursday.
I found that ORCL had the 17th-highest unusually active option yesterday with a Vol/OI (volume-to-open-interest) ratio of 25.95. Further, the Oct. 30 $145 call’s volume of 29,994 was one of only seven options with volume of 25,000 or more on the day.
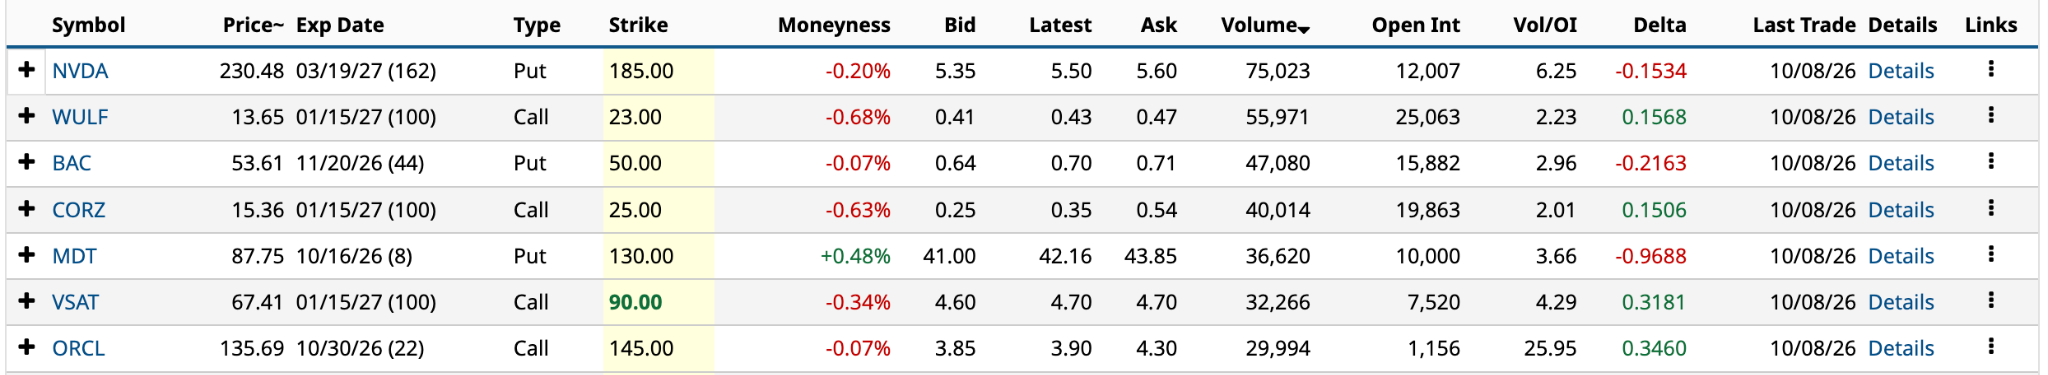
Whenever a single call or put has volume over 25,000, I immediately look at the options flow to understand institutional activity better. I found a lot of vertical spread bets. The question is whether retail investors should go with a Bull Call Spread or a Bear Call Spread. Here’s my two cents.
Have an excellent weekend. If you’re Canadian, Happy Thanksgiving!
The ORCL Unusually Active Option in Question
As shown above, the Oct. 30 $145 call had a volume of 29,994 yesterday, accounting for 4.7% of the stock’s total. That isn’t a significant contribution. However, it was one of only five Oracle options with a volume of 5,000 contracts or more (shown below).
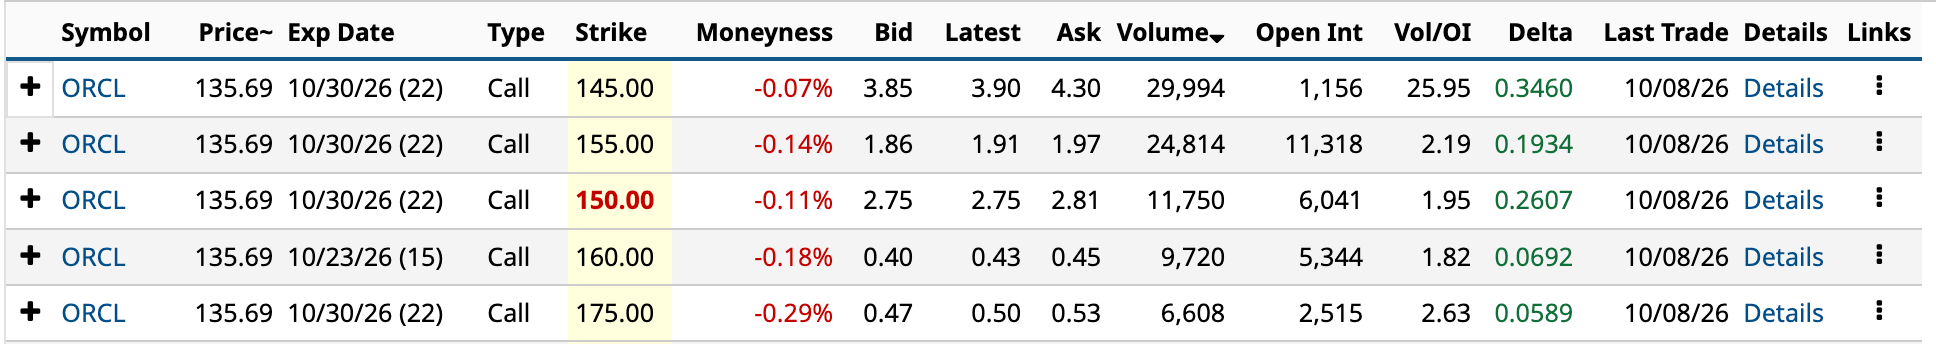
You’ll notice the second-highest-volume option was the $155 call at 24,814, with a Vol/OI ratio of 2.19. Both options are OTM (out-of-the-money), pointing to possible vertical spread bets by institutional investors. Yesterday's options flow gives us a clearer picture.
On Thursday, 13 trades of 1,000 contracts or more ranged from 1,111 to 8,441, with 4 puts and 9 calls. However, the volume of those four put trades was 14,915, 768 higher than the nine calls combined. That’s interesting only because Oracle's total Put/Call volume ratio was 0.47, which is bullish.
I’m focused on the unusually active $145 and $155 calls, both expiring in three weeks. The five multi-leg trades shown below took place yesterday between 12:52:10 p.m. ET and 1:00:29 p.m. ET. The total contracts involved were 5,627.
The key question is whether a bull call spread or a bear call spread was the better bet.





The Oracle Bull Call Spread

As you can see from today’s bull call spread data above, Oracle's share price has bounced back from yesterday’s losses.
The bull call spread is a defined-risk bet that expects the share price to rise. It involves buying the $145 call and selling the $155 call. In this case, that results in a net debit of $3.35 [$6.60 ask price - $3.35 bid price]. That’s also the maximum loss. The maximum profit is $6.65 [$155 strike price - $145 strike price - $3.35 net debit].
The risk/reward ratio is 0.50 to 1 [$3.35 maximum loss / $6.65 maximum profit]. You’re essentially risking 50 cents to make a dollar. The maximum profit percentage of 198.51% is the reverse calculation [$6.65 maximum profit / $3.35 maximum loss].
Looking at the five large multi-leg trades from yesterday, none of the trade prices are right on the ask or bid prices; they're mostly in the middle, making it difficult to know if these trades are bullish or bearish. Given yesterday's net trade sentiment for the Oct. 30 calls and puts, my inclination was bullish at $327,300.
The institution(s) that made these bets spent $2,152,500 on the long $145 calls and received $1,063,600 in premium for the short $155 calls, for a net debit of $1,088,900.
So, if they were bullish, they could have bought the $145 calls on their own for $2.15 million, but by pairing them with short $155 calls, they reduced their cost by 49% while still giving themselves a reasonable chance to make money on the bet.
One note: I used "institution(s)" because the fifth trade at 1:00:39 p.m. ET stands out from the other four, which occurred within a second of each other, 10 or 11 seconds earlier. Either way, the fifth trade was still a vertical spread.
The Oracle Bear Call Spread

The bear call spread is also a defined-risk strategy, but here the institution expects the share price to fall. It involves selling the $145 call and buying the $155 call. That results in a net credit of $2.80 [$6.05 bid price - $3.25 ask price]. That’s also the maximum profit. The maximum loss is $7.20 [$155 strike price - $145 strike price - $2.80 net credit].
The risk/reward ratio is 2.57 to 1. You’re essentially risking $2.57 to make a dollar. The maximum profit percentage is 38.89%. However, as you can see, the profit probability is considerably higher than the bull call spread's at 62.4%.
In this example, the breakeven is $147.80. It makes money below that, down to the $145 strike price, where it achieves the maximum profit of $2.80. It starts losing money above $147.80 and reaches its maximum loss of $7.20 at the $155 strike price.
While it’s counter-intuitive to risk more with the bear call spread to make the same amount as the bull call spread, it makes sense when you consider that to make the maximum profit on the bear call spread, the share price has to be below $145 at expiration, whereas to make the maximum profit for the bull call spread, the share price at expiration has to be above $155 at expiration. That’s a 9.2% gain over the next three weeks; the expected move, up or down, is 8.83%.
Oracle is far more likely to be down 8% than up.
On the date of publication, Will Ashworth did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.