
Scentre Group (ASX:SCG) Extends Debt Profile Following Note Sale As Undervalued View Holds
Scentre Group (ASX:SCG) has just raised US$750 million through 6.20% senior guaranteed notes maturing in 2036. This fresh long dated funding immediately affects the group’s debt profile and future cash priorities.
Recent trading shows that Scentre Group’s 1-week share price return of 2.99% contrasts with a year to date share price decline of 18.44%, while the 3-year total shareholder return of 59.74% points to a much stronger longer term experience for investors. The new A$3.45 level and fresh bond issuance together signal that the market is still reassessing both growth prospects and balance sheet risk after a 90 day share price pullback of 11.08%.
Scan beyond Scentre Group and compare this bond driven balance sheet story with other real estate players screened for resilient funding and fundamentals in our list of solid balance sheet and fundamentals (12 results).
Bulls see a solid mall owner refinancing on attractive terms, while bears see fresh leverage tied to a stock that has fallen strongly this year. Which side does the current valuation of Scentre Group actually support next?
Most Popular Narrative: 14% Undervalued
On the most followed narrative, Scentre Group screens as undervalued, with a fair value of A$4.03 against the current A$3.45 price. That gap leans heavily on how resilient its malls and capital spend are expected to be over time.
The Group's strategy of ongoing redevelopment, densification, and experiential additions to assets is capital intensive and subject to execution risk. If consumer preferences shift away from brick-and-mortar or if macroeconomic confidence wanes, elevated capital expenditures may pressure free cash flow and compress net margins over time.
See why 19 investors see Scentre Group as 14% undervalued.
Result: Fair Value of A$4.03 (UNDERVALUED)
Still, the risk that e commerce steadily siphons away discretionary spending, combined with capital intensive redevelopments, could challenge the bullish Scentre Group thesis.
Find out about the key risks to this Scentre Group narrative.
Another View On Scentre Group’s Valuation
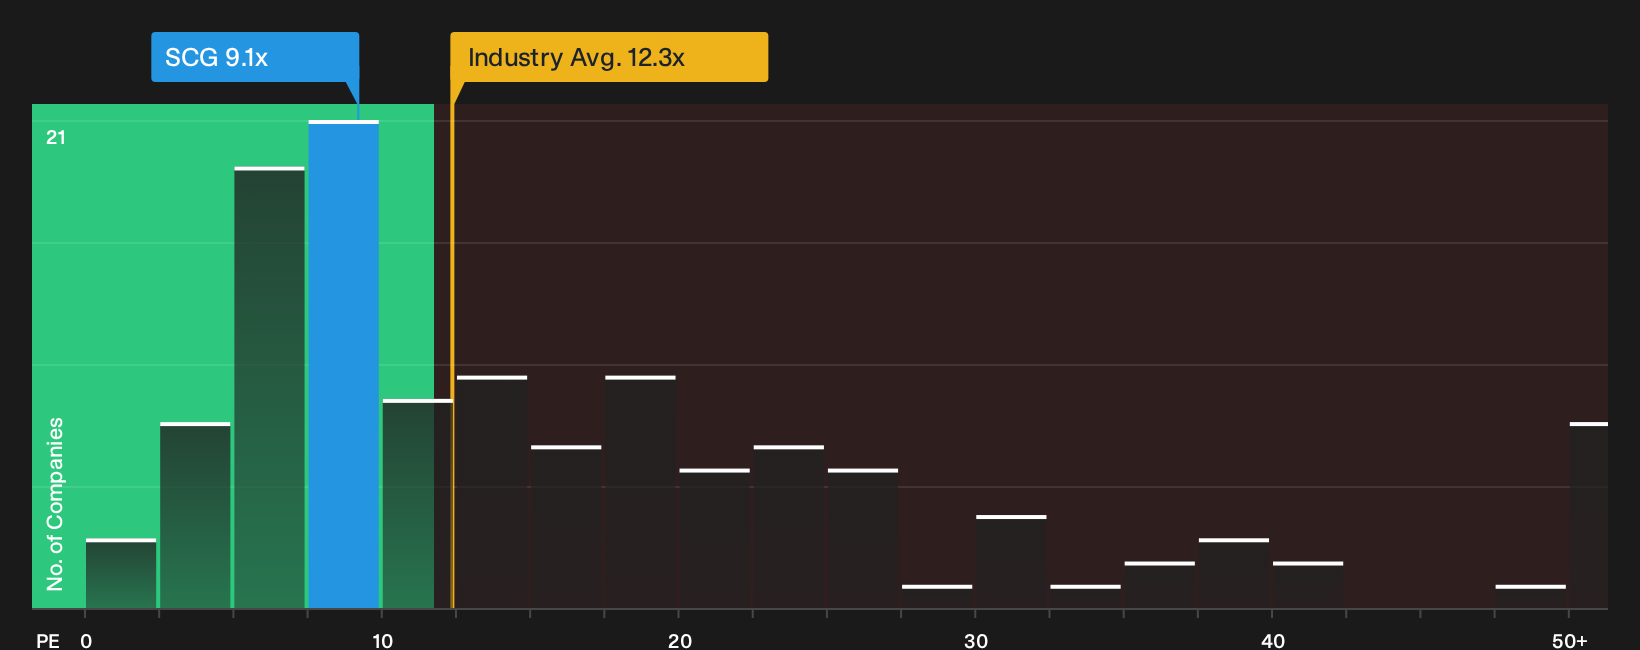
That A$4.03 fair value comes out of analyst forecasts and pricing assumptions. On a simple P/E metric, Scentre Group tells a different story. The stock trades at 9.1x earnings, richer than Australian Retail REIT peers at 7.6x, yet slightly below a fair ratio of 9.6x estimated for the business.
So P/E suggests Scentre Group is only modestly cheap against its own fair ratio, while carrying a premium to local peers. Is that small gap compensation for perceived quality, or a sign that downside risk has not fully washed through yet for mall focused real estate?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Scentre Group’s valuation and risk profile invite your own judgment, not blind agreement. Act while the data is fresh in mind and weigh both sides using 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Scentre Group?
If Scentre Group has sharpened your focus on price, quality and risk, do not stop here. Broader ideas can help you build a stronger overall portfolio.
- Target potential deep value by hunting for businesses that combine solid fundamentals with discounted prices through the 4 high quality undervalued stocks.
- Strengthen your income stream by assessing companies with robust payout profiles using the 6 dividend fortresses.
- Dial down portfolio volatility by filtering for financially resilient opportunities using the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com