
Sanki Engineering And 2 Japanese Quality Stocks To Watch
When consumer sentiment drops to a five month low and headlines focus on rising living costs, many investors crowd into the same mega caps and hope for the best. That leaves a pocket of high quality Japanese small companies overlooked, even when their balance sheets and business models look solid. This article highlights three under the radar stocks from our screener that could add diversification to a portfolio.
The three examples in this article are only a small sample, and the full screen surfaced 71 more high quality businesses with equally compelling stories that are not covered here. To see the full list, head straight into the High-Quality Undiscovered Gems screener to identify, filter, and analyze the ideas that best fit your own conviction.
Sanki Engineering (TSE:1961)
Sanki Engineering is a Tokyo based specialist in HVAC, plumbing, building facilities and smart building control projects for commercial and industrial sites, a direct fit with the screener’s under the radar infrastructure theme. It generates all reported revenue of ¥258.4b in Japan and has a market cap of about ¥398.9b.
Sanki Engineering ties directly into the High Quality Undiscovered Gems idea through its HVAC and smart building projects, with stronger guidance and a sizeable order book pointing to ongoing work in complex infrastructure. Investors get a small cap with improving profitability, although outcomes hinge on how one unseen pressure on its funding costs plays out.
Those funding pressures deserve a closer look, and the 3 key rewards and 2 important warning signs could show whether Sanki Engineering’s upside is masking more going on beneath the surface.

Tsugami (TSE:6101)
Tsugami is a Tokyo based builder of CNC precision machine tools such as automatic lathes, turning centers and machining centers that fit the High Quality Undiscovered Gems theme through niche, high precision equipment for electronics, telecom and auto makers. It reports about ¥122.2b in revenue from China and ¥29.8b from Japan, with a ¥263.9b market cap.
Tsugami combines a focused CNC tool portfolio with reported earnings growth of 53.6% over the past year, a 13.6% net margin and 23.2% Return on Equity. This aligns with the screener’s focus on small caps with strong fundamentals. The main tension sits in how one concentrated source of balance sheet risk evolves.
That concentrated exposure raises a clear question, and the 2 key rewards and 1 important warning sign shows where Tsugami’s balance sheet strength could amplify or limit the next phase.

santec Holdings (TSE:6777)
santec Holdings develops tunable lasers, optical filters, OCT systems and other measurement gear that fits the High Quality Undiscovered Gems theme through niche optical components used in telecom, semiconductor testing and medical imaging. The group reports about ¥25.3 billion from optical measuring instruments, ¥6.5 billion from optical components and ¥2.9 billion from other activities, with a roughly ¥277.8 billion market value.
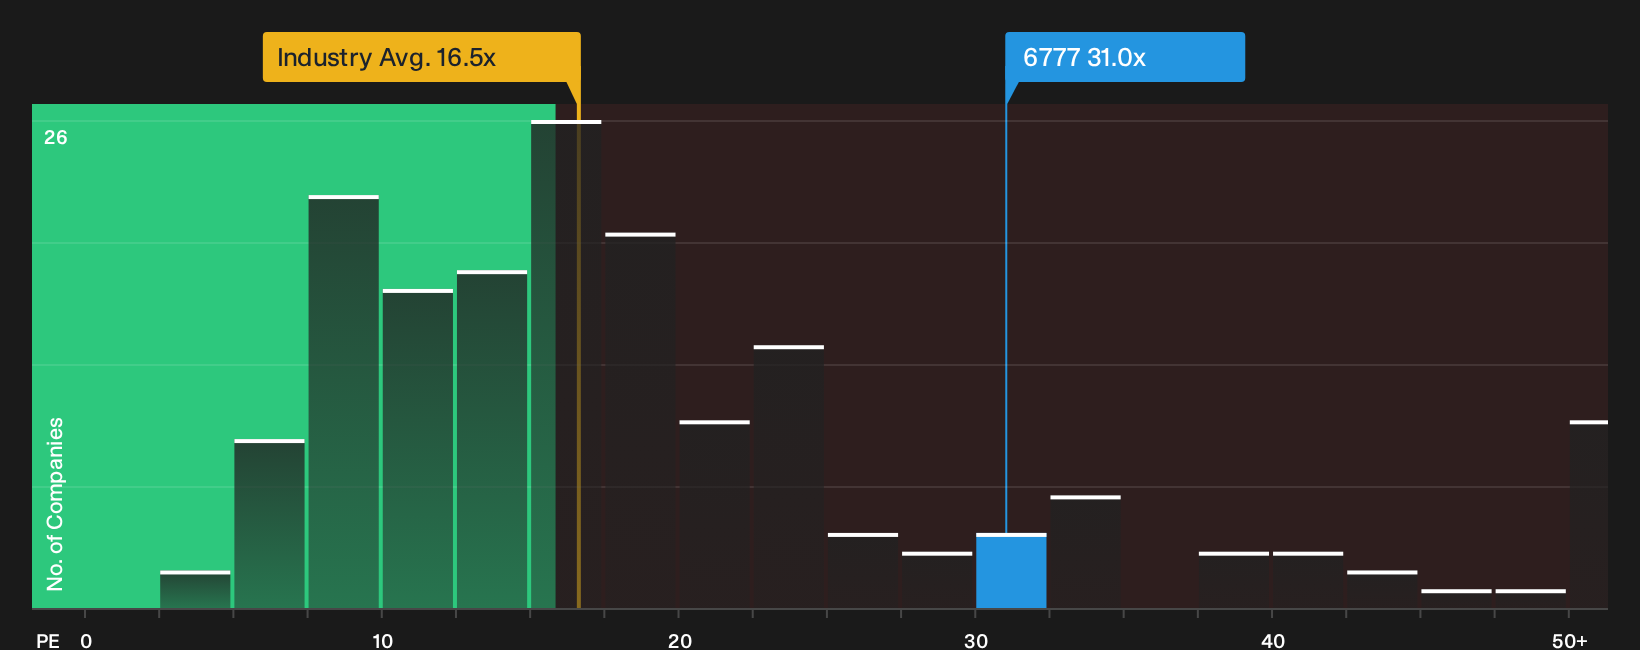
santec Holdings combines high margin optical instruments, a 25.9% net profit margin and 31.2% Return on Equity with forecast earnings growth of 13.45%. That is a profile many large funds tend to overlook in smaller specialists. However, a P/E of 30.9x versus 16.5x for the JP Electronic industry leaves a lot riding on how one invisible assumption about growth and valuation holds up.
With so much riding on that valuation assumption, review the 2 key rewards and 1 important major warning sign to see where expectations could be decoupling from what the business is actually delivering.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout momentum often emerges quietly, under the radar for now, then gets caught once the crowd piles in. Scan these curated screens while it matters and get in early.
- Jump on cash generating opportunities ahead of slower capital by scanning the 12 high quality undervalued stocks curated to highlight resilient businesses before momentum chases the rerating.
- Track resilient operators that aim to keep drawdowns in check and use the 23 resilient stocks with low risk scores to narrow in on sturdier balance sheets before fear spikes.
- Ride structural shifts in automation and manufacturing, and then sort through the hand picked group in the 91 robotics and automation stocks while pricing power and demand are still being repriced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com