
Mitsubishi Electric (TSE:6503) Rides Heat Pump Demand On A Fair Value Debate
Mitsubishi Electric (TSE:6503) has been in focus after two developments. The company is targeting rising demand for heat pumps and helped create an award-winning Radioactive Airborne Particulate Monitor for nuclear facilities.
Recent trading reflects that story. The share price is at ¥5,143 after a 1-day share price return of 1.82%. However, the 90-day share price return has declined 11.74%, while total shareholder return of 32.47% over one year and a very large 5-year total shareholder return suggest that longer term momentum has been strong.
Spot other potential beneficiaries of the heat pump and electrification trend by scanning our hand-picked 43 power grid technology and infrastructure stocks.Given that backdrop, the latest pullback over 90 days and the stronger multi year return raise a practical question. Are buyers now paying for Mitsubishi Electric’s business progress, or for a swing in sentiment that has run ahead of value?
Most Popular Narrative: 25% Undervalued
Against the last close at ¥5,143, the most followed narrative pegs Mitsubishi Electric’s fair value at ¥6,892 using a 7.51% discount rate. That gap frames the recent pullback less as a setback and more as a test of how durable the long-term thesis really is.
Expansion in the Energy Systems and Public Utility segments is driven by ongoing investments in power distribution and the transition toward electrification and energy efficiency, supported by worldwide decarbonization initiatives. This is expected to result in higher recurring revenues and improved net margins as Mitsubishi Electric benefits from secular shifts to sustainable infrastructure.
See why 6 investors see Mitsubishi Electric as 25% undervalued.
Result: Fair Value of ¥6,892 (UNDERVALUED)
Still, two pressure points could easily unsettle that 25% undervalued story: rising lower cost Asian rivals and slower progress in Mitsubishi Electric’s digital pivot.
Find out about the key risks to this Mitsubishi Electric narrative.
Another Angle On Mitsubishi Electric’s Value
The story shifts when you swap the narrative fair value for the SWS DCF model. That cash flow based approach estimates Mitsubishi Electric’s worth at ¥4,108 per share, which is below the current ¥5,143 level and points to an overvalued reading instead of a 25% discount.
The DCF view leans heavily on future cash generation rather than what investors are currently willing to pay for earnings. It therefore highlights more downside risk if cash flows come in weaker than expected. The question for you is simple: Which lens feels closer to how you think this business will actually convert its pipeline into cash?
Look into how the SWS DCF model arrives at its fair value.
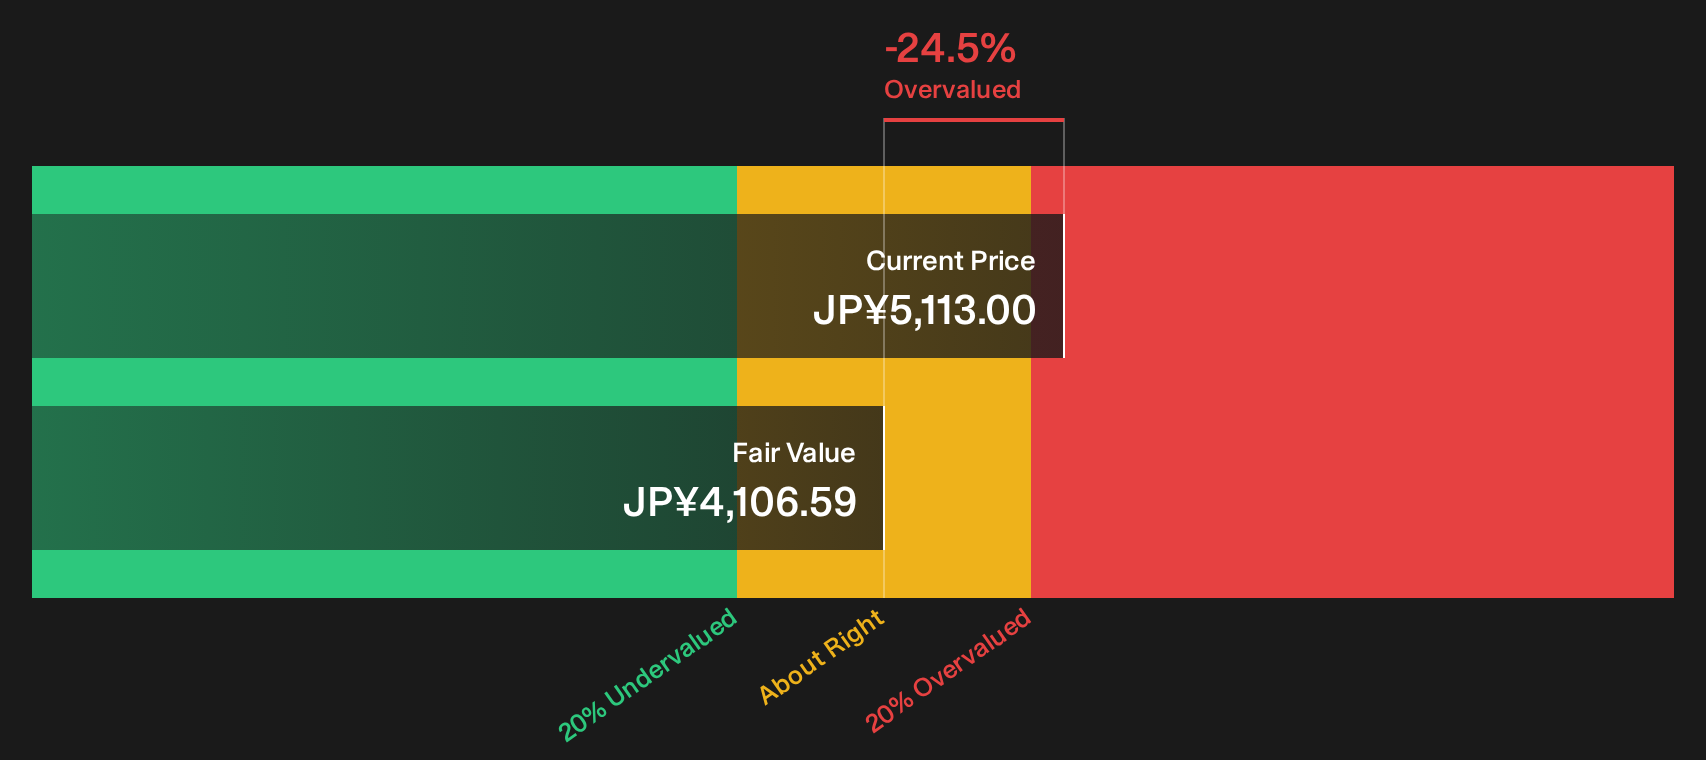
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Mitsubishi Electric’s value story are exactly why you should look at the numbers yourself and decide quickly where you stand. Then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mitsubishi Electric?
If Mitsubishi Electric has sharpened your focus on pricing and risk, it is worth lining up a few more contenders before you commit fresh capital.
- Target higher quality at a discount by scanning companies flagged as potentially underpriced through the 12 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results).
- Get ahead of the crowd by tracking financially robust opportunities that receive less attention via the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com