
Fuji Electric (TSE:6504) Joins Fusion Push As Its Undervalued Narrative Faces A Fresh Test
Fusion partnership puts Fuji Electric in the clean energy spotlight
Fuji Electric (TSE:6504) has taken an investor and Official Partner role in Helical Fusion’s Helix Program, tying the industrial group directly to efforts to commercialise fusion power in the 2030s.
The fusion announcement lands after a strong run in Fuji Electric’s shares, with a 30 day share price return of 14.53% and a year to date gain of 24.19% that has kept momentum building rather than cooling. Over a longer window, total shareholder return of 46.35% over one year and 136.42% over three years shows how consistently the market has rewarded the story so far. The 228.79% five year total shareholder return underlines how much long term holders have benefited from staying invested through earlier phases of the clean energy transition narrative.
Scan for other potential beneficiaries of the clean energy build out by reviewing our curated list of 43 power grid technology and infrastructure stocks.
Bulls see Fuji Electric’s fusion link as a new growth chapter, while bears see an overheated clean energy story. Which case do the current earnings, returns and valuation metrics actually lean toward next?
Most Popular Narrative: 9% Undervalued
Fuji Electric last closed at ¥15,015 and the most followed narrative pegs fair value around ¥16,556. This implies a moderate valuation gap that bulls link to its exposure to electrification and power infrastructure.
A surge in orders and revenue from Energy Management and Power Supply and Facility Systems, driven by increased demand for grid stabilization, storage battery systems, and data centers, positions Fuji Electric for multi-year growth as electrification and infrastructure upgrades accelerate globally. This is likely to support rising top-line revenue and improved operating margins as high-value projects ramp.
See why 5 investors see Fuji Electric as 9% undervalued.
Result: Fair Value of ¥16,556 (UNDERVALUED)
Still, the bullish Fuji Electric story runs into real friction if overseas demand stays soft or if rising fixed and raw material costs continue to squeeze semiconductor profitability.
Find out about the key risks to this Fuji Electric narrative.
Another angle on Fuji Electric’s valuation
The fair value narrative around ¥16,556 paints Fuji Electric as modestly undervalued. A second lens tells a cooler story. Simply Wall St’s DCF model points to a future cash flow value of about ¥12,584 per share, which sits well below the current price of ¥15,015 and screens as overvalued instead. Which yardstick do you put more weight on: earnings multiples or cash flow math?
To see how that cash flow view is built and stress test your own assumptions, take a closer look at the SWS DCF model for Fuji Electric, starting with Look into how the SWS DCF model arrives at its fair value..
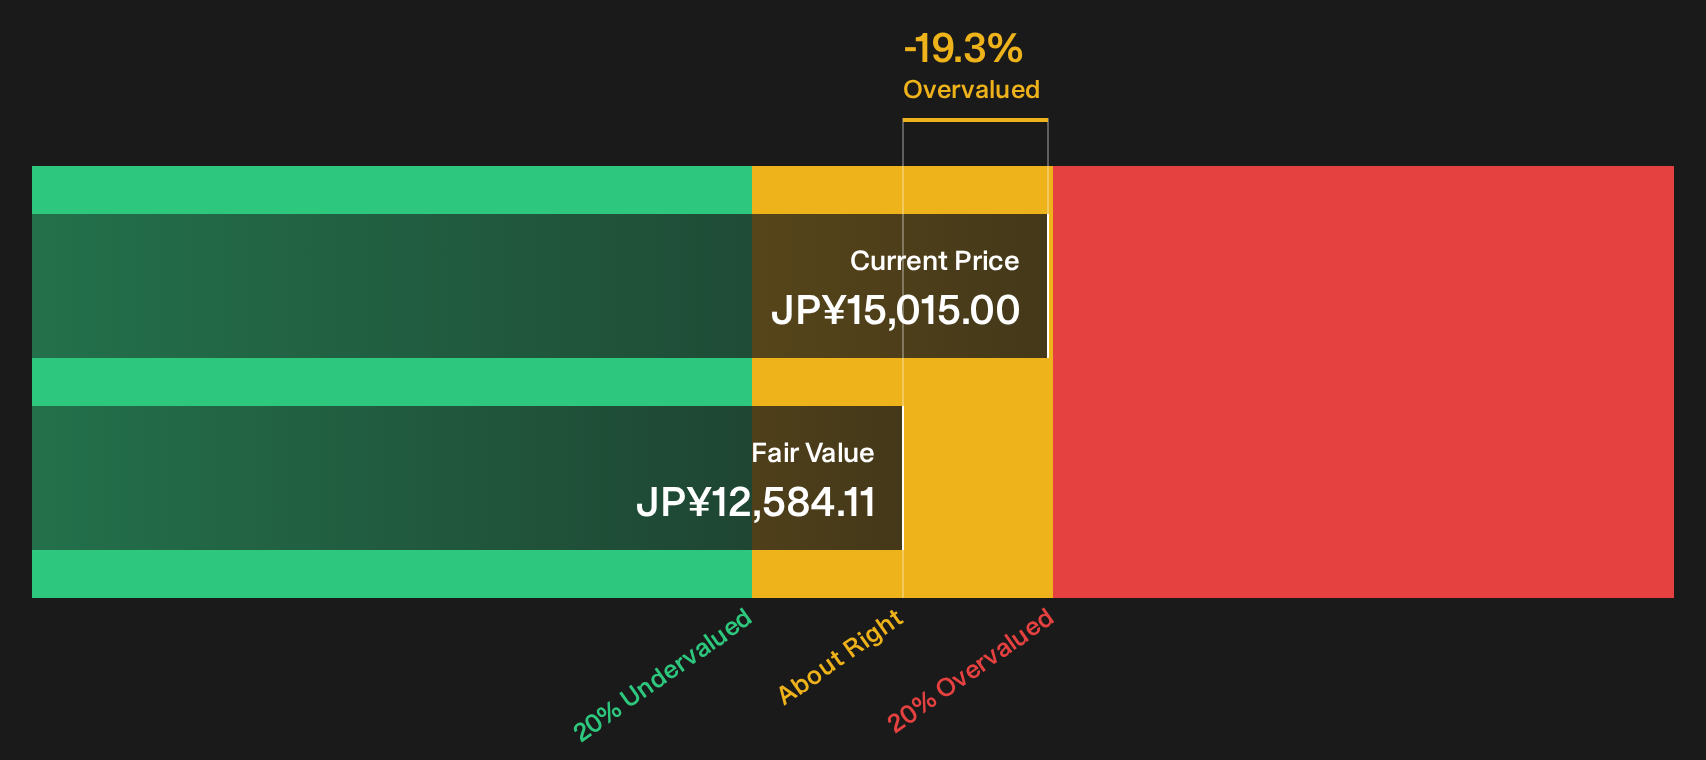
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fuji Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions on Fuji Electric in this piece cut both ways, with real upside and real questions. Act while the debate is fresh by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fuji Electric?
If you stop with Fuji Electric, you only see one angle. Broaden your watchlist with a few focused screens that can surface very different opportunities.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) to filter for financial strength first.
- Hunt for mispriced quality by reviewing the 12 high quality undervalued stocks to highlight companies where fundamentals and price do not fully align.
- Spot early opportunities before the crowd catches on by checking the 74 high quality undiscovered gems to focus on under-the-radar businesses with solid numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com