
Missed Onto Innovation's 114% Rally? Here's The Bet Holders Made
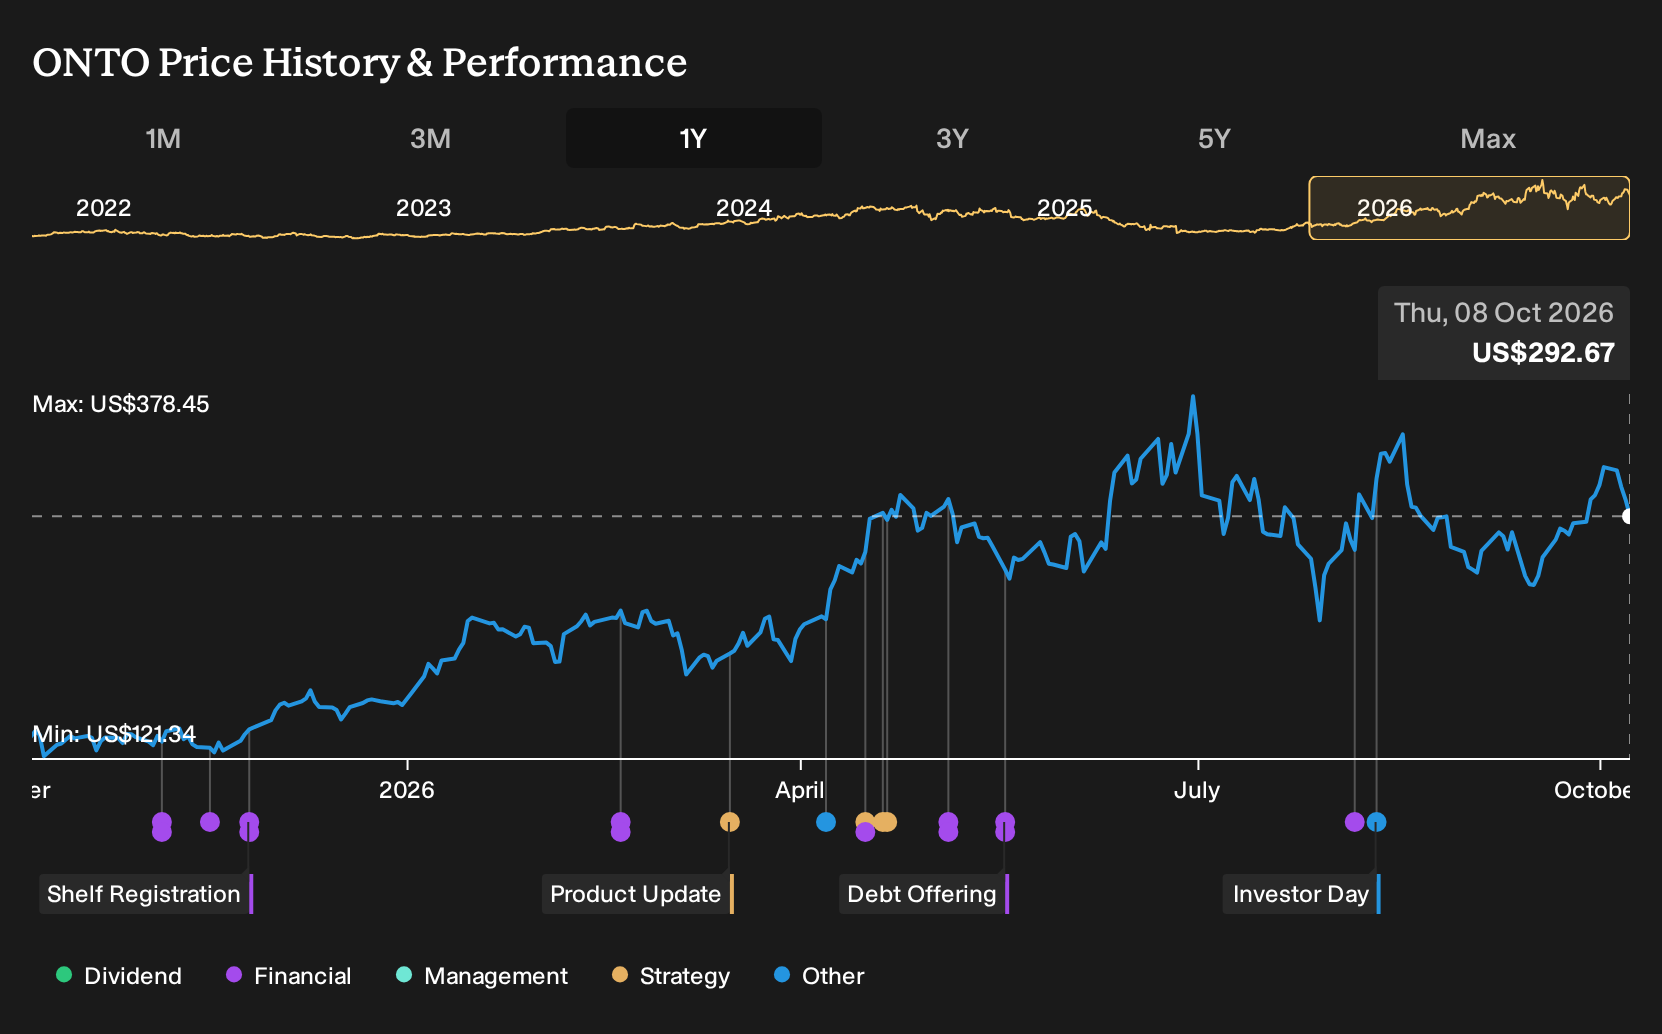
If Onto Innovation looked risky to you back in October 2025, you were not alone, given the split between bullish AI packaging forecasts and warnings about rising costs and customer concentration. For Onto Innovation shareholders, the return over the past year was 114.3%, including dividends. That gain arrived alongside higher recent revenue and net margin, but also fresh worries about overvaluation and governance. If you had been weighing those mixed signals then, what exactly was knowable at the start?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Onto Innovation is not the only name tied to this theme. Zero in on 92 AI infrastructure stocks and compare how each one is priced.
The Two Stories Onto Innovation Investors Had To Weigh
The shares cost US$139 at the start of the period, so anyone looking at Onto Innovation had to decide which future seemed more reasonable based on the information available in May 2025.
On the optimistic side, the bullish Narrative put Fair Value at US$182, 31% above the start price. That view leaned on the Dragonfly platform gaining multi customer pull, plus the Semilab acquisition adding over US$130 million of product revenue and higher margin potential.
The bearish Narrative set Fair Value at US$90, 35% below the start price. This case focused on rising geopolitical and regulatory costs, customer concentration, and tougher competition that could pressure pricing and limit long term profitability for Onto Innovation.
What The Results Changed For Onto Innovation
Onto Innovation’s Q2 2026 figures, with revenue at US$343.1 million and net income at US$60.1 million, leaned toward the optimistic case that argued the business could support higher earnings. Net margin moved from 13.4% in Q2 2025 to 17.5% in Q2 2026, which challenged the more cautious view that rising costs would cap profitability, although it did not resolve long term geopolitical or customer concentration worries. Overall, the evidence cut both ways.
The key assumption investors can lift to other stocks is margin resilience. When a bullish story leans on better profitability, compare the claimed margin path to what actually shows up in the income statement over multiple quarters.
What Onto Innovation’s Price Now Assumes
Onto Innovation trades at US$293 today after a 114.3% gain over the past year, and the selected Narrative’s Fair Value still sits above that level rather than below it.
The Narrative focuses on Onto Innovation’s role at the AI packaging bottleneck and argues today’s price does not fully credit the scale or durability of that position.
"The semiconductor industry is undergoing a structural shift. Historically, scaling performance primarily depended on shrinking transistor sizes. Today, physical scaling limitations are pushing the industry toward advanced packaging approaches in which multiple chips are interconnected in stacked or side-by-side configurations."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - uses device trade-in programs to source premium hardware for recycling channels.
- Company 2 - 39% below our estimate - shifts from specialty film supplier to integrated manufacturer with expanding installer partnerships.
- Company 3 - 31% below our estimate - converts constrained vessel availability and lengthy offshore contracts into stronger day-rate utilization.
Three companies from the same screener. Open all 27 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com